What Happens to Your Investments When Interest Rates Change? 6 Key Effects for Delhi NCR Investors

What happens to your investments when interest rates change, showing the effects on FDs, bonds, debt mutual funds, equity, real estate and gold.
Understand how changing interest rates can affect FDs, bonds, debt mutual funds, equity, real estate and gold.

What happens to your investments when interest rates change? Interest rates affect much more than the returns on your fixed deposit (FD). When the Reserve Bank of India (RBI) changes its policy rates, or market interest rates move for other reasons, the impact can spread across the financial system. Bond prices may change, debt mutual fund NAVs can fluctuate, borrowing costs may rise or fall, and investments such as equity, real estate, and gold can also be affected.

For investors in Delhi NCR, understanding these changes can help make financial decisions more informed. However, the impact depends on the type of investment you hold, your investment horizon, market conditions, and your financial goals.

In this guide, we explain six key effects of interest rate changes on common investment options and what investors should understand before making decisions.

What Do We Mean by Interest Rates?

There is no single interest rate that controls every investment. The RBI’s policy rates influence financial conditions and the broader cost of money, while banks and financial institutions respond according to their funding costs, liquidity, credit demand, and expectations.

Market interest rates are also influenced by inflation, economic growth, government borrowing, and global financial conditions.

For example, when market interest rates rise, new fixed-income investments may offer higher yields. However, existing fixed-rate investments do not necessarily change their contracted returns.

Understanding these differences is an important first step in learning what happens to your investments when interest rates change.

Why Do Interest Rates Matter to Investors?

Interest rates influence the relative attractiveness of different investments, the cost of borrowing and the value investors place on future income.

Consider a bond paying an annual coupon of 7%. If newly issued bonds with similar risk begin offering 8%, the older bond may become less attractive. Its market price would generally need to fall to make its yield competitive with the newer bonds.

This explains a fundamental relationship in fixed-income investing:

When market yields rise, existing fixed-rate bond prices generally fall. When market yields fall, existing fixed-rate bond prices generally rise.

The extent of the price movement depends on factors such as the bond’s maturity, coupon, and duration.

Interest rate changes can affect different investments in different ways. Let’s examine six important effects.

Effect 1: Fixed Deposits (FDs)

Fixed deposits are among the easiest investments to understand when discussing interest rates.

Suppose you book a three-year FD at an annual interest rate of 7%. Six months later, banks begin offering 7.5% on comparable new deposits.

Your existing fixed-rate FD generally continues at its contracted rate until maturity, subject to the deposit terms. You do not automatically start earning the newer rate.

When interest rates rise, new depositors may benefit from higher offered rates, while existing depositors continue earning the rate agreed upon earlier.

When rates fall, investors who previously locked in a higher fixed rate may continue earning that rate until maturity.

Should You Lock in FD Rates?

The decision depends on your investment horizon, liquidity needs, the available rates, and your expectations about future rates.

A fixed-rate FD can provide predictable contractual interest, but premature withdrawal may involve penalties or reduced interest. Reinvestment rates at maturity may also be different from the original rate.

Before choosing an FD, compare its tenure, interest payout options, premature withdrawal conditions, and applicable taxation.

Effect 2: Bonds

Bonds are particularly sensitive to changes in market interest rates.

Suppose you own a bond with a face value of ₹1,000 and an annual coupon rate of 8%. It pays ₹80 in annual coupon interest.

If newly issued bonds with similar risk begin offering 9%, your existing bond becomes less attractive at its original price. Its market price may fall below ₹1,000 so that a new buyer can obtain a more competitive yield.

If comparable market yields subsequently fall to 7%, your 8% coupon bond may become more attractive, potentially increasing its market price.

Do Bond Investors Lose Money When Rates Rise?

Not necessarily. The outcome depends on the bond’s price, the investor’s holding period, and whether the issuer meets its obligations.

If you hold a bond to maturity, its contractual coupon payments and principal repayment remain relevant, subject to the issuer’s ability to pay and the bond’s terms.

However, if you sell before maturity, the prevailing market price can result in a gain or loss.

Bonds also carry other risks, including credit risk, liquidity risk and reinvestment risk. A higher coupon or yield does not automatically mean a bond is suitable for every investor.

Effect 3: Debt Mutual Funds and Duration

Debt mutual funds invest in fixed-income securities such as government securities, corporate bonds and money market instruments, depending on the scheme’s mandate.

Their net asset values (NAVs) can respond to changes in market yields because the prices of the securities they hold may change.

When market yields rise, existing bond prices generally fall, potentially reducing a debt fund’s NAV. When market yields fall, bond prices may rise, potentially supporting the NAV.

However, the actual impact depends on the fund’s holdings, credit quality, duration, expenses, and market conditions.

What Is Duration in Debt Mutual Funds?

Duration is a measure used to understand a fixed-income investment’s sensitivity to interest rate changes. It is not simply the same as the investment’s maturity.

Generally, a fund with higher duration is more sensitive to changes in market yields than a comparable fund with lower duration.

For example, if two funds have similar credit quality but different duration profiles, the longer-duration fund will generally experience a larger price impact from the same yield movement.

This is why understanding a fund’s category and portfolio characteristics matters more than simply knowing that it invests in debt.

What Is Reinvestment Risk?

When interest rates fall, income from maturing bonds may need to be reinvested at lower yields. This is known as reinvestment risk.

Investors evaluating debt mutual funds should therefore consider their investment horizon, liquidity needs, risk tolerance, and the scheme’s investment objective rather than making decisions based only on forecasts of interest rates.

Explore relevant information through the GCIC Finserve website.

Effect 4: Equity

There is no universal rule that rising interest rates always cause stock markets to fall.

Interest rate changes can influence equity valuations and corporate profitability in several ways.

First, higher borrowing costs can increase expenses for companies with substantial debt. This may affect their profitability, investment plans and ability to expand.

Second, higher interest rates can make fixed-income investments relatively more attractive compared with riskier assets. This can influence how investors value equities.

Third, interest rates affect the discount rate used to estimate the present value of future corporate earnings. Companies whose valuations depend heavily on profits expected far into the future can be particularly sensitive to changes in these assumptions.

However, equity markets respond to several factors simultaneously, including earnings growth, economic activity, valuations, liquidity, inflation, and investor expectations.

For example, rising interest rates during a period of strong economic growth may have different implications from rising rates driven by persistent inflation.

Equity investors should therefore avoid making decisions based on interest rates alone.

Effect 5: Real Estate

Interest rates can influence real estate through home loans, commercial financing, and property demand.

For homebuyers in Delhi NCR, higher loan interest rates can increase the EMI on a floating-rate loan or extend its repayment period, depending on the lender’s terms and loan structure. Higher borrowing costs may also reduce the loan amount some buyers can afford.

Lower borrowing costs may improve affordability for some buyers, but they do not guarantee that property prices will rise.

Commercial real estate is also affected by financing costs, rental income expectations, and the returns investors require.

Property prices depend on multiple factors, including location, infrastructure, supply, rental yields, employment opportunities, and broader economic conditions.

Before purchasing property, consider the total cost, loan affordability, liquidity requirements, and intended holding period rather than relying solely on the direction of interest rates.

Effect 6: Gold

Gold behaves differently from investments that pay contractual interest.

Because gold does not pay interest, higher interest rates or rising real yields can increase the opportunity cost of holding it compared with interest-bearing assets.

This relationship can influence gold prices, but it is not consistent in every market environment.

Gold prices can also be affected by inflation expectations, global interest rates, movements in the US dollar, central bank demand, geopolitical uncertainty, and currency fluctuations.

For Indian investors, movements in international gold prices and the rupee can both influence domestic gold prices.

Therefore, gold does not always move in the opposite direction to interest rates.

Investors considering gold should assess its role in their overall portfolio, diversification needs, costs, and risk tolerance rather than assuming it will perform in a particular way when rates change.

Policy Rates vs Market Rates: Why the Difference Matters

The RBI’s policy decisions influence monetary and financial conditions, but the interest rate on a particular bond, FD or loan does not automatically move by the same amount.

Market rates also reflect inflation expectations, government borrowing, credit risk, liquidity and expectations about future monetary policy.

This is why bond yields may move before an RBI announcement or change even when the policy rate remains unchanged.

For investors, it is important to distinguish between:

  • Policy rates: Rates set by the RBI as part of its monetary policy framework.
  • Market yields: Returns available on securities at prevailing market prices.
  • Deposit rates: Rates offered by banks and other deposit-taking institutions under their respective terms.
  • Loan rates: Rates charged by lenders according to the loan agreement, benchmark and applicable conditions.

Understanding these differences helps explain why the effects of interest rate changes are not identical across investments.

For official monetary policy information, visit the Reserve Bank of India.

Should You Change Your Investments When Interest Rates Change?

Not necessarily. Changing investments every time rates move can result in unnecessary transactions, costs, taxes and decisions based on short-term forecasts.

Instead, consider these questions before making a decision:

  1. What is the purpose of the investment? Money intended for a near-term expense may require a different approach from money invested for a long-term goal.
  2. When will you need the money? Your investment horizon can influence how much price fluctuation you can reasonably tolerate.
  3. How sensitive is the investment to interest rates? Consider the duration of debt investments, the terms of your FD and the borrowing exposure of companies or property investments.
  4. Do you need liquidity? An investment that is difficult or costly to exit may not suit money you need at short notice.
  5. Does your portfolio still match your goals and risk tolerance? Review the overall allocation instead of focusing on a single market indicator.

Consider two investors. One holds short-term FDs and short-duration debt investments. Over time, that investor may be able to reinvest maturing money at higher rates if available.

Another investor holds long-duration bonds or debt funds. That investor may experience a more immediate impact on market value when yields rise.

Neither situation is automatically better or worse. The outcome depends on the investor’s needs, the investment’s characteristics and market conditions.

The objective is to understand the risks and make informed decisions, not to predict every interest rate movement.

GCIC Finserve’s Perspective for Delhi NCR Investors

Interest rate movements can affect different investments in different ways. Understanding these effects can help investors evaluate their portfolios in the context of their financial goals, investment horizon, liquidity needs and risk tolerance.

GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705), shares educational information to help investors understand mutual funds and related investment concepts.

For general information about mutual funds and financial services, visit GCIC Finserve.

For official information about monetary policy, visit the Reserve Bank of India. For investor education and securities-market information, refer to SEBI and the Association of Mutual Funds in India (AMFI).

Frequently Asked Questions

1. What happens to bonds when interest rates rise?

Existing fixed-rate bond prices generally fall when comparable market yields rise. The extent of the impact depends on factors such as duration, maturity, coupon and credit quality.

2. Do FD rates change when the RBI changes interest rates?

Banks may revise rates on new deposits in response to market conditions, funding costs and other factors. An existing fixed-rate FD generally continues at its contracted rate until maturity, subject to its terms.

3. What happens to debt mutual funds when interest rates rise?

Rising market yields generally reduce the prices of existing fixed-income securities, which can lower a debt mutual fund’s NAV. Funds with higher duration are generally more sensitive to yield changes, all else being equal.

4. Do falling interest rates always mean stock markets will rise?

No. Equity markets respond to several factors, including corporate earnings, economic growth, valuations, inflation, liquidity and investor expectations. Interest rates are only one influence.

5. Is a higher interest rate always better for investors?

Not necessarily. Higher rates may benefit investors placing new money into certain fixed-income products, but they can also increase borrowing costs and reduce the market value of existing fixed-rate bonds. The impact depends on the investor’s circumstances and investments.

6. Why do bond prices and yields move in opposite directions?

A bond’s contractual coupon generally remains fixed. When its market price falls, a new buyer pays less for the same contractual cash flows, increasing the yield available at that price. When the price rises, the yield generally falls, all else being equal.

Final Word

What happens to your investments when interest rates change depends on what you own and why you own it.

Fixed-rate FDs generally retain their contracted rate, bond prices tend to move inversely to market yields, debt mutual funds respond according to their holdings and duration, and equity, real estate and gold are influenced by a wider range of factors.

You do not need to predict every rate movement to make informed investment decisions. Understanding how interest rates affect your existing investments can help you evaluate risks, review your financial goals, and avoid reacting unnecessarily to short-term market changes.

Disclaimer: This article is intended solely for general educational and informational purposes. It should not be construed as investment, financial, tax, or legal advice, or as a recommendation to buy, sell, or hold any security or investment product. The impact of interest rate movements varies according to market conditions, investment characteristics, and individual circumstances. Market-linked investments are subject to market risks, and past performance is not indicative of future results. Investors should consider their financial goals, investment horizon, liquidity requirements, and risk tolerance before making investment decisions and seek professional guidance where appropriate.

Mutual fund investments are subject to market risks; read all the related documents carefully before investing.
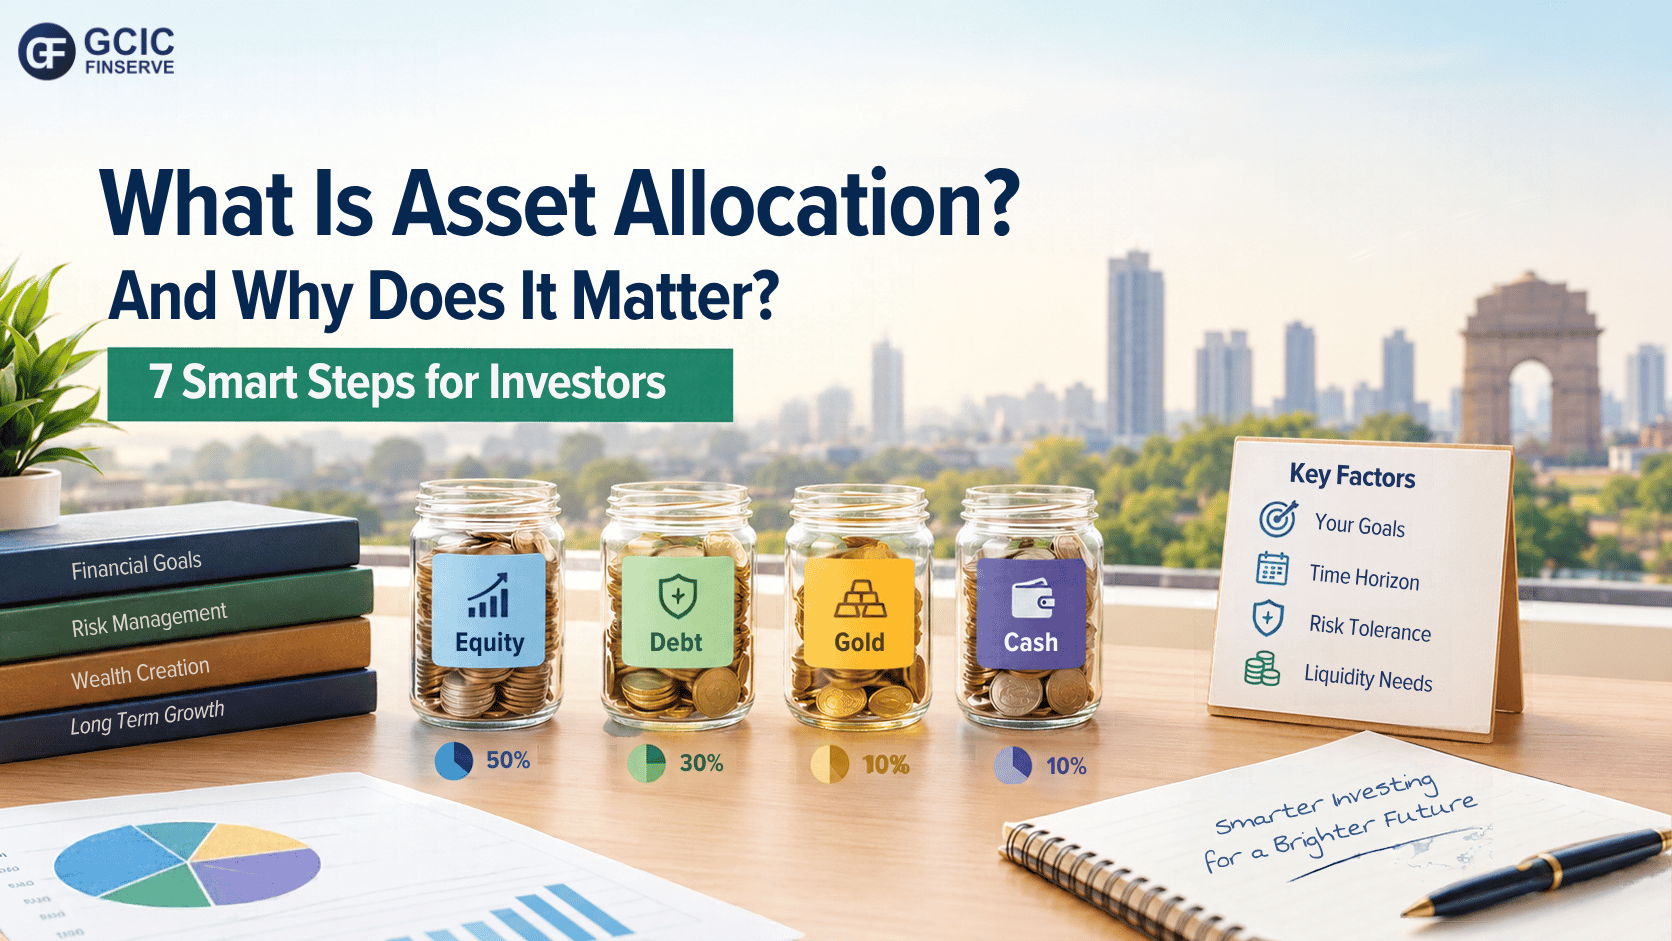
What Is Asset Allocation and Why Does It Matter? 7 Smart Steps for Delhi NCR Investors

What is asset allocation – equity, debt, gold and cash explained for Delhi NCR investors
Understand how asset allocation helps organise investments across different asset classes.

What is asset allocation, and why do experienced investors consider it an important part of financial planning? Investing is often presented as a question of what to buy: which mutual fund, which stock, gold or bonds? But a bigger question comes first: how should your overall money be divided?

Asset allocation is the process of deciding how much to invest across asset classes such as equity, debt, gold and cash. A suitable allocation considers your financial goals, investment horizon, liquidity needs and ability to handle risk. It does not rely on predicting which market or asset class will perform best next.

For Delhi NCR investors managing savings, property, business income and long-term family goals, understanding asset allocation can help bring greater structure to financial decisions.

1. What Exactly Is Asset Allocation?

Imagine you have ₹50 lakh to invest. You could put it all into equity, keep most of it in fixed deposits, buy gold or divide it across different asset classes.

That division is your asset allocation.

For illustration, ₹50 lakh could be divided as follows:

  • Equity: ₹25 lakh (50%)
  • Debt: ₹15 lakh (30%)
  • Gold: ₹5 lakh (10%)
  • Cash or liquid investments: ₹5 lakh (10%)

This is an illustrative example, not a recommended allocation for every investor. The appropriate mix depends on your individual circumstances, financial commitments and investment horizon.

2. Why Does Asset Allocation Matter?

Different investments carry different risks and behave differently under changing economic conditions.

Equity offers long-term growth potential but can experience significant short-term fluctuations. Debt investments may provide income or relative stability, although their risks vary by instrument. Gold may behave differently from equity and debt, potentially adding diversification. Cash and liquid investments can help meet immediate financial needs.

Combining different asset classes can reduce dependence on a single type of investment. However, diversification does not guarantee profits or eliminate losses.

Consider someone planning to use ₹30 lakh for a property purchase in two years. Even if that person chooses well-performing equity funds, investing money needed so soon in volatile assets could create a mismatch between the investment and the goal.

This is why understanding what is asset allocation matters before selecting individual mutual funds or other investment products.

3. The 3 Factors That Shape Your Allocation

There is no universal allocation formula based only on age or income. Three important factors help determine an appropriate approach.

Investment horizon: Money needed within a year has a different purpose from money intended for retirement 15 years away. Each financial goal may require its own allocation.

Risk tolerance and risk capacity: Risk tolerance refers to your emotional comfort with market fluctuations. Risk capacity refers to your financial ability to absorb losses without jeopardising important goals. Both matter when deciding how much risk to take.

Financial goals: Retirement, children’s education, a property purchase and business expansion have different timelines and cash-flow requirements. Your investments should reflect those differences.

Your circumstances can also change. A new child, a business expansion, an inheritance or approaching retirement may require a review of your allocation.

4. The Major Asset Classes

Equity

Equity represents ownership in businesses, either directly through stocks or indirectly through equity mutual funds. It offers growth potential but can fluctuate considerably. It is generally more suitable for goals with a sufficiently long horizon and an ability to withstand market volatility.

Debt

Debt investments involve lending money to a government, company or other borrower. Examples include fixed deposits, government securities, corporate bonds, treasury bills and debt mutual funds.

These instruments can serve different purposes, including income, liquidity and portfolio stability. Their credit, interest-rate and liquidity risks vary, so they should not all be treated as equally safe.

Gold

Gold can be held physically or through eligible financial products such as Gold ETFs and gold mutual funds. It does not generate interest or business profits. Some investors include it as a diversifying asset rather than relying on it as their primary source of long-term growth.

Cash and Liquid Investments

Cash and suitable liquid investments can help cover emergency expenses and foreseeable short-term needs. Accessibility and capital preservation are often more important for this portion of a portfolio than pursuing higher returns.

Real Estate

Real estate is a significant part of wealth for many Delhi NCR families. Property can serve residential or investment purposes, but it may involve substantial capital, transaction costs and limited liquidity.

If a large proportion of your wealth is already tied up in property, that exposure should be considered when reviewing your overall financial position.

You do not necessarily need every asset class. Adding investments simply to make a portfolio appear diversified can increase complexity without necessarily improving it.

5. A Simple Example: Two Investors, ₹1 Crore Each

Consider two hypothetical investors with ₹1 crore each.

Investor A: A 35-year-old with a stable income and a financial goal at least 15 years away may be able to consider a meaningful equity allocation, provided their financial capacity and risk tolerance support it.

Investor B: A 60-year-old expecting to use a substantial portion of their wealth for living expenses over the next few years may need to give greater attention to liquidity and short-term capital fluctuations.

Both investors have the same amount of money, but their financial needs differ.

The lesson is not that a particular age requires a fixed percentage in equity or debt. The purpose of the money, the time available and the investor’s ability to absorb losses should guide the decision.

6. Rebalancing and Common Asset Allocation Mistakes

What Is Rebalancing?

Suppose a hypothetical portfolio begins with 60% equity, 30% debt and 10% gold. After a period of strong equity performance, its allocation changes to 72% equity, 21% debt and 7% gold.

The portfolio now has greater equity exposure than originally intended.

Rebalancing means bringing the portfolio closer to its intended allocation. This may involve directing new investments towards underrepresented assets or selling some holdings, after considering taxes, costs and individual circumstances.

Rebalancing is not a method of predicting the market. It is a way to maintain a portfolio structure that continues to fit your objectives.

Strategic asset allocation establishes a longer-term target. Tactical asset allocation involves temporary changes based on market views and can be difficult to execute consistently.

Common Mistakes to Avoid

  • Chasing recent performance: Buying an asset simply because it has recently delivered strong returns.
  • Taking excessive risk: Choosing an allocation that becomes difficult to maintain during market declines.
  • Ignoring inflation: Overlooking how rising living costs can affect long-term financial goals.
  • Overlooking existing wealth: Ignoring property, business ownership and other assets when assessing total exposure.
  • Never reviewing the portfolio: Failing to reassess investments after significant financial or family changes.

7. 7 Steps to Build an Asset Allocation

Step 1: List your financial goals. Identify what you are investing for, such as retirement, education, property or business needs.

Step 2: Assign a time horizon. Estimate when you will need the money for each goal.

Step 3: Assess liquidity requirements. Keep suitable provisions for emergencies and foreseeable expenses.

Step 4: Understand your risk capacity. Consider your income stability, financial obligations, existing assets and ability to absorb losses.

Step 5: Decide your broad asset mix. Evaluate the role of equity, debt, gold, cash and any other relevant assets in your overall financial position.

Step 6: Select suitable investments. Only after establishing the broad allocation should you compare individual products, costs, risks and investment features.

Step 7: Review and rebalance periodically. Revisit your allocation at appropriate intervals and after major life events or changes in financial goals.

These steps provide a framework for organising financial decisions. They do not replace an individual assessment of suitability.

GCIC Finserve’s Perspective for Delhi NCR Investors

Investors in South Delhi, Gurugram, Noida and other parts of Delhi NCR may have different financial priorities, from retirement planning and children’s education to property purchases and business expansion.

At GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705, subject to verification of current registration details), investors can explore mutual fund categories and understand how different investment options relate to their financial goals and time horizons.

To learn more about mutual fund categories and investor education, visit AMFI India.

Frequently Asked Questions

Q1. What is asset allocation in simple terms?

Asset allocation means dividing your investments among different asset classes, such as equity, debt, gold and cash, according to your goals, time horizon and risk profile.

Q2. Is asset allocation the same as diversification?

No. Asset allocation determines how money is divided among broad asset classes. Diversification involves spreading investments across different holdings or exposures to reduce concentration risk. Neither guarantees protection against losses.

Q3. What is the best asset allocation?

There is no single best allocation for everyone. It depends on financial goals, investment horizon, risk tolerance, risk capacity, liquidity requirements, liabilities and existing assets.

Q4. Should young investors invest mostly in equity?

Age alone should not determine an allocation. A younger investor may have a longer investment horizon, but income stability, financial responsibilities and the ability to tolerate losses also matter.

Q5. What is portfolio rebalancing?

Portfolio rebalancing means adjusting investments when their actual proportions move away from the intended allocation. It can help keep the portfolio aligned with its objectives and risk profile.

Q6. How often should asset allocation be reviewed?

The review frequency depends on individual circumstances and the investment strategy. Periodic reviews and reassessments after major life events can help determine whether the allocation remains appropriate.

Final Word

So, what is asset allocation? It is the process of deciding how your overall wealth should be distributed before choosing individual investments.

Instead of trying to predict the next winning asset class, the objective is to build a portfolio that reflects your financial goals, investment horizon, liquidity needs and ability to handle risk.

A thoughtful allocation can help bring discipline to investment decisions, but it cannot guarantee returns or prevent losses. Reviewing your overall financial position regularly is an important part of keeping your investment approach aligned with changing needs.

Disclaimer: This article is intended solely for general educational and informational purposes. It does not constitute investment, financial, tax or legal advice, or a recommendation to buy, sell or hold any security or investment product. The examples and asset allocations discussed are illustrative only and may not be suitable for every investor. Investment decisions should take account of individual financial goals, investment horizon, liquidity requirements, risk profile, liabilities and existing assets. Market-linked investments are subject to market risks, and diversification does not guarantee returns or eliminate the risk of loss. Please read the relevant scheme documents carefully before investing and consult an appropriately qualified financial professional where necessary.

Jio IPO 2026: Dates, Price Band & 5 Key Risks to Know

Jio IPO 2026 investor guide
Understand the reported Jio IPO details and key risks before making an investment decision.

The Jio IPO 2026 is attracting attention from investors across India, including Delhi NCR, as Jio Platforms Limited prepares to enter the public markets. The company operates in India’s telecommunications and digital services ecosystem, making its proposed public issue an important development for investors following the technology and telecom sectors.

However, a well-known brand or a large IPO does not automatically make an investment suitable for every investor. Before considering an application, it is important to understand the offer details, the business, the valuation and the risks described in the official offer document.

This article provides an educational overview based on information available as of 17 October 2026. IPO details can change, so readers should verify the latest official disclosures before making a decision.

Jio IPO 2026: Key Details

Jio Platforms Limited has filed its Red Herring Prospectus (RHP), and the reported public subscription window is scheduled for 21–23 October 2026. The reported price band is ₹1,065–₹1,119 per share. Investors should verify all final details against the official RHP and price-band advertisement before applying.

Key reported details include:

  • Company: Jio Platforms Limited
  • Reported IPO dates: 21 October to 23 October 2026
  • Reported price band: ₹1,065–₹1,119 per share
  • Issue structure: Fresh issue of up to 27 crore equity shares
  • Indicative issue size: Approximately ₹28,755 crore to ₹30,213 crore, based on the reported share count and price band
  • Use of proceeds: Primarily repayment or prepayment of borrowings at Reliance Jio Infocomm, with the balance for general corporate purposes

These figures are indicative and should not replace the official offer documents. Confirm the final issue size, lot size, application categories, reservation details, allotment timeline and listing date from official disclosures.

For the latest information, read the Jio Platforms RHP on SEBI’s website and visit the official Jio IPO information page.

What Is Jio Platforms?

Jio Platforms is part of the Reliance group’s digital services ecosystem. Its business is associated with telecommunications, digital connectivity and platforms supporting India’s expanding digital economy.

When evaluating the Jio IPO 2026, investors should look beyond the company’s brand recognition and customer base. Revenue growth, profitability, cash flow, capital expenditure, debt, competitive positioning and future expansion plans are also important.

The official offer document provides detailed information about the company’s business, financial performance, material risk factors and the proposed use of IPO proceeds.

Why Is the Jio IPO 2026 Attracting Attention?

1. India’s digital economy

Demand for mobile connectivity, data consumption, and digital services may create business opportunities. However, future growth depends on competition, pricing, customer behaviour and the company’s ability to convert demand into sustainable earnings.

2. Scale and market position

Jio has an established presence in India’s telecom market. Investors should examine how that position translates into revenue, profitability and potential long-term shareholder returns.

3. Technology and new services

Cloud services, digital platforms, and artificial intelligence may provide growth opportunities. These areas also involve investment costs, execution challenges, and uncertainty about future earnings.

4. Valuation and investor expectations

Even a strong business can deliver disappointing investment returns if its shares are purchased at a price that already assumes very high future growth. Investors should evaluate valuation alongside the company’s financial performance and risks.

5 Things to Check Before Applying for the Jio IPO 2026

1. Read the Red Herring Prospectus

Review the company’s financial statements, business operations, use of proceeds, outstanding legal matters and material risk factors. Avoid relying only on news headlines, social media posts or informal market commentary.

2. Evaluate the valuation

Compare relevant financial measures with suitable listed companies, while recognising that businesses differ in scale, growth, profitability and operations. A high-profile IPO is not automatically attractively priced.

3. Understand the business risks

Review risks relating to telecom regulation, competition, pricing, technology investment, data protection, cybersecurity and the company’s ability to execute its plans. Consider how these factors could affect future business performance.

4. Consider your financial position

An IPO application should not interfere with emergency savings, essential expenses or other financial commitments. Consider how much of your overall portfolio would be exposed to one company and whether that concentration fits your risk tolerance.

5. Avoid grey market speculation

Grey Market Premium (GMP) is unofficial and may be unreliable. It does not guarantee the listing price, allotment, or profit. Avoid basing an investment decision solely on GMP or predictions of listing gains.

Is the Jio IPO 2026 Suitable for Every Investor?

No single IPO is suitable for every investor. Suitability depends on individual financial goals, investment horizon, risk tolerance, liquidity needs, and existing portfolio exposure.

Investors should distinguish between a company’s popularity and the potential return available at its offer price. Listing gains are uncertain, and shares may trade below the issue price after listing.

Rather than applying because of market excitement, investors should review the official offer document, understand the risks, and consider their overall financial circumstances before making a decision.

About GCIC Finserve

GCIC Finserve is an AMFI-registered Mutual Fund Distributor (ARN-272705) and SIF Distributor and an APMI-registered PMS Distributor (APRN-08140), serving investors across Delhi NCR.

This article is intended to provide general information about a public offer and is not a recommendation to apply for the Jio IPO. Readers can visit the GCIC Finserve website to learn about its mutual fund and PMS distribution services.

For official IPO information, consult SEBI, NSE India, and BSE India.

Frequently Asked Questions

1. When is the Jio IPO expected to open?

The reported subscription window is 21–23 October 2026. Verify the dates in the latest official offer documents before applying.

2. What is the reported Jio IPO price band?

The reported price band is ₹1,065–₹1,119 per share. Confirm the final price band and application requirements through official disclosures.

3. What is the reported Jio IPO issue size?

Based on the reported fresh issue of up to 27 crore shares and the reported price band, the indicative issue size is approximately ₹28,755 crore to ₹30,213 crore. Refer to the RHP for definitive details.

4. Does the Jio IPO 2026 guarantee listing gains?

No. Allotment and post-listing performance are uncertain. Investors may incur losses, including if the shares list or trade below the issue price.

5. Where can investors find official Jio IPO information?

Investors can consult the company’s official IPO information page, the SEBI RHP, and relevant NSE and BSE disclosures. Read the applicable offer document before making an investment decision.

Conclusion

The Jio IPO 2026 is an important development for investors tracking India’s telecom and digital services sectors. However, the size of an IPO, a recognized brand, and strong market interest should not replace a careful review of financial performance, valuation, and risk factors.

Investors should rely on official disclosures, assess their own financial circumstances, and avoid making decisions based only on short-term market expectations.

Disclaimer: This article is for educational and informational purposes only. It is not investment advice, a recommendation to apply for the Jio IPO, an offer to sell securities, or a solicitation to buy securities. Equity investments involve market risks, and returns are not guaranteed. IPO details may change; please refer to the latest official offer documents and regulatory disclosures before making any investment decision. Read all applicable offer documents carefully.

Is Your Investment Portfolio Properly Diversified? 7 Simple Tests for Delhi NCR Investors

is your investment portfolio properly diversified
Seven practical tests to review portfolio diversification and concentration risk.

Is your investment portfolio properly diversified, or does it only look that way? Many investors believe they’re diversified because they own several mutual funds, a few stocks, some FDs, and maybe gold. But owning many investments doesn’t automatically mean you’re diversified. You could hold ten mutual funds and still have most of your money in the same companies. You could own several stocks and be heavily exposed to one sector. True diversification isn’t about how many investments you own; it’s about how many different risks your portfolio is exposed to.

What Does Diversification Actually Mean?

Diversification means spreading investments across assets, companies, sectors, and markets so your wealth doesn’t depend too heavily on one outcome. If you hold ten banking stocks, you own ten investments, but one sector downturn could hit most of your money at once. Compare that with ₹20 lakh split between equity, debt, and gold, with the equity spread across sectors. Different sources of risk and return make that portfolio much closer to genuine diversification. So is your investment portfolio properly diversified? Let’s find out.

Test 1: How Is Your Total Wealth Allocated?

Start with asset allocation before looking at individual products. Say you have ₹30 lakh in equity mutual funds, ₹10 lakh in direct stocks, ₹5 lakh in FDs, and ₹5 lakh in gold. That looks like four types of investments, but 80% of the portfolio is in equity. If your mutual funds also hold many of the same companies as your direct stocks, the real equity concentration could be even higher. Whether 80% equity is appropriate depends on your goals, time horizon, and risk capacity, but it’s worth knowing the real number.

Test 2: Are Your Mutual Funds Overlapping?

One of the most common problems in Indian portfolios is owning a large-cap fund, a flexi-cap fund, a multi-cap fund, a large and mid-cap fund, and an index fund, all at once. That sounds diversified, but these funds can hold many of the same large companies. This is called portfolio overlap: different investments with significant exposure to the same underlying securities. Some overlap is normal. The question is whether it’s intentional and reasonable, or whether adding more funds is just adding more complexity.

Test 3: Are You Too Dependent on One Sector?

You may own 30 or 40 different companies, but if nearly two-fifths of your equity sits in financial services, a prolonged downturn in that sector could hit your overall portfolio hard. A diversified portfolio doesn’t need equal exposure to every sector, but large concentrations should be a deliberate choice, not an accident.

Test 4: Are You Overexposed to One Company?

This matters especially for direct-stock investors. Suppose you hold ₹20 lakh in Company A directly and ₹60 lakh across mutual funds. If those funds also hold Company A, your actual exposure is higher than the ₹20 lakh you see in your demat account. When concentration is substantial, look through to the underlying holdings of your funds.

Test 5: Is Your Debt Portfolio Diversified Too?

Diversification isn’t only about equity. Two FDs and two corporate bonds are four investments, but you should still ask: who are the issuers, what’s the credit quality, when do they mature, are they exposed to the same economic risks, and how much of your wealth depends on one institution? Several debt instruments don’t make a diversified portfolio if most of the money rests on a handful of issuers.

Test 6: What Happens If the Market Falls?

One of the simplest tests is to imagine stress. If equity markets fall sharply, how much of your total wealth falls with them? If almost everything you own is linked directly or indirectly to equity, you may have more exposure than you realise. Then ask: what if interest rates rise (important for longer-duration debt), what if the sector I’m heavily in faces a downturn, and what if I need a large amount of money during a correction? These questions reveal risks that a simple list of investments won’t show. Also remember that diversification is about time too: money needed for a child’s education in two years needs more attention to stability and liquidity than money you won’t touch for 15 years.

Test 7: Is Your Total Family Wealth Diversified?

For many Indian families, real estate is a large share of wealth. If your financial portfolio looks diversified but three properties make up 70% of family wealth, you’re still concentrated in real estate. The same applies to business owners: with a ₹10 crore business and ₹2 crore of other investments, family wealth is still heavily dependent on the business, and possibly on one industry for both income and net worth. Investment-portfolio diversification and total-wealth diversification aren’t always the same thing.

Two Portfolios, Same ₹50 Lakh

Portfolio A has a large-cap fund, a flexi-cap fund, an index fund, a mid-cap fund, direct stocks, and an FD. It looks diversified because there are six investments, but the equity portion may overlap heavily. Portfolio B holds diversified equity, debt and FDs, gold, and liquid investments, with fewer products but potentially wider spread across asset classes. Which suits a particular investor depends on goals and risk profile, but the principle holds: more products don’t automatically mean more diversification.

When Does a Portfolio Need Rebalancing?

Even a well-diversified portfolio drifts. Start with 60% equity, 30% debt, and 10% gold, and after a strong equity run it could become 75% equity, 18% debt, and 7% gold. You didn’t choose that extra equity risk; the market did. Rebalancing means bringing the portfolio back toward an allocation that fits your objectives and risk profile. It doesn’t mean selling everything that has done well. Note too that diversification reduces concentration risk but can’t eliminate losses: in a broad global decline, several asset classes can fall together.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, AMFI-registered Mutual Fund Distributor (ARN-272705), we help Delhi NCR investors understand how their mutual fund holdings fit together, including category choices and overlap. Connect with our team to discuss your mutual fund holdings. For official fund category and portfolio disclosure information, refer to AMFI India.

FAQs

Q1. How many mutual funds should I own to be diversified? There’s no fixed number. Adding funds with similar holdings may increase complexity without improving diversification.

Q2. Is owning different mutual fund categories enough? Not necessarily. Different categories can still have overlapping holdings, so actual portfolio exposure matters more than fund names.

Q3. How can I check mutual fund overlap? Compare the underlying holdings of your funds and spot companies and sectors that appear repeatedly. Many portfolio tools offer overlap analysis.

Q4. Can too much diversification be a problem? Yes. Too many investments can make a portfolio hard to monitor, create overlap, and obscure the actual risks.

Q5. Should I rebalance every year? Not necessarily. It depends on how far your allocation has drifted from the intended one, and a periodic review can show when rebalancing may be appropriate.

Final Word

A properly diversified portfolio isn’t the one with the most investments. It’s one where your money is deliberately spread across assets, companies, sectors, and risks to match your goals. The real test: if one company fails, one sector struggles, rates rise, or equity markets fall, how much of your overall wealth is affected? That tells you far more than the number of statements in your drawer.

Disclaimer: This article is for general educational and informational purposes only and should not be construed as investment, financial, or tax advice. There is no single asset allocation or diversification strategy suitable for every investor. Mutual fund and other market-linked investments are subject to market risks, and diversification does not guarantee profits or eliminate losses. Please consider your goals, horizon, liquidity needs, and risk profile, and consult a qualified financial professional where appropriate.

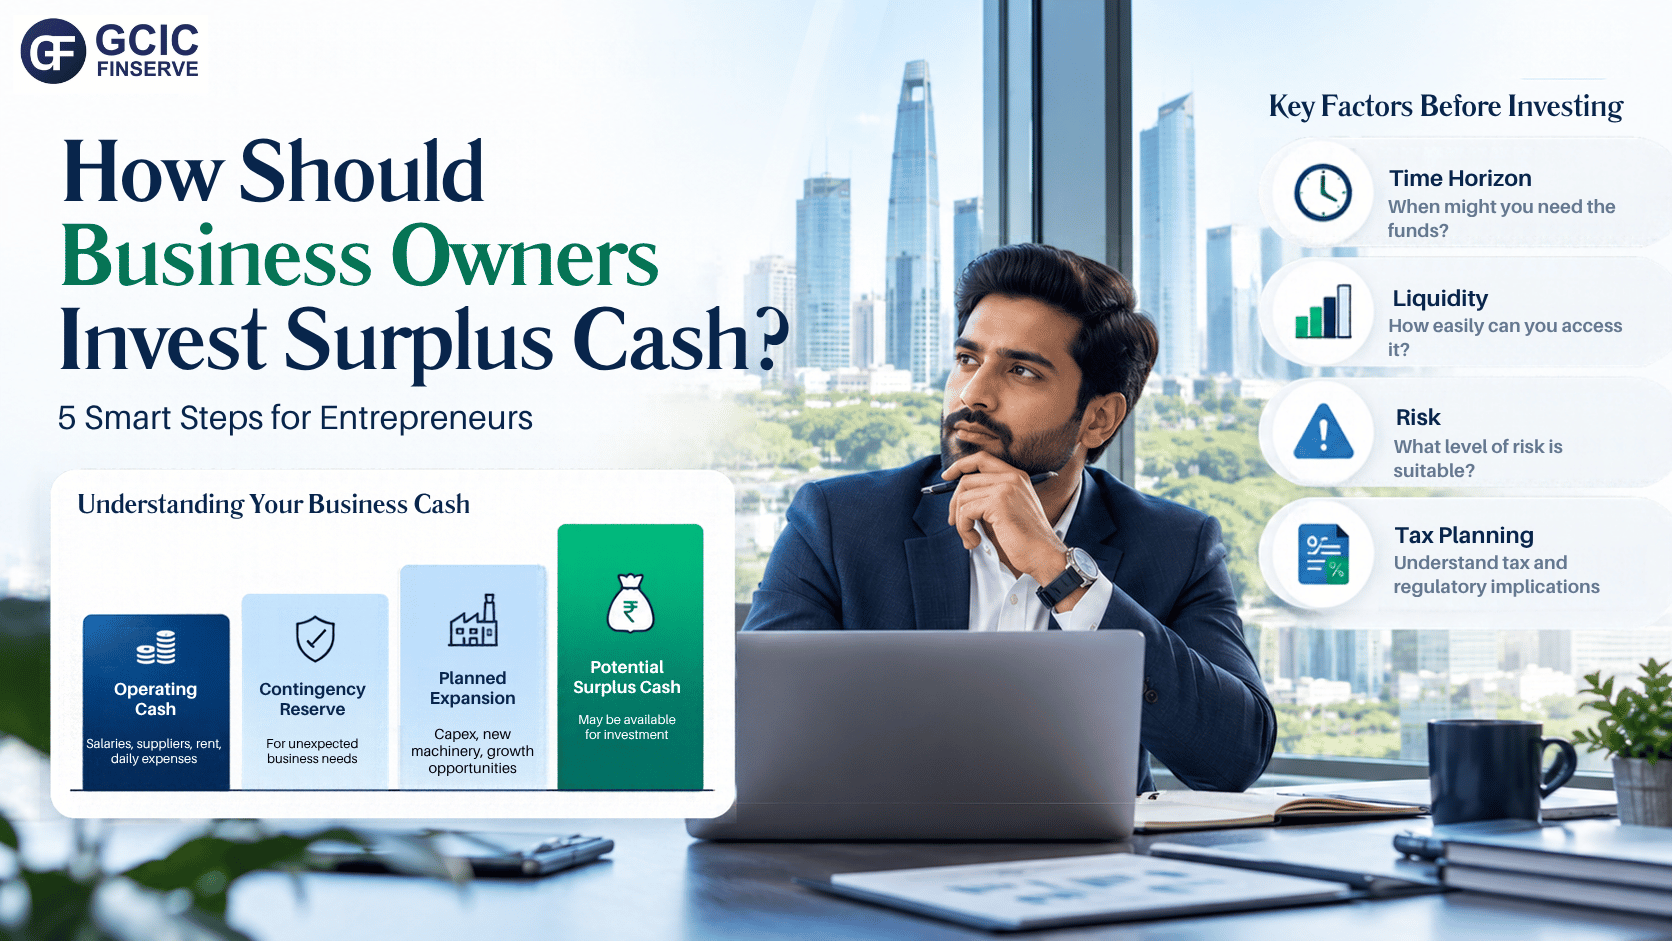
How Should Business Owners Invest Surplus Cash? 5 Smart Steps for Delhi NCR Entrepreneurs

How should business owners invest surplus cash – financial planning for Delhi NCR entrepreneurs
Business owner in Delhi NCR reviewing surplus cash investment options, operating cash, contingency reserves, liquidity, risk and tax planning – GCIC Finserve Limited.
Explore 5 smart steps for Delhi NCR business owners to manage surplus cash, maintain liquidity, evaluate investment options and plan for long-term financial goals.

How should business owners invest surplus cash? It is a different question from the one a salaried investor might ask. A business owner in Delhi, Gurugram, or Noida may have ₹25 lakh, ₹1 crore, or even ₹5 crore sitting in a bank account. It can look like idle money that should be invested immediately. However, not all cash in a business account is genuinely surplus.

Some money is needed for salaries, inventory, supplier payments, taxes, loan repayments, or business expansion. Only after these requirements are considered can a business owner assess how much money may be available for investment.

For Delhi NCR entrepreneurs, the objective is to understand the business’s cash requirements, protect liquidity, and evaluate investment options according to the purpose and time horizon of the funds.

What Is Surplus Cash?

Surplus cash is money that a business does not reasonably expect to need for its normal operations or known financial commitments over the relevant period.

Consider a manufacturer with ₹3 crore in its bank account. The business estimates that it needs ₹80 lakh for working capital, ₹40 lakh for salaries and operating expenses, ₹30 lakh for taxes, and ₹50 lakh for new machinery.

After accounting for these requirements, approximately ₹1 crore remains as potential surplus cash.

This is only an illustrative calculation. Actual requirements may change with customer collections, supplier terms, business conditions, debt repayments, and unexpected expenses.

The important point is that a large bank balance does not automatically mean a large investable surplus. Business owners should first understand which funds are committed and which may genuinely be available for investment.

Business Cash vs Personal Wealth

Business finances and personal finances serve different purposes.

Business cash supports working capital, salaries, inventory, supplier payments, taxes, debt obligations, and planned capital expenditure.

Personal wealth may include personal bank deposits, mutual funds, shares, bonds, real estate, gold, and other investments held by the owner.

Keeping these finances separate helps business owners understand their financial position more clearly. It also reduces the risk of investing money that the business may need at short notice.

Before moving company funds into personal investments, owners should understand the legal, accounting, tax, and ownership implications with their chartered accountant and other qualified professionals.

Step 1: Calculate How Much Cash the Business Actually Needs

The first step in deciding how should business owners invest surplus cash is to calculate the amount that can potentially be invested without compromising business operations.

A practical starting point is to divide available cash into three categories.

1. Operating cash

This covers routine expenses such as salaries, rent, supplier payments, utilities, and other immediate commitments. It generally needs to remain readily accessible.

2. Contingency cash

This is a reserve for unexpected expenses, delayed customer payments, temporary revenue declines, or other business disruptions. The appropriate amount depends on the company’s circumstances.

3. Potential surplus cash

This is the amount left after accounting for operating requirements, contingency reserves, taxes, debt obligations, and planned expenditure. Its investment suitability depends on when the money might be needed.

The right balance varies by business. A manufacturer with long receivable cycles may need a larger cash buffer than a professional-services firm with predictable collections. A seasonal business may also need to retain additional liquidity before its peak period.

Do not invest working capital simply because it appears idle. Money received today may already be required for supplier payments over the next few months.

Step 2: Match Surplus Cash to Your Time Horizon

Once potential surplus has been identified, the next question is when the money might be required.

Different investment products have different liquidity characteristics, risks, costs, and tax implications. The following categories are general educational examples, not personalised investment recommendations.

  • Short-term requirements—up to 12 months: Business owners may examine options focused on liquidity and capital preservation, such as suitable bank deposits or other short-duration instruments. Terms, early-withdrawal conditions, and risks should be checked.
  • Medium-term requirements — 1 to 3 years: Suitable options may include deposits or selected debt-oriented investments, depending on the required access to funds, credit risk, interest-rate risk, and tolerance for fluctuations.
  • Longer-term requirements — 3 to 5 years or more: Diversified equity-oriented investments may be considered where the investment horizon and risk profile can accommodate market volatility and potential losses.
  • Long-term wealth planning: Eligible investors may also explore portfolio management services (PMS), alternative investment funds (AIFs), or other investment structures after reviewing their features, eligibility requirements, liquidity restrictions, fees, and risks.

These time ranges are broad illustrations, not fixed suitability rules. Even long-term investments can lose value, and some products may be difficult to exit when funds are needed.

Step 3: Understand the Available Investment Options

There is no single investment product that suits every business owner. Understanding the main features and limitations of different options can help make the evaluation more structured.

Fixed Deposits

Fixed deposits may be considered when the amount, expected holding period, and access requirements are relatively clear. Interest terms generally depend on the institution, deposit type, and tenure.

Business owners should examine the institution’s financial position, premature-withdrawal conditions, applicable deposit-insurance limits, taxation, and concentration of deposits. A stated interest rate should not be confused with a guarantee against every possible risk.

Debt Mutual Funds

Debt mutual funds invest in debt and money-market instruments. Their portfolios can differ in maturity, credit quality, interest-rate sensitivity, and liquidity.

Unlike a bank deposit with contractual terms, a debt mutual fund’s net asset value can fluctuate. Investors should review the scheme’s portfolio, risk factors, expenses, and redemption conditions before considering an investment.

Corporate Bonds

Corporate bonds are debt instruments issued by companies. Their risks may include default, credit-rating changes, interest-rate movements, and limited secondary-market liquidity.

A higher stated yield does not necessarily mean a better investment. Issuer financials, repayment terms, maturity, credit quality, and the ability to exit the investment should all be evaluated.

Equity Mutual Funds

Equity mutual funds invest primarily in shares and can experience substantial market fluctuations.

They may be relevant for genuinely long-term investment objectives, subject to the investor’s risk profile and financial position. Money required for next year’s factory expansion or supplier payments should not be exposed to equity-market volatility merely in pursuit of higher returns.

Portfolio Management Services (PMS)

PMS involves portfolio management under a specific service arrangement and applicable regulatory requirements. Portfolio construction, investment approach, fees, reporting, and risks can differ across providers and strategies.

PMS is not automatically better than mutual funds. Investors should examine the applicable eligibility requirements, service agreement, investment strategy, costs, and potential losses before making a decision.

Alternative Investment Funds (AIFs)

AIFs cover different investment strategies and asset classes, which may include private equity, venture capital, and private credit.

Depending on the fund, these investments may involve longer holding periods, limited liquidity, complex structures, and significant risks. Applicable eligibility requirements, minimum investment amounts, fees, and fund-specific terms should be verified in the relevant offering documents and regulations.

Gold and Other Assets

Gold and other assets may form part of a broader personal wealth portfolio, depending on an investor’s circumstances and objectives. Their role should be assessed alongside existing business interests, property holdings, and other investments rather than in isolation.

Step 4: Review Concentration and Liquidity Risks

Business owners can already have substantial financial exposure to a single business, industry, or geographical market.

For example, an owner of a manufacturing company may have most of their wealth tied to that company. Investing a large part of the family’s remaining portfolio in the same industry could increase concentration risk.

Diversification should therefore be considered across the broader financial position, including business ownership, real estate, deposits, shares, mutual funds, and other assets.

Liquidity is equally important. An investment that is difficult to sell may be unsuitable for funds that could be required unexpectedly.

Before investing, business owners should consider:

  • How much of their wealth depends on the performance of their business.
  • Whether their investments are concentrated in similar industries or asset classes.
  • How quickly invested money may need to be accessed.
  • Whether a potential loss could affect business operations or family financial goals.
  • Whether the costs and risks of an investment are appropriate for its intended purpose.

The aim is to understand the combined financial picture rather than evaluate every investment account separately.

Step 5: Coordinate Investment and Tax Planning

The decision to retain surplus funds within a company or distribute them for personal investment can have tax, accounting, legal, and ownership implications.

The appropriate approach depends on the business structure, the nature of the funds, applicable tax rules, and the owner’s financial circumstances.

Before transferring significant sums or making long-term commitments, coordinate with your chartered accountant and qualified tax or legal professionals. Review the relevant documentation and consider how the proposed transaction could affect the company’s cash flow and financial obligations.

Tax treatment can differ across investment products and may change over time. Decisions should be based on the rules applicable to the particular investor and transaction rather than general assumptions about tax efficiency.

A Practical Example: Investing ₹5 Crore of Business Cash

Consider a hypothetical business owner with ₹5 crore in available cash.

After reviewing the company’s requirements, the owner identifies:

  • ₹1.5 crore for working capital.
  • ₹50 lakh for taxes and near-term obligations.
  • ₹1 crore for a planned manufacturing line.
  • ₹50 lakh as a contingency reserve.

This leaves approximately ₹1.5 crore as potential surplus cash.

That figure is a starting point, not an automatic investment amount. The owner must still consider future cash-flow requirements, business risks, the time horizon, the overall financial position, and the legal and tax implications of investing the funds.

Only after these factors have been assessed can suitable options be evaluated.

This illustrates the difference between investing money that happens to be in a bank account and making a considered decision about genuinely available surplus.

Common Mistakes Business Owners Should Avoid

1. Treating the entire bank balance as surplus: Some of the money may already be committed to operations, taxes, debt, or expansion.

2. Chasing the highest advertised return: A higher potential return can involve additional credit, market, liquidity, or other risks.

3. Assuming fixed deposits eliminate every risk: Deposit terms, institutional exposure, insurance limits, early-withdrawal conditions, and taxation still matter.

4. Investing short-term money in volatile products: Funds required for near-term business commitments should be evaluated differently from long-term wealth.

5. Ignoring the owner’s existing exposure: A business owner may already have substantial wealth tied to one company, industry, or property market.

6. Overlooking costs and taxes: Product charges, transaction costs, taxation, and withdrawal conditions can affect the overall outcome.

7. Mixing company and personal finances without professional review: Transfers and distributions should be considered in the context of the business’s legal and tax structure.

How GCIC Finserve Supports Investment Awareness in Delhi NCR

GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN-272705) and an APMI-registered PMS Distributor (APRN-08140). Its distribution-related activities are subject to the applicable registrations and requirements.

For business owners in South Delhi, Gurugram, Noida, and the wider Delhi NCR region, understanding the differences between mutual funds, fixed deposits, bonds, PMS, and AIFs can be an important part of evaluating investment options.

You can explore the GCIC Finserve website and its mutual fund information to learn more about the available categories.

Before making a decision, assess your business’s liquidity requirements, investment horizon, financial position, and risk tolerance. Product selection should follow this assessment, not replace it.

For official regulatory information, refer to the Securities and Exchange Board of India (SEBI) and the applicable scheme or product documentation.

FAQ

1. How should business owners invest surplus cash?

Start by identifying operating requirements, contingency reserves, taxes, debt obligations, and planned expenditure. Then assess the remaining amount against the time horizon, liquidity requirements, risk tolerance, and existing financial exposure before evaluating investment options.

2. Should business owners invest surplus cash in fixed deposits?

Fixed deposits may be considered for certain liquidity and capital-preservation requirements, subject to the institution’s terms and applicable risks. The appropriate amount depends on the business’s cash-flow needs, deposit conditions, taxation, and overall financial position.

3. How much emergency cash should a business keep?

There is no universal amount suitable for every business. The required reserve depends on operating expenses, receivable and payable cycles, revenue stability, debt obligations, seasonality, and access to financing.

4. Can business owners invest surplus cash in equity mutual funds?

Equity mutual funds may be considered for longer-term objectives where the investor can tolerate market fluctuations and potential losses. Funds required for operations or near-term capital expenditure should be assessed separately.

5. Is PMS suitable for business owners?

PMS may be considered by eligible investors after reviewing the service arrangement, applicable eligibility requirements, strategy, fees, risks, and liquidity. It is not automatically more suitable than mutual funds or other investment options.

6. Can business owners invest surplus cash in AIFs?

Some business owners may be eligible to consider AIFs, depending on the applicable rules and the particular fund. These investments can involve complex strategies, significant risks, and limited liquidity. Relevant offering documents and eligibility requirements should be reviewed carefully.

7. Should a business owner invest all surplus cash at once?

Not necessarily. The decision depends on the investment objective, cash-flow outlook, market exposure, and time horizon. Some investors may consider investing over time, but no single approach is appropriate for every situation.

8. Should surplus cash remain in the company or be invested personally?

This depends on the business structure, cash requirements, tax treatment, ownership considerations, and the owner’s personal financial position. Consult a qualified chartered accountant and relevant legal or tax professionals before moving significant amounts.

Final Takeaway

For business owners, surplus cash is money that remains available after the business’s financial requirements have been considered.

The process is straightforward in principle: understand cash flow, protect operating liquidity, identify potential surplus, establish the time horizon, and then evaluate investment options according to their risks and costs.

For entrepreneurs in Delhi NCR, the goal is not simply to pursue higher returns. It is to make informed financial decisions while preserving the ability of the business to meet its commitments and pursue future opportunities.

Disclaimer: This article is for educational and informational purposes only and should not be construed as investment, financial, tax, accounting, or legal advice, a personalised recommendation, or a solicitation to invest. Investment decisions should be based on individual objectives, financial circumstances, risk tolerance, liquidity needs, and applicable product documentation. Mutual Fund investments are subject to market risks; read all scheme-related documents carefully before investing. Market-linked investments can lose value, and past performance does not guarantee future returns. Fixed deposits and other products also have terms and risks that should be reviewed. Tax laws and regulations may change. Consult qualified professionals where appropriate. GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN-272705) and an APMI-registered PMS Distributor (APRN-08140); activities are subject to applicable registrations and requirements.
FD vs Debt Mutual Funds: 6 Key Differences Every Delhi NCR Investor Must Know

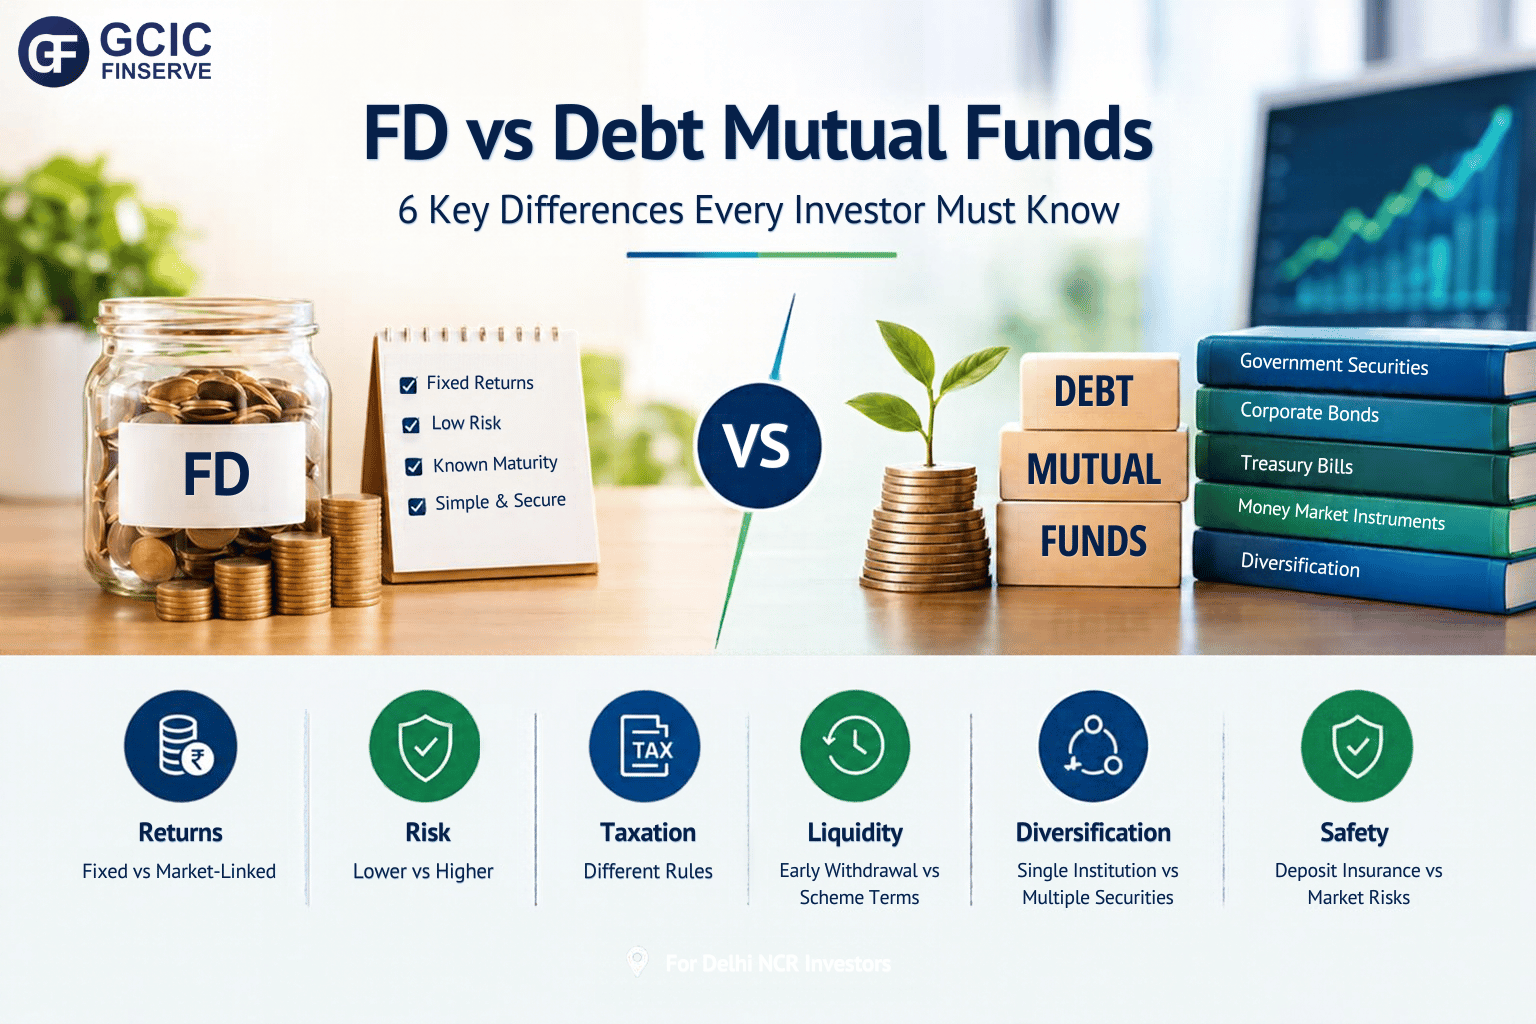
FD vs debt mutual funds comparison highlighting returns, risk, taxation, liquidity, and diversification.
Compare fixed deposits and debt mutual funds to understand their returns, risks, and suitability.

FD vs debt mutual funds is a common question for investors who want to manage their money without taking direct exposure to the stock market. Both options can play a role in the conservative part of a portfolio, but they work differently.

A fixed deposit (FD) offers a contracted interest rate for a chosen tenure, subject to the institution’s terms. A debt mutual fund invests in fixed-income securities, and its returns depend on the income and market value of those investments.

So, which option is right for you? The answer depends on your financial goals, investment horizon, liquidity needs, risk tolerance and tax situation.

Table of Contents

  1. What Is a Fixed Deposit?
  2. What Is a Debt Mutual Fund?
  3. FD vs Debt Mutual Funds: 6 Key Differences
  4. Can You Lose Money in a Debt Mutual Fund?
  5. Taxation, Liquidity and Safety
  6. Which Option May Suit Your Needs?
  7. Frequently Asked Questions

1. What Is a Fixed Deposit?

A fixed deposit is an investment in which you deposit money with a bank or eligible financial institution for a specified period at an agreed interest rate.

For example, if you invest ₹10 lakh in an FD at an illustrative interest rate of 7% per annum for three years, the applicable interest and maturity amount can generally be calculated in advance, subject to the FD’s terms and compounding method.

This predictability makes FDs useful for people who prefer knowing their expected returns.

However, premature withdrawal may result in a penalty or reduced interest. Also, the safety of an FD depends on the institution and applicable protections.

Eligible bank deposits are insured by the Deposit Insurance and Credit Guarantee Corporation (DICGC) up to ₹5 lakh per depositor per bank, including principal and interest, subject to applicable rules.

Learn more through the official DICGC website.

2. What Is a Debt Mutual Fund?

A debt mutual fund pools money from investors and invests it in fixed-income instruments such as government securities, corporate bonds, treasury bills, certificates of deposit and money-market instruments.

Unlike an FD, a debt mutual fund does not offer a guaranteed rate of return or promise that your invested capital will remain unchanged.

Different categories of debt funds have different risk profiles. For example, liquid funds generally invest in short-term instruments, while longer-duration funds may be more sensitive to changes in interest rates.

Before investing, understand the scheme’s portfolio, investment strategy, credit quality, duration and associated risks.

3. FD vs Debt Mutual Funds: 6 Key Differences

The following comparison explains how these two investment options differ.

Factor Fixed Deposit Debt Mutual Fund
Returns Contracted interest rate for the tenure Market-linked returns; not guaranteed
Capital value Generally predictable under the deposit terms NAV can rise or fall
Risk Institution and deposit-related risks Interest-rate, credit and liquidity risks
Liquidity Premature withdrawal may have conditions or penalties Redemption subject to scheme terms and applicable timelines
Taxation Interest generally taxable according to applicable rules Tax depends on fund classification, acquisition date and applicable tax law
Diversification Exposure to the depositing institution Can spread investments across multiple securities and issuers

Neither option is automatically better for every investor. The right choice depends on what you expect the money to achieve.

4. Returns: Fixed Interest vs Market-Linked Performance

One of the main differences in FD vs debt mutual funds is how returns are determined.

With an FD, the applicable interest rate is generally agreed upon when you make the deposit. This makes it easier to estimate the maturity amount.

Debt mutual fund returns are different. They depend on interest income from the underlying securities, changes in their market prices, expenses and other portfolio factors.

For example, when market interest rates fall, existing fixed-rate bonds may become more valuable, potentially increasing a debt fund’s NAV. When interest rates rise, bond prices may fall, reducing the NAV.

Therefore, debt mutual funds can deliver positive or negative returns over a particular period. Higher returns are never guaranteed.

5. Can You Lose Money in a Debt Mutual Fund?

Yes. Debt mutual funds are not risk-free, and their NAV can decline.

Three important risks to understand are:

  • Interest-rate risk: Bond prices generally fall when market interest rates rise, all else being equal.
  • Credit risk: A bond issuer may experience financial difficulties or fail to meet its payment obligations.
  • Liquidity risk: Some securities may be difficult to sell quickly at a reasonable price, especially during stressed market conditions.

These risks vary between schemes. A liquid fund, a short-duration fund and a credit-risk-oriented fund may have very different portfolios and risk characteristics.

Read the scheme’s current Scheme Information Document (SID), portfolio disclosures and risk information before investing.

For more information, visit AMFI India, the Association of Mutual Funds in India.

6. Taxation, Liquidity and Safety

Taxation

FD interest is generally taxable according to the applicable income-tax rules. Tax deducted at source (TDS) may apply where relevant.

Debt mutual fund taxation depends on factors such as the fund’s classification, the date of acquisition and the prevailing tax provisions. Do not assume that debt mutual funds automatically provide a tax advantage over FDs.

Check the latest rules and consider your individual tax situation before making a decision. You can consult the Income Tax Department’s official website.

Liquidity

FDs may allow premature withdrawal, but the applicable conditions, penalties and interest adjustments depend on the institution and deposit terms.

Debt mutual funds generally allow redemptions according to the scheme’s terms. However, exit loads, applicable settlement timelines and restrictions may apply to certain schemes.

Remember that the ability to redeem an investment does not guarantee that you will receive your original invested amount.

Safety

An FD offers greater predictability regarding its contracted interest rate and maturity terms, but it is not automatically risk-free. Deposit insurance applies only within the applicable eligibility and coverage limits.

A debt mutual fund carries market and portfolio risks, and its NAV can fluctuate.

Before choosing either option, assess the risks you can reasonably accept and when you will need the money.

Diversification: An Important Advantage of Debt Mutual Funds

Diversification is another consideration when comparing FDs and debt mutual funds.

If you place your money in one FD, your deposit exposure is concentrated in that institution. A debt mutual fund may invest across several securities, issuers and maturity profiles.

This can help diversify certain risks, but it does not eliminate the possibility of losses. A fund may still be affected by interest-rate movements, credit events or liquidity problems.

Diversification should therefore be considered alongside portfolio quality, investment costs and the scheme’s objectives.

Which Option May Suit Your Needs?

Your investment decision should begin with the purpose of the money.

An FD may be worth considering if:

  • You prefer a known interest rate for a specified tenure.
  • You want to plan for a future expense with predictable maturity terms.
  • You prefer a straightforward deposit product.
  • You understand the withdrawal conditions and institution-related risks.

A debt mutual fund may be worth considering if:

  • You want exposure to a diversified portfolio of debt securities.
  • You understand that NAV can fluctuate.
  • You want to explore different debt fund categories and maturity profiles.
  • You can select a scheme whose risk characteristics match your investment horizon and objectives.

Before investing in a debt mutual fund, review its credit quality, portfolio concentration, duration, expense ratio and exit load. Do not select a long-duration fund simply because you want to park money for a few weeks or months.

Neither option is suitable for every financial goal, and your overall asset allocation also matters.

FD vs Debt Mutual Funds: Frequently Asked Questions

1. Is a debt mutual fund the same as an FD?

No. An FD is a deposit with an agreed interest rate and tenure, while a debt mutual fund invests in a portfolio of fixed-income securities. Its NAV can fluctuate.

2. Are debt mutual funds risk-free?

No. Debt mutual funds carry interest-rate, credit and liquidity risks. The extent of these risks depends on the scheme’s investments and strategy.

3. Can debt mutual funds give higher returns than FDs?

They can outperform FDs over some periods, but this is not guaranteed. Debt fund returns are market-linked, and investors may experience losses.

4. Which is safer: an FD or a debt mutual fund?

They involve different risks. An FD offers greater predictability of contracted interest and maturity terms, while a debt mutual fund has market-linked NAV and portfolio risks. Eligible bank deposits also have limited DICGC insurance protection, subject to applicable rules.

5. Should I move all my FDs into debt mutual funds?

Not necessarily. Consider your financial goals, investment horizon, liquidity requirements, risk tolerance, tax position and existing investments before making any changes.

6. Which option is better for short-term savings?

The answer depends on when you need the money, how much certainty you require and the risks you can accept. Compare the specific FD terms and the characteristics of any debt fund under consideration rather than assuming that one option is always better.

GCIC Finserve’s Perspective for Delhi NCR Investors

For investors in South Delhi and across Delhi NCR, choosing between an FD and a debt mutual fund should begin with a clear understanding of financial goals, liquidity needs and risk tolerance.

At GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705), we focus on helping investors understand mutual fund options and how they may fit into their broader financial plans.

If you need help understanding mutual fund categories and their associated risks, connect with GCIC Finserve to learn more.

Final Word

FD vs debt mutual funds is not about finding one universal winner. It is about matching an investment to the purpose of your money.

An FD offers a contracted interest rate and predictable maturity terms, subject to its conditions. A debt mutual fund provides exposure to a portfolio of debt securities, with market-linked returns and the possibility of NAV fluctuations.

Before investing, ask yourself three questions: When will I need the money? How much uncertainty can I accept? And how does this investment fit into my overall financial plan?

Make the objective clear first, and then evaluate the product.

Disclaimer: This article is for educational and informational purposes only and does not constitute investment, tax, legal or financial advice. Mutual fund investments are subject to market risks, including possible loss of principal. Returns are not guaranteed, and past performance does not assure future results. Fixed deposits are subject to the terms of the respective institution and applicable regulations; deposit insurance is subject to eligibility and prescribed limits. Tax laws may change. Please assess your financial goals and risk profile and consult an appropriately qualified professional before making investment decisions.

Are Indian Markets Too Expensive Right Now? 5 Honest Answers Every Delhi NCR Investor Should Know

Indian market valuation and investment planning for Delhi NCR investors
Understanding Indian market valuations, investment risks and long-term financial planning.

Are Indian markets too expensive right now? It is a question many investors ask when stock-market valuations appear high or the Nifty 50 is trading near elevated levels.

The concern is understandable. Nobody wants to invest a large amount just before a major market correction. At the same time, waiting indefinitely for markets to become “cheap” can also create its own challenges.

The more useful question is not simply whether Indian markets look expensive. It is whether current valuations are supported by earnings, business growth, economic conditions and your own investment horizon.

For investors in Delhi NCR and elsewhere, understanding this difference can help bring more perspective to market decisions.

What Does “Expensive” Mean in the Stock Market?

When investors describe a market as expensive, they are generally talking about valuation.

One commonly used measure is the Price-to-Earnings (P/E) ratio. It compares a company’s share price with its earnings per share.

For example, if a company earns ₹10 per share and its share price is ₹200, its P/E ratio is 20.

But valuation should not be viewed in isolation.

A company or market trading at a higher valuation may still have the potential to grow its earnings over time. Similarly, a low valuation does not automatically mean that an investment is attractive.

Therefore, when asking, “Are Indian markets too expensive right now?” investors should look beyond a single valuation number and consider earnings growth, economic conditions, business fundamentals, and their own financial objectives.

Investors can also review their broader financial assessment and investment planning before making decisions based on short-term market movements.

1. Are Indian Markets Too Expensive Right Now?

There is no single valuation measure that can conclusively tell investors whether the entire Indian market is “too expensive.”

Indian equities can trade at valuations above or below their historical averages at different points in the market cycle. Valuations can also differ significantly between sectors and individual companies.

For this reason, describing the entire market as either “cheap” or “expensive” can oversimplify a much more complicated situation.

A better approach is to consider questions such as:

  • Are corporate earnings growing?
  • Are current valuations supported by business fundamentals?
  • What are the broader economic conditions?
  • How much volatility can you tolerate?
  • When will you actually need the invested money?

Market valuation is therefore one factor to consider, not a standalone investment decision.

For official market information, investors can refer to NSE India and its publicly available market and research resources.

2. Why Waiting for a Correction Can Be Difficult

Suppose you believe the market is expensive and decide to wait for a correction.

The market may fall eventually. But it may also remain elevated or move higher before any meaningful correction occurs.

This creates a common dilemma.

If markets rise while you remain on the sidelines, you may later feel pressure to invest at an even higher level. If markets fall sharply after you invest, you may question whether waiting would have been better.

The important point is that short-term market movements are difficult to predict consistently.

Even when valuations appear stretched, investors cannot know exactly when a correction will occur or how deep it will be.

That is why investment decisions are generally better considered in the context of financial goals, time horizon, and risk tolerance rather than a single prediction about the next market move.

3. Can a Market Grow Into Its Valuation?

Yes, this can happen.

Consider a simplified example.

A company earns ₹10 per share and trades at ₹200, giving it a P/E of 20.

If the company’s earnings increase to ₹15 per share while its share price remains at ₹200, its P/E would fall to approximately 13.3.

The share price did not fall. Instead, the underlying earnings increased.

Real markets are much more complex because prices reflect expectations about future earnings, interest rates, economic conditions, and investor sentiment.

Nevertheless, the example demonstrates an important point:

Today’s valuation does not by itself determine tomorrow’s market return.

A market that appears expensive today can become more reasonably valued if earnings grow. Equally, valuations can remain elevated or become more stretched if investor expectations rise faster than underlying earnings.

4. What Should Long-Term Investors Focus On?

A short-term market participant may ask:

“What will the market do next?”

A long-term investor may need to ask a different question:

“What am I investing for, and how long can I remain invested?”

Equity markets can experience substantial declines over shorter periods. Investors may therefore experience periods of volatility, sometimes lasting for extended periods.

This is why an investment horizon matters.

Money required for a near-term financial commitment may need to be treated differently from money being invested for a long-term goal.

Instead of trying to predict every market high and low, long-term investors can focus on:

  • Financial goals
  • Investment horizon
  • Risk tolerance
  • Asset allocation
  • Diversification
  • Portfolio suitability
  • Ability to remain invested during market volatility

Historical market performance can provide context, but it does not guarantee future returns.

If you are reviewing your existing investment approach, you can also explore GCIC’s financial assessment to understand the broader factors that may need to be considered.

5. How Regular Investing Can Help Manage Timing Risk

Regular investing can be one way of reducing the pressure associated with trying to identify the “perfect” entry point.

When markets are higher, a fixed investment amount buys fewer units. When prices are lower, the same amount can buy more units.

This does not remove market risk and does not guarantee profits.

However, for investors whose financial goals and risk profile are suitable for regular investing, investing systematically can reduce dependence on making a single large timing decision.

The appropriate approach can vary from one investor to another, particularly when dealing with a significant lump sum.

For general investor education and mutual fund-related information, investors can also refer to AMFI.

What Should You Consider When Markets Look Expensive?

There is no universal answer.

If You Are Already Invested

A higher market valuation by itself may not necessarily mean that an investor should make a wholesale change to their portfolio.

It may be more useful to review whether the existing asset allocation remains aligned with the investor’s financial goals, investment horizon and risk profile.

If You Invest Regularly

Market valuations can be one factor to monitor, but stopping a long-term investment plan solely because markets appear expensive may not be appropriate for every investor.

The decision should be considered in the context of the investor’s objectives and overall financial plan.

If You Have a Large Lump Sum

Investing a large amount at one point exposes the investor to the market conditions prevailing at that time.

Depending on the investor’s circumstances, financial objectives, and risk profile, a phased approach may be considered instead of making a decision based entirely on a market-level valuation.

This is not a universal recommendation. The appropriate approach depends on individual circumstances.

If You Need the Money Soon

This may be the most important question.

If money is required for a near-term financial goal, the discussion should not be limited to whether Indian markets are expensive.

The more fundamental question is whether equity-market exposure is suitable for that particular goal and time horizon.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve Limited, we believe market valuation should be considered as part of a broader investment discussion rather than treated as the only factor.

For investors in Delhi NCR, investment decisions can be evaluated around financial goals, time horizon, risk profile, asset allocation, and the ability to remain invested through different market conditions.

As an AMFI-registered Mutual Fund Distributor (ARN-272705), GCIC Finserve Limited provides mutual fund distribution services. Investors should evaluate the suitability of any investment based on their own circumstances and available product information.

You can contact GCIC Finserve to learn more about the services available and discuss your financial requirements.

For official market information, investors can refer to NSE India. For general mutual fund investor information, AMFI is another useful official industry resource.

FAQ

1. Are Indian markets too expensive right now?

Indian market valuations can appear elevated when compared with certain historical measures, but there is no single valuation metric that can conclusively determine whether the entire market is “too expensive.” Valuation should be considered alongside earnings, economic conditions, investment horizon and risk.

2. Should I stop my SIP because the market looks expensive?

Valuation alone may not be sufficient to decide whether to stop a long-term investment plan. Financial goals, investment horizon, risk tolerance and overall asset allocation should also be considered.

3. Is it better to wait for a market correction before investing?

A correction may provide lower prices, but there is no reliable way to know when a correction will occur, how large it will be or how long an investor may need to wait. Investment decisions should therefore not depend solely on predicting the next market correction.

4. Can expensive markets become reasonably valued without falling?

Yes. If corporate earnings grow while market prices remain relatively stable, valuation multiples can decline over time. However, future earnings growth is uncertain and should not be treated as a guaranteed outcome.

5. Do Indian markets always go up in the long run?

No. Equity markets can experience significant declines and prolonged periods of volatility. Historical performance should not be interpreted as a guarantee of future returns.

Final Word

Are Indian markets too expensive right now?

The honest answer is that valuation levels deserve attention, but the word “expensive” does not automatically mean “do not invest.”

For a long-term investor, the more useful questions are:

What is the goal?
How long can the money remain invested?
What level of risk can be accepted?
Is the portfolio appropriately diversified and aligned with the investor’s circumstances?

Market cycles will continue to change. Instead of attempting to predict every market high and low, investors can focus on the factors they can actually control: their goals, time horizon, risk tolerance and investment approach.

Disclaimer

This article is for educational purposes only and should not be considered investment advice or a recommendation. Past performance does not guarantee future returns. Investors should consider their financial goals, risk profile and investment horizon before investing. Mutual Fund investments are subject to market risks, read all scheme related documents carefully. GCIC Finserve Limited is an AMFI-registered Mutual Fund Distributor (ARN: 272705).

Why Do You Need a Wealth Partner? 6 Signs Every Growing Delhi NCR Investor Should Watch For

Wealth partner helping an investor organize and manage multiple financial goals
A wealth partner can help bring investments, goals, and financial decisions together.

Why do you need a wealth partner? It’s a question that rarely comes up when you’re just starting out—a few SIPs, a bank account, maybe an insurance policy, and time doing the rest of the work. But as income grows across Delhi NCR’s fast-moving professional and business circles, financial lives rarely stay that simple. Money starts sitting across different institutions—a business, property, insurance, and retirement assets—and the question quietly shifts from “where should I invest?” to “how should all of my wealth work together?”

What Does a Wealth Partner Actually Mean?

At its core, the idea behind why you need a wealth partner comes down to one distinction: managing investments versus managing wealth. An investment is one piece of your financial life; understanding how all those pieces fit together—liquidity, risk, goals, asset allocation—is the broader picture.

Choosing a mutual fund answers where to invest ₹10 lakh. A wider conversation also asks, how much of your total wealth should stay liquid? Are you overexposed to one asset class? How should the portfolio evolve as goals get closer?

Why Do You Need a Wealth Partner as Your Finances Grow?

India’s investment landscape has expanded dramatically, which is part of why the wealth-partner conversation matters more today. According to AMFI India, the mutual fund industry’s assets under management grew from ₹15.63 lakh crore in August 2016 to ₹87.08 lakh crore by August 2026, with folios crossing 28.35 crore.

Investors today can choose from mutual funds, PMS, AIFs, SIFs, bonds, FDs, REITs, and InvITs—more choice, but not necessarily easier decisions.

The real challenge isn’t accessing investments anymore; it’s deciding which ones actually deserve a place in your financial life.

From Products to a Portfolio

Consider someone holding ten different mutual funds. Each may look reasonable individually, but that alone doesn’t confirm the portfolio makes sense—there could be significant overlap, too much exposure to one segment, or insufficient liquidity.

This is exactly where the question of why you need a wealth partner starts to matter: someone who looks beyond individual products and asks what the portfolio as a whole is actually trying to achieve.

From Investments to Decisions

Markets rise and fall, interest rates shift, and personal circumstances change. The hard part usually isn’t knowing what happened—it’s deciding what to do about it.

Should you rebalance? Deploy a cash surplus now or gradually? Move money just because something else recently performed better?

A structured process around these decisions—rather than reacting to headlines—is one of the clearest reasons investors consider professional financial support as their financial life becomes more layered.

What Areas Does This Kind of Support Cover?

The exact scope varies, but typically spans portfolio planning, asset allocation, goal planning, portfolio reviews, identifying concentration or overlap, risk and liquidity management, and rebalancing.

As financial circumstances become more complex, family wealth and succession considerations may also become relevant. Tax, legal, and estate matters usually require separate specialist professionals—coordination across these areas can still be an important part of the broader financial picture.

6 Signs You Might Need a Wealth Partner

  1. Your financial situation has become hard to track on your own—multiple institutions, products, or accounts.
  2. Your investable surplus has grown significantly and now needs a clearer structure.
  3. You have both business and personal wealth that rarely get looked at together.
  4. You’re approaching a major goal—retirement, a child’s education, or a large purchase.
  5. You’re unsure whether your portfolio is genuinely diversified or just spread across many products.
  6. You find yourself making investment decisions reactively, based on headlines rather than a plan.

The real question isn’t “How much money do I have?”—it”‘s “How much financial complexity am I comfortable managing myself?”

You Don’t Need One Just Because You Have Money

This distinction matters.

If your finances are straightforward and you have the time, interest, and discipline to manage everything yourself, doing it independently can work perfectly well.

The need typically emerges from complexity, not net worth alone. Someone with modest wealth but several overlapping goals may value structured support more than someone financially sophisticated with a simple, well-understood portfolio.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705) and APMI-registered PMS Distributor (APRN-08140), we help Delhi NCR investors and families understand their mutual fund and PMS investment options and how these may fit within their broader financial goals and circumstances.

The appropriate approach depends on individual objectives, risk profile, investment horizon, and financial situation.

Connect with our team to discuss your investment requirements and available options.

FAQs

Q1. Is a wealth partner the same as a mutual fund distributor?

Not necessarily. A mutual fund distributor primarily facilitates and services mutual fund investments, while “wealth partner” is a broader term. The exact services and regulatory permissions depend on the specific entity and its registrations.

Q2. Is a wealth partner only for high-net-worth individuals?

No. The need depends more on the complexity of your finances than your net worth alone. Someone with modest wealth but several goals may value structured support just as much.

Q3. Does working with a wealth partner mean giving up control of my investments?

Not necessarily. The structure depends on the services involved. Investors can retain decision-making authority while using professional support for research, planning, and review.

Q4. Can a wealth partner guarantee better investment returns?

No. Returns can never be guaranteed. The value of professional support can lie in portfolio construction, risk management, goal alignment, and disciplined decision-making—not guaranteed return maximization.

Q5. When should I start thinking about this kind of support?

There’s no fixed number. A useful trigger is increasing complexity: more assets, more goals, or more decisions than you’re comfortable managing alone.

Final Word

Why do you need a wealth partner? Ultimately, it comes down to one shift: from making money work to making all of your money work together.

As your financial life across Delhi NCR grows—more assets, more goals, more decisions—the value isn’t necessarily in finding the next best investment alone, but in keeping every piece of your financial picture aligned with what you actually want it to achieve.


Disclaimer: This article is intended for educational and informational purposes only and should not be construed as investment advice, a recommendation, or a solicitation to invest in any particular financial product. Investment decisions should be based on individual financial circumstances, objectives, risk profile, and investment horizon. Past performance is not indicative of future results. Please independently evaluate products and, where appropriate, seek advice from suitably qualified and regulated professionals.

SIP Investments in India Hit a Record High: 5 Smart Lessons Every Delhi NCR Investor Should Take Away

SIP investments in India hit a record high with ₹32,297 crore monthly contribution in August 2026
India’s monthly SIP contribution reached a record ₹32,297 crore in August 2026, according to AMFI data.

SIP investments in India hit a record high of ₹32,297 crore in August 2026—the highest monthly SIP contribution ever recorded by AMFI. Ten years earlier, in August 2016, that number was just ₹3,497 crore. That’s a more than nine-fold jump in a decade. But behind this headline number is a much more interesting story for Delhi NCR investors: how Indians are quietly changing the way they think about money and what the cost of waiting to invest actually looks like.

Just How Big Is India’s SIP Boom?

The scale becomes clear when you place the numbers side by side. Monthly SIP contributions rose from ₹3,497 crore in August 2016 to ₹32,297 crore in August 2026. Outstanding SIP accounts reached 10.75 crore, with 10.02 crore actually contributing that month, and SIP assets under management touched ₹18.62 lakh crore. AMFI also recorded 66.40 lakh new SIP registrations in August alone, against 53.82 lakh SIPs that were discontinued or completed—a net addition of roughly 12.58 lakh accounts in just one month. SIP investments in India hitting a record high comes as part of a much larger increase in SIP participation over the past decade. 

The Bigger Mutual Fund Story Behind the Numbers

SIPs are just one part of a much larger transformation. India’s overall mutual fund industry AUM stood at ₹87.08 lakh crore at the end of August 2026, up roughly six-fold from ₹15.63 lakh crore in August 2016. Mutual fund folios have grown from 10.86 crore in August 2021 to 28.35 crore in August 2026—more than a two-and-a-half-fold increase in just five years, with roughly 21.62 crore of those folios in equity, hybrid, and solution-oriented schemes. For Delhi NCR households, this points to something bigger than a passing trend: organized, systematic investing is becoming the norm rather than the exception.

Why Has the SIP Become So Popular?

The appeal is part mathematics, part psychology. Ask someone to invest ₹12 lakh in one go, and it immediately raises hard questions—where will the money come from, is the market at the right level, and what if it falls right after? Ask instead, “Can you invest ₹10,000 a month?” and the decision suddenly feels manageable. According to AMFI, a SIP, is simply a method of investing a fixed amount periodically in a mutual fund scheme, helping investors stay disciplined without trying to time the market. It’s worth remembering: a SIP is a method of investing, not an investment product in itself—the underlying mutual fund is what actually carries the risk and return.

The Real FOMO Isn’t About Missing the Next Rally

The common fear is “the market went up; I should have invested earlier.” But that’s not the FOMO that matters most. Consider two people who both could have started investing ₹10,000 a month five years ago—one did, one kept waiting for the “right time.” Five years later, the person who started has something the other person can never buy back: five years of investment time. You can increase your SIP amount later, change your strategy later, or even recover from a bad investment choice later—but you cannot recover lost time.

What Does Starting Early Actually Do?

Here’s a simple illustration. Investing ₹10,000 every month for 20 years means a total contribution of ₹24 lakh, which at an illustrative 12% annualized return could grow to approximately ₹99 lakh. Wait five years, and investing the same ₹10,000 monthly for only 15 years brings the total contribution down to ₹18 lakh, with an illustrative corpus of around ₹50 lakh. (These are hypothetical illustrations, not guaranteed returns—actual outcomes depend on market performance, fund selection, costs, and taxes.) The investor who waited contributed just ₹6 lakh less, yet the eventual illustrative gap is far larger—because those extra five years of compounding matter more than the headline contribution amount.

The Other Side of the SIP Story

Record SIP contributions shouldn’t push anyone into investing blindly. When your colleague has an SIP, your friend has three mutual funds, and headlines talk about ₹32,297 crore flowing in every month, it’s easy to feel like you’re “behind”—but that’s FOMO, not a strategy. The fact that millions of Delhi NCR residents (and Indians nationwide) are investing through SIPs doesn’t tell you what to invest in, how much risk to take, or which mutual fund category actually suits your goal. It’s also worth remembering that an SIP doesn’t remove market risk—if you’re invested in equity mutual funds, your value can still fall when markets fall. A SIP simply means you keep investing on schedule; it doesn’t eliminate volatility.

3 Questions to Ask Before Starting a SIP

Before jumping in because “SIP investments in India hit a record high” made headlines, ask yourself:

  1. What am I actually investing for? Retirement, a child’s education, or a future purchase can each call for a different approach.
  2. How long can I realistically stay invested? Your time horizon should match the volatility you’re willing to sit through.
  3. How much can I invest without disrupting my monthly budget? A sustainable SIP beats an aggressive one you can’t maintain past a few months.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, AMFI-registered Mutual Fund Distributor (ARN-272705), we see the SIP boom as a genuine shift in household financial behavior—but record flows should never replace a plan built around your own goals and risk profile. If you have a long-term goal and keep postponing simply because the timing never feels perfect, it’s worth understanding what that delay is actually costing you in lost compounding time. Connect with our team to understand which mutual fund categories might suit your goals. For the latest official SIP and mutual fund industry data, refer to AMFI India’s official reports.

FAQs

Q1. Are SIP investments in India really at a record high?

Yes—AMFI reported ₹32,297 crore in monthly SIP contributions in August 2026, the highest in its published series.

Q2. Does a record SIP contribution mean the stock market will rise? No. SIP flows reflect investor participation, not a reliable signal of future market direction.

Q3. Is it too late to start a SIP now that contributions are at record highs? 

There’s no universal answer—it depends on your goals, horizon, and risk tolerance. But waiting indefinitely for a “perfect” entry point can mean losing valuable compounding time.

Q4. Does starting a SIP early guarantee higher returns? 

No. Starting earlier gives your investment more time to potentially compound, but actual returns still depend on market performance and the underlying fund.

Final Word

SIP investments in India hitting a record high isn’t a signal to rush in—it’s a signal that Indian investors, including many across Delhi NCR, are increasingly treating investing as a recurring habit rather than a one-time event. You don’t need to feel FOMO because someone else started before you. But if investing genuinely fits your goals, understand what indefinite postponement is costing you. The market will offer many entry points over your lifetime—time is the one entry point you can’t revisit.

Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. This article is for educational and informational purposes only and should not be construed as investment advice or a guarantee of returns. The illustrations used are hypothetical. Please assess your own financial circumstances and, where appropriate, consult a qualified financial professional before investing. Data source: Association of Mutual Funds in India (AMFI), August 2026.
Why Is My Mutual Fund Underperforming? 5 Real Reasons Every Delhi NCR Investor Should Understand

Why is my mutual fund underperforming – 5 real reasons explained
Should you invest in 10 mutual funds portfolio diversification
More mutual funds do not always mean better diversification.

Why is my mutual fund underperforming? It’s the question that hits the moment you spot a friend’s fund or a WhatsApp forward showing higher returns than your own. Across Delhi NCR, this is one of the most common triggers for investors to impulsively switch funds, often without actually understanding what’s behind the gap. Before you make that call, it helps to know that a fund can deliver positive returns and still technically be “underperforming”—and that alone isn’t always a red flag.

What Does “Underperforming” Actually Mean?

Underperformance simply means a fund has delivered lower returns than an appropriate reference point—its benchmark, its category, or a comparable peer—over a specific period. If your fund returned 10% while its benchmark returned 14%, that’s a 4-point gap. But looking at just one period can be misleading, since different investment strategies perform differently across market cycles. A fund trailing today may lead tomorrow once conditions shift—which is exactly why understanding why my mutual fund is underperforming matters more than reacting to a single number.

5 Real Reasons a Mutual Fund Can Underperform

1. Its Investment Style Is Temporarily Out of Favor

A value-oriented fund can lag when growth stocks are leading the market, and a defensive portfolio may not fully participate in a sharp rally. This doesn’t mean the fund manager has erred—it may simply be positioned differently from what the market is currently rewarding.

2. It’s Going Through a Difficult Market Cycle

If the sectors a fund holds significant exposure to fall out of favor, its returns can trail benchmarks and peers for a stretch—particularly relevant for actively managed funds whose positioning differs meaningfully from an index.

3. The Fund Manager’s Calls Haven’t Worked Out

Active management means making decisions that differ from the benchmark. Some work, some don’t. If a fund manager’s decisions consistently fail to add value over a meaningful period, that’s when persistent underperformance deserves closer investigation.

4. Higher Costs Are Eating Into Returns

Expenses reduce what actually reaches investors. Two funds with near-identical portfolios can produce different investor returns purely due to differences in expense ratios—which is exactly why performance should be judged after costs, not just on paper.

5. The Fund Itself Has Changed

Fund managers change, investment processes evolve, and portfolios can end up looking quite different from what you originally signed up for. If the reason you picked the fund no longer holds true, that’s worth attention—even before returns reflect the shift.

Stop Comparing Every Fund to the Nifty

One of the biggest mistakes behind “why is my mutual fund underperforming” panic is comparing every scheme directly to the Nifty 50. A small-cap fund, a debt fund, and a large-cap fund all have completely different mandates, so their performance should be judged against the appropriate benchmark and category—not a single headline index. The real question isn’t “did my fund beat the market?” It’s “Did my fund perform reasonably well relative to what it’s actually designed to compete with?”

How Long Should You Wait Before Judging a Fund?

There’s no universal timeframe that fits every fund. Short-term performance is heavily influenced by market conditions, so a few weak months — or even a year — may not say much about a long-term strategy’s quality. A more meaningful review looks at performance across different market cycles and an appropriate investment horizon. According to AMFI India’s investor education resources, evaluating a fund against its category and benchmark over a longer, relevant period gives a far more accurate picture than a single year’s snapshot.

Should You Switch Your Mutual Fund?

Not simply because another fund performed better recently. Switching purely on recent performance often traps investors in a costly cycle—selling a fund after weakness and buying another right after it has already run up. Instead, first understand why your fund underperformed and whether that reason is likely to persist. If its strategy, management, and risk profile remain appropriate, temporary underperformance may not require any action at all. A review becomes genuinely worthwhile when underperformance is persistent, hard to explain, or accompanied by real changes in fund management or strategy.

GCIC Finserve’s Take for Delhi NCR Investors

At GCIC Finserve, when Delhi NCR clients ask, “Why is my mutual fund underperforming?” we don’t jump straight to a switch—we look at the fund’s benchmark-relative performance, category consistency, portfolio positioning, and whether it’s still serving its original purpose in the portfolio. As an AMFI-registered Mutual Fund Distributor (ARN-272705), our team helps you separate a fund that genuinely needs replacing from one that’s simply going through a normal market cycle.

FAQs

Q1. Why is my mutual fund underperforming the market? It could be due to its investment style being out of favor, sector exposure, costs, fund manager decisions, or changes in the fund’s strategy—not necessarily poor management.

Q2. Should I sell a mutual fund after one year of underperformance? Not necessarily. One year can reflect normal market cycles rather than a genuine problem—compare it against its appropriate benchmark and category first.

Q3. Should I switch to whichever fund has the highest recent returns? Not automatically. Chasing recent performance often means buying high after a fund has already run up—evaluate based on strategy and suitability instead.

Q4. What should I check before replacing an underperforming fund? Its benchmark and category performance, consistency across periods, portfolio positioning, costs, and whether it still fits your original goal and risk profile.

Final Word

The next time you catch yourself asking, “Why is my mutual fund underperforming?” resist the urge to switch immediately. Understand the reason first—market cycle, style, costs, or a genuine change in the fund—and only then decide if action is actually needed. A fund doesn’t need to top the charts every year to remain the right investment for you.


Disclaimer: This article is intended solely for educational and informational purposes and should not be construed as investment advice. Mutual fund investments are subject to market risks. Please review scheme-related documents and consult a registered advisor before investing.