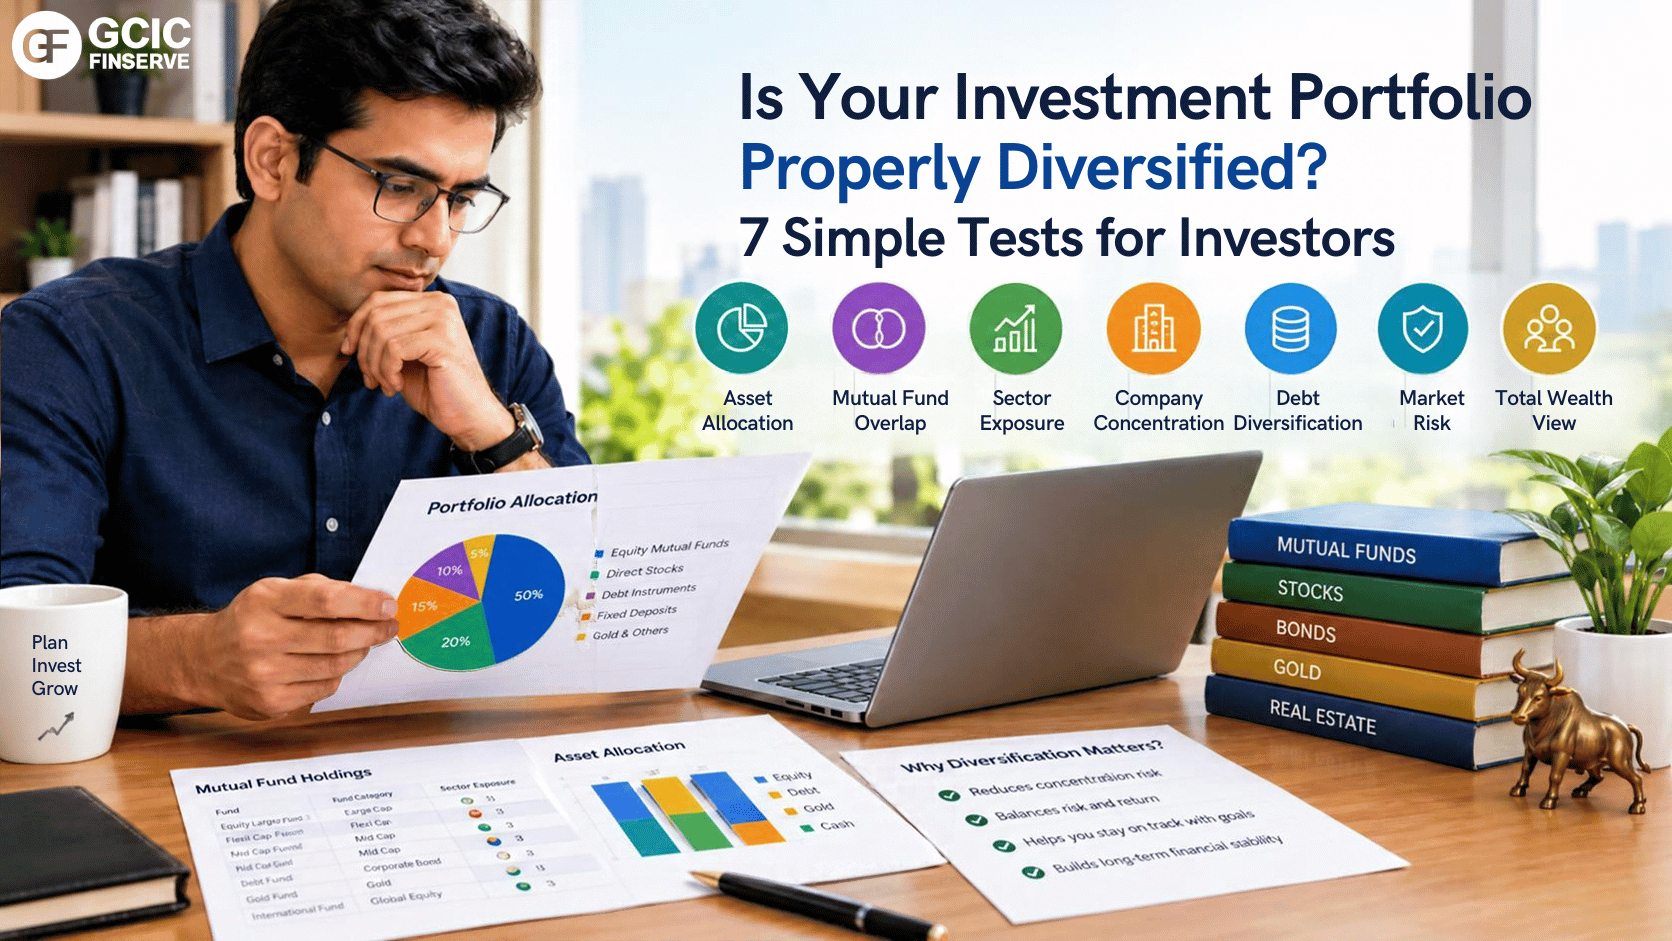
What is asset allocation, and why do experienced investors consider it an important part of financial planning? Investing is often presented as a question of what to buy: which mutual fund, which stock, gold or bonds? But a bigger question comes first: how should your overall money be divided?
Asset allocation is the process of deciding how much to invest across asset classes such as equity, debt, gold and cash. A suitable allocation considers your financial goals, investment horizon, liquidity needs and ability to handle risk. It does not rely on predicting which market or asset class will perform best next.
For Delhi NCR investors managing savings, property, business income and long-term family goals, understanding asset allocation can help bring greater structure to financial decisions.
1. What Exactly Is Asset Allocation?
Imagine you have ₹50 lakh to invest. You could put it all into equity, keep most of it in fixed deposits, buy gold or divide it across different asset classes.
That division is your asset allocation.
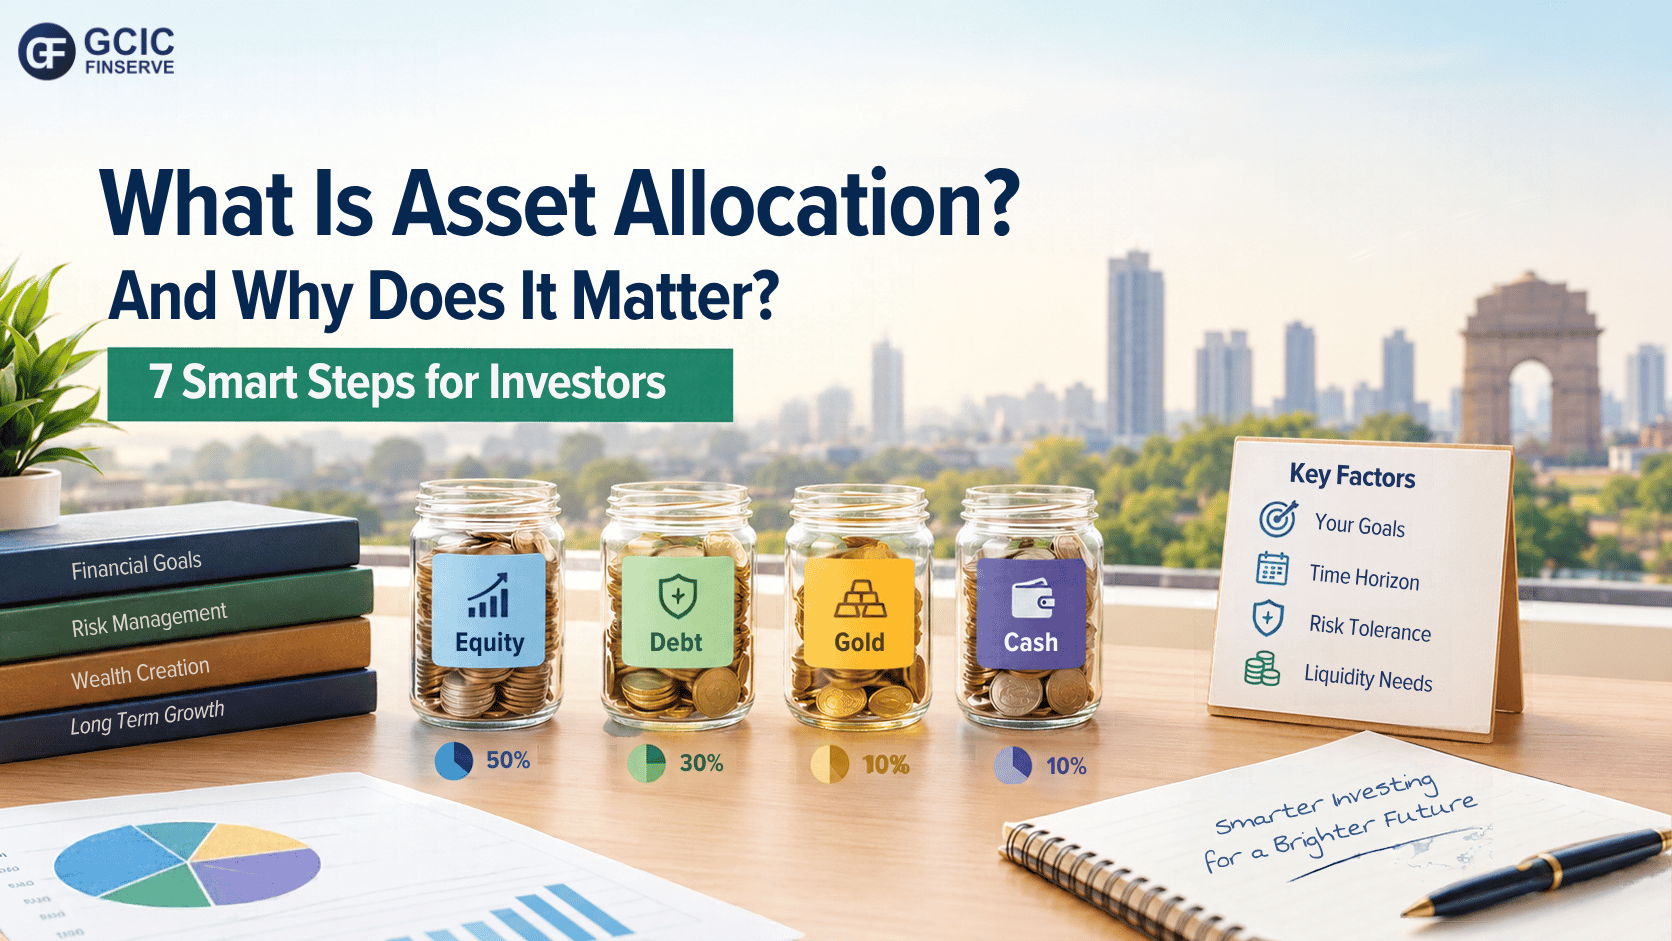
For illustration, ₹50 lakh could be divided as follows:
- Equity: ₹25 lakh (50%)
- Debt: ₹15 lakh (30%)
- Gold: ₹5 lakh (10%)
- Cash or liquid investments: ₹5 lakh (10%)
This is an illustrative example, not a recommended allocation for every investor. The appropriate mix depends on your individual circumstances, financial commitments and investment horizon.
2. Why Does Asset Allocation Matter?
Different investments carry different risks and behave differently under changing economic conditions.
Equity offers long-term growth potential but can experience significant short-term fluctuations. Debt investments may provide income or relative stability, although their risks vary by instrument. Gold may behave differently from equity and debt, potentially adding diversification. Cash and liquid investments can help meet immediate financial needs.
Combining different asset classes can reduce dependence on a single type of investment. However, diversification does not guarantee profits or eliminate losses.
Consider someone planning to use ₹30 lakh for a property purchase in two years. Even if that person chooses well-performing equity funds, investing money needed so soon in volatile assets could create a mismatch between the investment and the goal.
This is why understanding what is asset allocation matters before selecting individual mutual funds or other investment products.
3. The 3 Factors That Shape Your Allocation
There is no universal allocation formula based only on age or income. Three important factors help determine an appropriate approach.
Investment horizon: Money needed within a year has a different purpose from money intended for retirement 15 years away. Each financial goal may require its own allocation.
Risk tolerance and risk capacity: Risk tolerance refers to your emotional comfort with market fluctuations. Risk capacity refers to your financial ability to absorb losses without jeopardising important goals. Both matter when deciding how much risk to take.
Financial goals: Retirement, children’s education, a property purchase and business expansion have different timelines and cash-flow requirements. Your investments should reflect those differences.
Your circumstances can also change. A new child, a business expansion, an inheritance or approaching retirement may require a review of your allocation.
4. The Major Asset Classes
Equity
Equity represents ownership in businesses, either directly through stocks or indirectly through equity mutual funds. It offers growth potential but can fluctuate considerably. It is generally more suitable for goals with a sufficiently long horizon and an ability to withstand market volatility.
Debt
Debt investments involve lending money to a government, company or other borrower. Examples include fixed deposits, government securities, corporate bonds, treasury bills and debt mutual funds.
These instruments can serve different purposes, including income, liquidity and portfolio stability. Their credit, interest-rate and liquidity risks vary, so they should not all be treated as equally safe.
Gold
Gold can be held physically or through eligible financial products such as Gold ETFs and gold mutual funds. It does not generate interest or business profits. Some investors include it as a diversifying asset rather than relying on it as their primary source of long-term growth.
Cash and Liquid Investments
Cash and suitable liquid investments can help cover emergency expenses and foreseeable short-term needs. Accessibility and capital preservation are often more important for this portion of a portfolio than pursuing higher returns.
Real Estate
Real estate is a significant part of wealth for many Delhi NCR families. Property can serve residential or investment purposes, but it may involve substantial capital, transaction costs and limited liquidity.
If a large proportion of your wealth is already tied up in property, that exposure should be considered when reviewing your overall financial position.
You do not necessarily need every asset class. Adding investments simply to make a portfolio appear diversified can increase complexity without necessarily improving it.
5. A Simple Example: Two Investors, ₹1 Crore Each
Consider two hypothetical investors with ₹1 crore each.
Investor A: A 35-year-old with a stable income and a financial goal at least 15 years away may be able to consider a meaningful equity allocation, provided their financial capacity and risk tolerance support it.
Investor B: A 60-year-old expecting to use a substantial portion of their wealth for living expenses over the next few years may need to give greater attention to liquidity and short-term capital fluctuations.
Both investors have the same amount of money, but their financial needs differ.
The lesson is not that a particular age requires a fixed percentage in equity or debt. The purpose of the money, the time available and the investor’s ability to absorb losses should guide the decision.
6. Rebalancing and Common Asset Allocation Mistakes
What Is Rebalancing?
Suppose a hypothetical portfolio begins with 60% equity, 30% debt and 10% gold. After a period of strong equity performance, its allocation changes to 72% equity, 21% debt and 7% gold.
The portfolio now has greater equity exposure than originally intended.
Rebalancing means bringing the portfolio closer to its intended allocation. This may involve directing new investments towards underrepresented assets or selling some holdings, after considering taxes, costs and individual circumstances.
Rebalancing is not a method of predicting the market. It is a way to maintain a portfolio structure that continues to fit your objectives.
Strategic asset allocation establishes a longer-term target. Tactical asset allocation involves temporary changes based on market views and can be difficult to execute consistently.
Common Mistakes to Avoid
- Chasing recent performance: Buying an asset simply because it has recently delivered strong returns.
- Taking excessive risk: Choosing an allocation that becomes difficult to maintain during market declines.
- Ignoring inflation: Overlooking how rising living costs can affect long-term financial goals.
- Overlooking existing wealth: Ignoring property, business ownership and other assets when assessing total exposure.
- Never reviewing the portfolio: Failing to reassess investments after significant financial or family changes.
7. 7 Steps to Build an Asset Allocation
Step 1: List your financial goals. Identify what you are investing for, such as retirement, education, property or business needs.
Step 2: Assign a time horizon. Estimate when you will need the money for each goal.
Step 3: Assess liquidity requirements. Keep suitable provisions for emergencies and foreseeable expenses.
Step 4: Understand your risk capacity. Consider your income stability, financial obligations, existing assets and ability to absorb losses.
Step 5: Decide your broad asset mix. Evaluate the role of equity, debt, gold, cash and any other relevant assets in your overall financial position.
Step 6: Select suitable investments. Only after establishing the broad allocation should you compare individual products, costs, risks and investment features.
Step 7: Review and rebalance periodically. Revisit your allocation at appropriate intervals and after major life events or changes in financial goals.
These steps provide a framework for organising financial decisions. They do not replace an individual assessment of suitability.
GCIC Finserve’s Perspective for Delhi NCR Investors
Investors in South Delhi, Gurugram, Noida and other parts of Delhi NCR may have different financial priorities, from retirement planning and children’s education to property purchases and business expansion.
At GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705, subject to verification of current registration details), investors can explore mutual fund categories and understand how different investment options relate to their financial goals and time horizons.
To learn more about mutual fund categories and investor education, visit AMFI India.
Frequently Asked Questions
Q1. What is asset allocation in simple terms?
Asset allocation means dividing your investments among different asset classes, such as equity, debt, gold and cash, according to your goals, time horizon and risk profile.
Q2. Is asset allocation the same as diversification?
No. Asset allocation determines how money is divided among broad asset classes. Diversification involves spreading investments across different holdings or exposures to reduce concentration risk. Neither guarantees protection against losses.
Q3. What is the best asset allocation?
There is no single best allocation for everyone. It depends on financial goals, investment horizon, risk tolerance, risk capacity, liquidity requirements, liabilities and existing assets.
Q4. Should young investors invest mostly in equity?
Age alone should not determine an allocation. A younger investor may have a longer investment horizon, but income stability, financial responsibilities and the ability to tolerate losses also matter.
Q5. What is portfolio rebalancing?
Portfolio rebalancing means adjusting investments when their actual proportions move away from the intended allocation. It can help keep the portfolio aligned with its objectives and risk profile.
Q6. How often should asset allocation be reviewed?
The review frequency depends on individual circumstances and the investment strategy. Periodic reviews and reassessments after major life events can help determine whether the allocation remains appropriate.
Final Word
So, what is asset allocation? It is the process of deciding how your overall wealth should be distributed before choosing individual investments.
Instead of trying to predict the next winning asset class, the objective is to build a portfolio that reflects your financial goals, investment horizon, liquidity needs and ability to handle risk.
A thoughtful allocation can help bring discipline to investment decisions, but it cannot guarantee returns or prevent losses. Reviewing your overall financial position regularly is an important part of keeping your investment approach aligned with changing needs.
Disclaimer: This article is intended solely for general educational and informational purposes. It does not constitute investment, financial, tax or legal advice, or a recommendation to buy, sell or hold any security or investment product. The examples and asset allocations discussed are illustrative only and may not be suitable for every investor. Investment decisions should take account of individual financial goals, investment horizon, liquidity requirements, risk profile, liabilities and existing assets. Market-linked investments are subject to market risks, and diversification does not guarantee returns or eliminate the risk of loss. Please read the relevant scheme documents carefully before investing and consult an appropriately qualified financial professional where necessary.