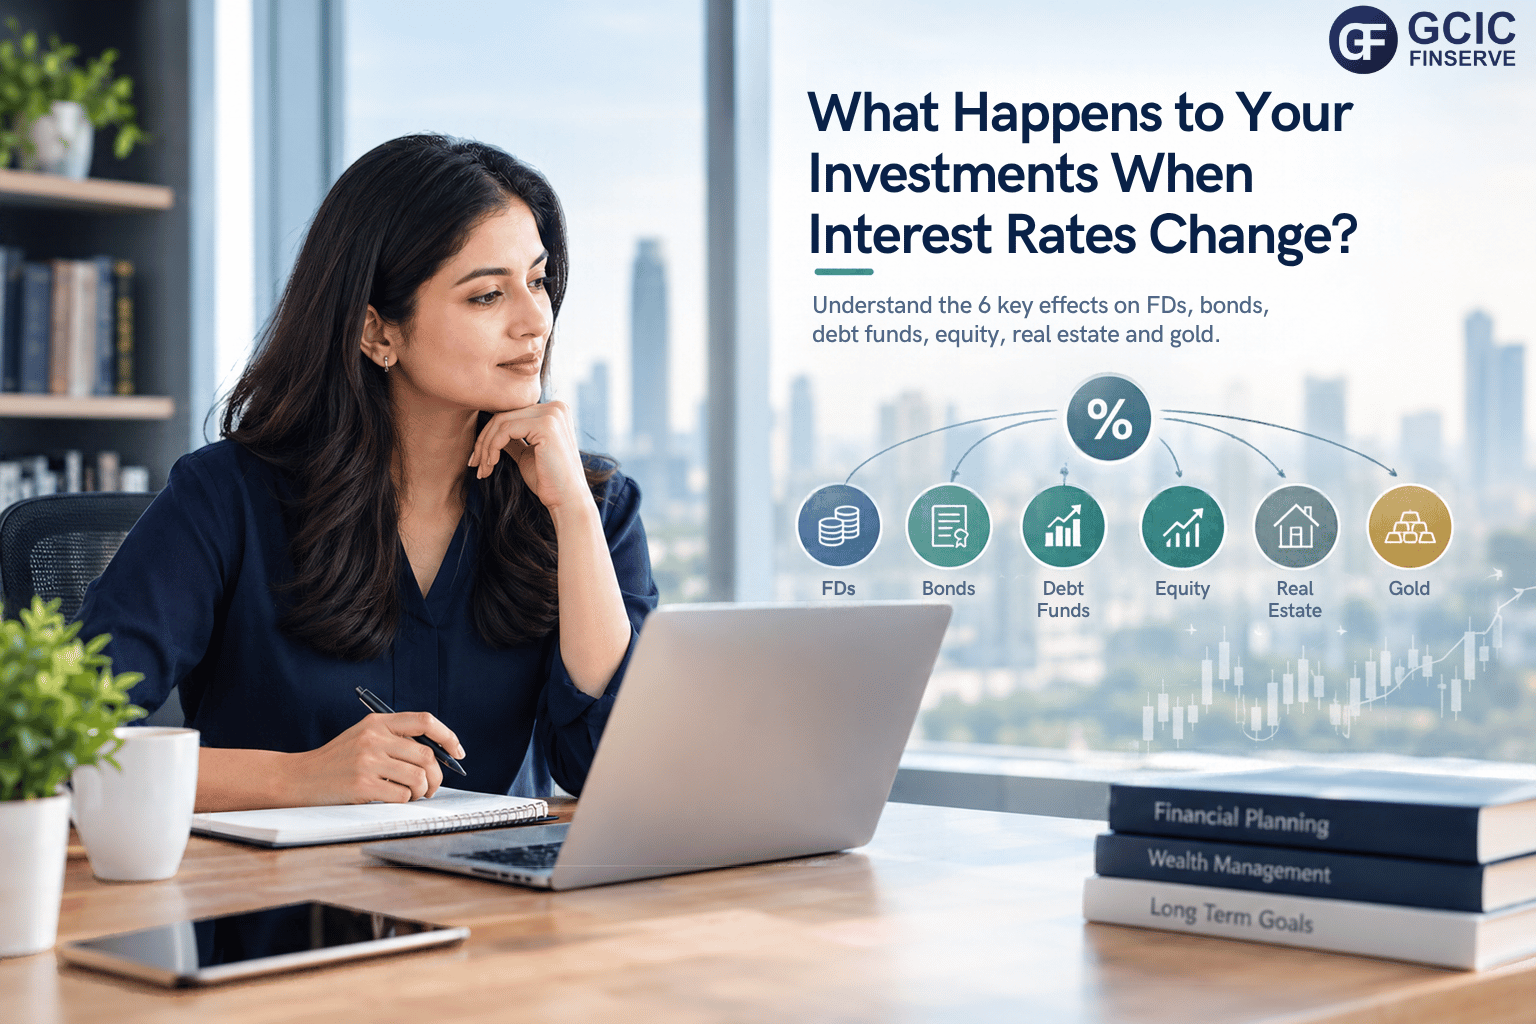

What happens to your investments when interest rates change? Interest rates affect much more than the returns on your fixed deposit (FD). When the Reserve Bank of India (RBI) changes its policy rates, or market interest rates move for other reasons, the impact can spread across the financial system. Bond prices may change, debt mutual fund NAVs can fluctuate, borrowing costs may rise or fall, and investments such as equity, real estate, and gold can also be affected.
For investors in Delhi NCR, understanding these changes can help make financial decisions more informed. However, the impact depends on the type of investment you hold, your investment horizon, market conditions, and your financial goals.
In this guide, we explain six key effects of interest rate changes on common investment options and what investors should understand before making decisions.
What Do We Mean by Interest Rates?
There is no single interest rate that controls every investment. The RBI’s policy rates influence financial conditions and the broader cost of money, while banks and financial institutions respond according to their funding costs, liquidity, credit demand, and expectations.
Market interest rates are also influenced by inflation, economic growth, government borrowing, and global financial conditions.
For example, when market interest rates rise, new fixed-income investments may offer higher yields. However, existing fixed-rate investments do not necessarily change their contracted returns.
Understanding these differences is an important first step in learning what happens to your investments when interest rates change.
Why Do Interest Rates Matter to Investors?
Interest rates influence the relative attractiveness of different investments, the cost of borrowing and the value investors place on future income.
Consider a bond paying an annual coupon of 7%. If newly issued bonds with similar risk begin offering 8%, the older bond may become less attractive. Its market price would generally need to fall to make its yield competitive with the newer bonds.
This explains a fundamental relationship in fixed-income investing:
When market yields rise, existing fixed-rate bond prices generally fall. When market yields fall, existing fixed-rate bond prices generally rise.
The extent of the price movement depends on factors such as the bond’s maturity, coupon, and duration.
Interest rate changes can affect different investments in different ways. Let’s examine six important effects.
Effect 1: Fixed Deposits (FDs)
Fixed deposits are among the easiest investments to understand when discussing interest rates.
Suppose you book a three-year FD at an annual interest rate of 7%. Six months later, banks begin offering 7.5% on comparable new deposits.
Your existing fixed-rate FD generally continues at its contracted rate until maturity, subject to the deposit terms. You do not automatically start earning the newer rate.
When interest rates rise, new depositors may benefit from higher offered rates, while existing depositors continue earning the rate agreed upon earlier.
When rates fall, investors who previously locked in a higher fixed rate may continue earning that rate until maturity.
Should You Lock in FD Rates?
The decision depends on your investment horizon, liquidity needs, the available rates, and your expectations about future rates.
A fixed-rate FD can provide predictable contractual interest, but premature withdrawal may involve penalties or reduced interest. Reinvestment rates at maturity may also be different from the original rate.
Before choosing an FD, compare its tenure, interest payout options, premature withdrawal conditions, and applicable taxation.
Effect 2: Bonds
Bonds are particularly sensitive to changes in market interest rates.
Suppose you own a bond with a face value of ₹1,000 and an annual coupon rate of 8%. It pays ₹80 in annual coupon interest.
If newly issued bonds with similar risk begin offering 9%, your existing bond becomes less attractive at its original price. Its market price may fall below ₹1,000 so that a new buyer can obtain a more competitive yield.
If comparable market yields subsequently fall to 7%, your 8% coupon bond may become more attractive, potentially increasing its market price.
Do Bond Investors Lose Money When Rates Rise?
Not necessarily. The outcome depends on the bond’s price, the investor’s holding period, and whether the issuer meets its obligations.
If you hold a bond to maturity, its contractual coupon payments and principal repayment remain relevant, subject to the issuer’s ability to pay and the bond’s terms.
However, if you sell before maturity, the prevailing market price can result in a gain or loss.
Bonds also carry other risks, including credit risk, liquidity risk and reinvestment risk. A higher coupon or yield does not automatically mean a bond is suitable for every investor.
Effect 3: Debt Mutual Funds and Duration
Debt mutual funds invest in fixed-income securities such as government securities, corporate bonds and money market instruments, depending on the scheme’s mandate.
Their net asset values (NAVs) can respond to changes in market yields because the prices of the securities they hold may change.
When market yields rise, existing bond prices generally fall, potentially reducing a debt fund’s NAV. When market yields fall, bond prices may rise, potentially supporting the NAV.
However, the actual impact depends on the fund’s holdings, credit quality, duration, expenses, and market conditions.
What Is Duration in Debt Mutual Funds?
Duration is a measure used to understand a fixed-income investment’s sensitivity to interest rate changes. It is not simply the same as the investment’s maturity.
Generally, a fund with higher duration is more sensitive to changes in market yields than a comparable fund with lower duration.
For example, if two funds have similar credit quality but different duration profiles, the longer-duration fund will generally experience a larger price impact from the same yield movement.
This is why understanding a fund’s category and portfolio characteristics matters more than simply knowing that it invests in debt.
What Is Reinvestment Risk?
When interest rates fall, income from maturing bonds may need to be reinvested at lower yields. This is known as reinvestment risk.
Investors evaluating debt mutual funds should therefore consider their investment horizon, liquidity needs, risk tolerance, and the scheme’s investment objective rather than making decisions based only on forecasts of interest rates.
Explore relevant information through the GCIC Finserve website.
Effect 4: Equity
There is no universal rule that rising interest rates always cause stock markets to fall.
Interest rate changes can influence equity valuations and corporate profitability in several ways.
First, higher borrowing costs can increase expenses for companies with substantial debt. This may affect their profitability, investment plans and ability to expand.
Second, higher interest rates can make fixed-income investments relatively more attractive compared with riskier assets. This can influence how investors value equities.
Third, interest rates affect the discount rate used to estimate the present value of future corporate earnings. Companies whose valuations depend heavily on profits expected far into the future can be particularly sensitive to changes in these assumptions.
However, equity markets respond to several factors simultaneously, including earnings growth, economic activity, valuations, liquidity, inflation, and investor expectations.
For example, rising interest rates during a period of strong economic growth may have different implications from rising rates driven by persistent inflation.
Equity investors should therefore avoid making decisions based on interest rates alone.
Effect 5: Real Estate
Interest rates can influence real estate through home loans, commercial financing, and property demand.
For homebuyers in Delhi NCR, higher loan interest rates can increase the EMI on a floating-rate loan or extend its repayment period, depending on the lender’s terms and loan structure. Higher borrowing costs may also reduce the loan amount some buyers can afford.
Lower borrowing costs may improve affordability for some buyers, but they do not guarantee that property prices will rise.
Commercial real estate is also affected by financing costs, rental income expectations, and the returns investors require.
Property prices depend on multiple factors, including location, infrastructure, supply, rental yields, employment opportunities, and broader economic conditions.
Before purchasing property, consider the total cost, loan affordability, liquidity requirements, and intended holding period rather than relying solely on the direction of interest rates.
Effect 6: Gold
Gold behaves differently from investments that pay contractual interest.
Because gold does not pay interest, higher interest rates or rising real yields can increase the opportunity cost of holding it compared with interest-bearing assets.
This relationship can influence gold prices, but it is not consistent in every market environment.
Gold prices can also be affected by inflation expectations, global interest rates, movements in the US dollar, central bank demand, geopolitical uncertainty, and currency fluctuations.
For Indian investors, movements in international gold prices and the rupee can both influence domestic gold prices.
Therefore, gold does not always move in the opposite direction to interest rates.
Investors considering gold should assess its role in their overall portfolio, diversification needs, costs, and risk tolerance rather than assuming it will perform in a particular way when rates change.
Policy Rates vs Market Rates: Why the Difference Matters
The RBI’s policy decisions influence monetary and financial conditions, but the interest rate on a particular bond, FD or loan does not automatically move by the same amount.
Market rates also reflect inflation expectations, government borrowing, credit risk, liquidity and expectations about future monetary policy.
This is why bond yields may move before an RBI announcement or change even when the policy rate remains unchanged.
For investors, it is important to distinguish between:
- Policy rates: Rates set by the RBI as part of its monetary policy framework.
- Market yields: Returns available on securities at prevailing market prices.
- Deposit rates: Rates offered by banks and other deposit-taking institutions under their respective terms.
- Loan rates: Rates charged by lenders according to the loan agreement, benchmark and applicable conditions.
Understanding these differences helps explain why the effects of interest rate changes are not identical across investments.
For official monetary policy information, visit the Reserve Bank of India.
Should You Change Your Investments When Interest Rates Change?
Not necessarily. Changing investments every time rates move can result in unnecessary transactions, costs, taxes and decisions based on short-term forecasts.
Instead, consider these questions before making a decision:
- What is the purpose of the investment? Money intended for a near-term expense may require a different approach from money invested for a long-term goal.
- When will you need the money? Your investment horizon can influence how much price fluctuation you can reasonably tolerate.
- How sensitive is the investment to interest rates? Consider the duration of debt investments, the terms of your FD and the borrowing exposure of companies or property investments.
- Do you need liquidity? An investment that is difficult or costly to exit may not suit money you need at short notice.
- Does your portfolio still match your goals and risk tolerance? Review the overall allocation instead of focusing on a single market indicator.
Consider two investors. One holds short-term FDs and short-duration debt investments. Over time, that investor may be able to reinvest maturing money at higher rates if available.
Another investor holds long-duration bonds or debt funds. That investor may experience a more immediate impact on market value when yields rise.
Neither situation is automatically better or worse. The outcome depends on the investor’s needs, the investment’s characteristics and market conditions.
The objective is to understand the risks and make informed decisions, not to predict every interest rate movement.
GCIC Finserve’s Perspective for Delhi NCR Investors
Interest rate movements can affect different investments in different ways. Understanding these effects can help investors evaluate their portfolios in the context of their financial goals, investment horizon, liquidity needs and risk tolerance.
GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705), shares educational information to help investors understand mutual funds and related investment concepts.
For general information about mutual funds and financial services, visit GCIC Finserve.
For official information about monetary policy, visit the Reserve Bank of India. For investor education and securities-market information, refer to SEBI and the Association of Mutual Funds in India (AMFI).
Frequently Asked Questions
1. What happens to bonds when interest rates rise?
Existing fixed-rate bond prices generally fall when comparable market yields rise. The extent of the impact depends on factors such as duration, maturity, coupon and credit quality.
2. Do FD rates change when the RBI changes interest rates?
Banks may revise rates on new deposits in response to market conditions, funding costs and other factors. An existing fixed-rate FD generally continues at its contracted rate until maturity, subject to its terms.
3. What happens to debt mutual funds when interest rates rise?
Rising market yields generally reduce the prices of existing fixed-income securities, which can lower a debt mutual fund’s NAV. Funds with higher duration are generally more sensitive to yield changes, all else being equal.
4. Do falling interest rates always mean stock markets will rise?
No. Equity markets respond to several factors, including corporate earnings, economic growth, valuations, inflation, liquidity and investor expectations. Interest rates are only one influence.
5. Is a higher interest rate always better for investors?
Not necessarily. Higher rates may benefit investors placing new money into certain fixed-income products, but they can also increase borrowing costs and reduce the market value of existing fixed-rate bonds. The impact depends on the investor’s circumstances and investments.
6. Why do bond prices and yields move in opposite directions?
A bond’s contractual coupon generally remains fixed. When its market price falls, a new buyer pays less for the same contractual cash flows, increasing the yield available at that price. When the price rises, the yield generally falls, all else being equal.
Final Word
What happens to your investments when interest rates change depends on what you own and why you own it.
Fixed-rate FDs generally retain their contracted rate, bond prices tend to move inversely to market yields, debt mutual funds respond according to their holdings and duration, and equity, real estate and gold are influenced by a wider range of factors.
You do not need to predict every rate movement to make informed investment decisions. Understanding how interest rates affect your existing investments can help you evaluate risks, review your financial goals, and avoid reacting unnecessarily to short-term market changes.
Disclaimer: This article is intended solely for general educational and informational purposes. It should not be construed as investment, financial, tax, or legal advice, or as a recommendation to buy, sell, or hold any security or investment product. The impact of interest rate movements varies according to market conditions, investment characteristics, and individual circumstances. Market-linked investments are subject to market risks, and past performance is not indicative of future results. Investors should consider their financial goals, investment horizon, liquidity requirements, and risk tolerance before making investment decisions and seek professional guidance where appropriate.
Mutual fund investments are subject to market risks; read all the related documents carefully before investing.