Why Do You Need a Wealth Partner? 6 Signs Every Growing Delhi NCR Investor Should Watch For

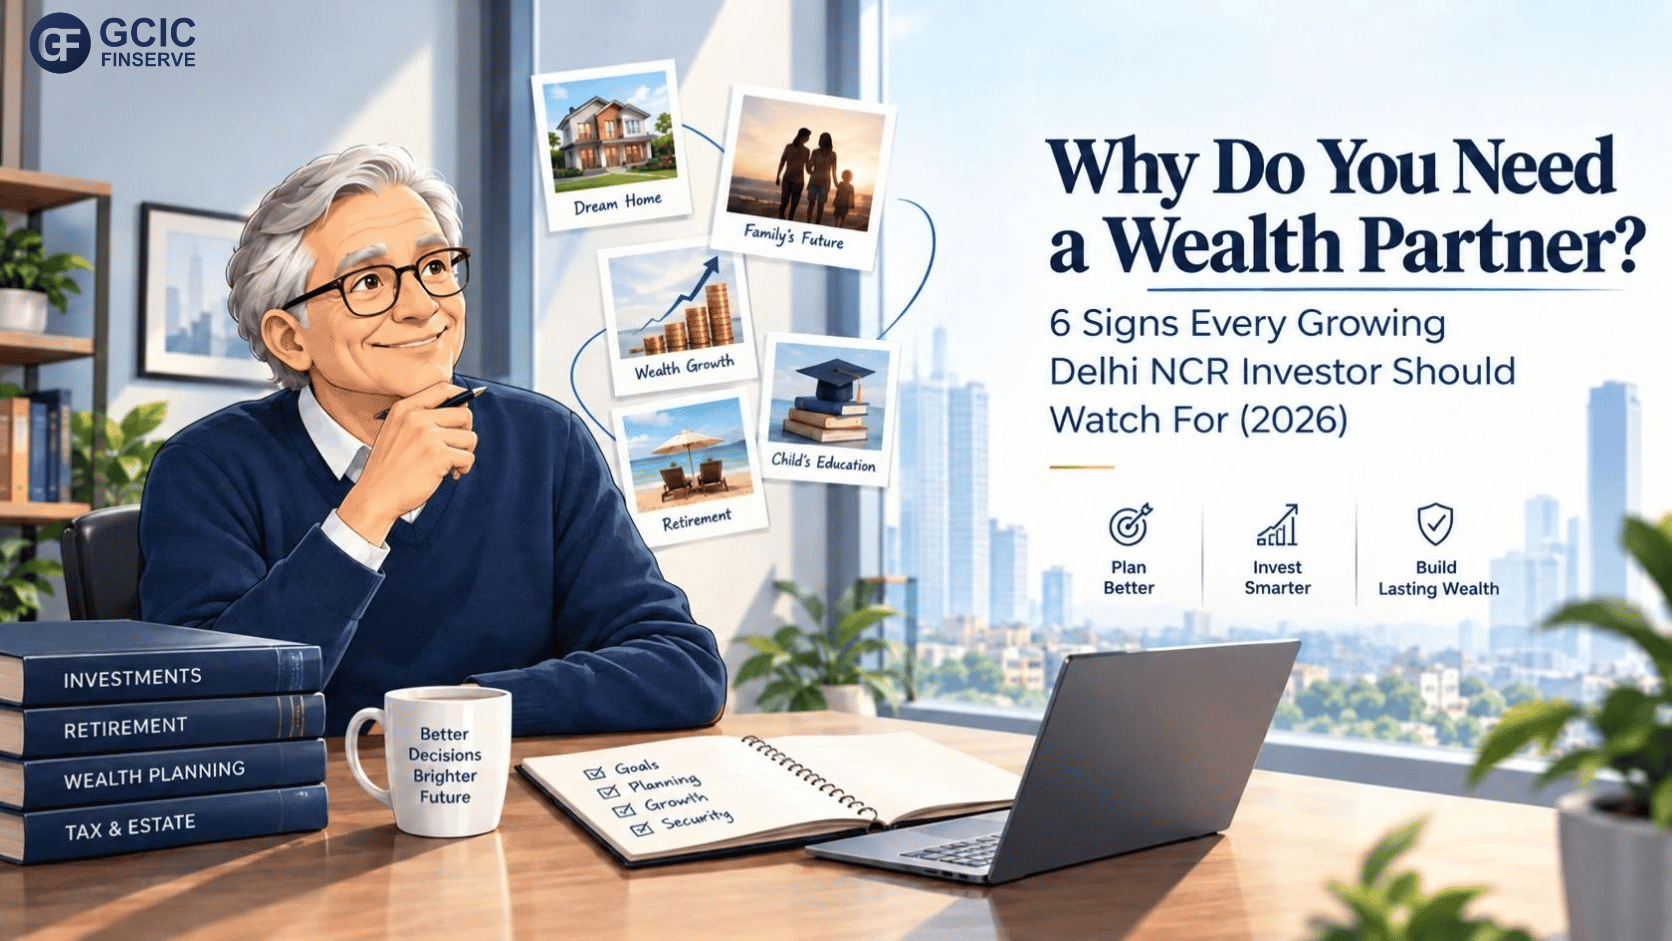
Wealth partner helping an investor organize and manage multiple financial goals
A wealth partner can help bring investments, goals, and financial decisions together.

Why do you need a wealth partner? It’s a question that rarely comes up when you’re just starting out—a few SIPs, a bank account, maybe an insurance policy, and time doing the rest of the work. But as income grows across Delhi NCR’s fast-moving professional and business circles, financial lives rarely stay that simple. Money starts sitting across different institutions—a business, property, insurance, and retirement assets—and the question quietly shifts from “where should I invest?” to “how should all of my wealth work together?”

What Does a Wealth Partner Actually Mean?

At its core, the idea behind why you need a wealth partner comes down to one distinction: managing investments versus managing wealth. An investment is one piece of your financial life; understanding how all those pieces fit together—liquidity, risk, goals, asset allocation—is the broader picture.

Choosing a mutual fund answers where to invest ₹10 lakh. A wider conversation also asks, how much of your total wealth should stay liquid? Are you overexposed to one asset class? How should the portfolio evolve as goals get closer?

Why Do You Need a Wealth Partner as Your Finances Grow?

India’s investment landscape has expanded dramatically, which is part of why the wealth-partner conversation matters more today. According to AMFI India, the mutual fund industry’s assets under management grew from ₹15.63 lakh crore in August 2016 to ₹87.08 lakh crore by August 2026, with folios crossing 28.35 crore.

Investors today can choose from mutual funds, PMS, AIFs, SIFs, bonds, FDs, REITs, and InvITs—more choice, but not necessarily easier decisions.

The real challenge isn’t accessing investments anymore; it’s deciding which ones actually deserve a place in your financial life.

From Products to a Portfolio

Consider someone holding ten different mutual funds. Each may look reasonable individually, but that alone doesn’t confirm the portfolio makes sense—there could be significant overlap, too much exposure to one segment, or insufficient liquidity.

This is exactly where the question of why you need a wealth partner starts to matter: someone who looks beyond individual products and asks what the portfolio as a whole is actually trying to achieve.

From Investments to Decisions

Markets rise and fall, interest rates shift, and personal circumstances change. The hard part usually isn’t knowing what happened—it’s deciding what to do about it.

Should you rebalance? Deploy a cash surplus now or gradually? Move money just because something else recently performed better?

A structured process around these decisions—rather than reacting to headlines—is one of the clearest reasons investors consider professional financial support as their financial life becomes more layered.

What Areas Does This Kind of Support Cover?

The exact scope varies, but typically spans portfolio planning, asset allocation, goal planning, portfolio reviews, identifying concentration or overlap, risk and liquidity management, and rebalancing.

As financial circumstances become more complex, family wealth and succession considerations may also become relevant. Tax, legal, and estate matters usually require separate specialist professionals—coordination across these areas can still be an important part of the broader financial picture.

6 Signs You Might Need a Wealth Partner

  1. Your financial situation has become hard to track on your own—multiple institutions, products, or accounts.
  2. Your investable surplus has grown significantly and now needs a clearer structure.
  3. You have both business and personal wealth that rarely get looked at together.
  4. You’re approaching a major goal—retirement, a child’s education, or a large purchase.
  5. You’re unsure whether your portfolio is genuinely diversified or just spread across many products.
  6. You find yourself making investment decisions reactively, based on headlines rather than a plan.

The real question isn’t “How much money do I have?”—it”‘s “How much financial complexity am I comfortable managing myself?”

You Don’t Need One Just Because You Have Money

This distinction matters.

If your finances are straightforward and you have the time, interest, and discipline to manage everything yourself, doing it independently can work perfectly well.

The need typically emerges from complexity, not net worth alone. Someone with modest wealth but several overlapping goals may value structured support more than someone financially sophisticated with a simple, well-understood portfolio.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705) and APMI-registered PMS Distributor (APRN-08140), we help Delhi NCR investors and families understand their mutual fund and PMS investment options and how these may fit within their broader financial goals and circumstances.

The appropriate approach depends on individual objectives, risk profile, investment horizon, and financial situation.

Connect with our team to discuss your investment requirements and available options.

FAQs

Q1. Is a wealth partner the same as a mutual fund distributor?

Not necessarily. A mutual fund distributor primarily facilitates and services mutual fund investments, while “wealth partner” is a broader term. The exact services and regulatory permissions depend on the specific entity and its registrations.

Q2. Is a wealth partner only for high-net-worth individuals?

No. The need depends more on the complexity of your finances than your net worth alone. Someone with modest wealth but several goals may value structured support just as much.

Q3. Does working with a wealth partner mean giving up control of my investments?

Not necessarily. The structure depends on the services involved. Investors can retain decision-making authority while using professional support for research, planning, and review.

Q4. Can a wealth partner guarantee better investment returns?

No. Returns can never be guaranteed. The value of professional support can lie in portfolio construction, risk management, goal alignment, and disciplined decision-making—not guaranteed return maximization.

Q5. When should I start thinking about this kind of support?

There’s no fixed number. A useful trigger is increasing complexity: more assets, more goals, or more decisions than you’re comfortable managing alone.

Final Word

Why do you need a wealth partner? Ultimately, it comes down to one shift: from making money work to making all of your money work together.

As your financial life across Delhi NCR grows—more assets, more goals, more decisions—the value isn’t necessarily in finding the next best investment alone, but in keeping every piece of your financial picture aligned with what you actually want it to achieve.


Disclaimer: This article is intended for educational and informational purposes only and should not be construed as investment advice, a recommendation, or a solicitation to invest in any particular financial product. Investment decisions should be based on individual financial circumstances, objectives, risk profile, and investment horizon. Past performance is not indicative of future results. Please independently evaluate products and, where appropriate, seek advice from suitably qualified and regulated professionals.
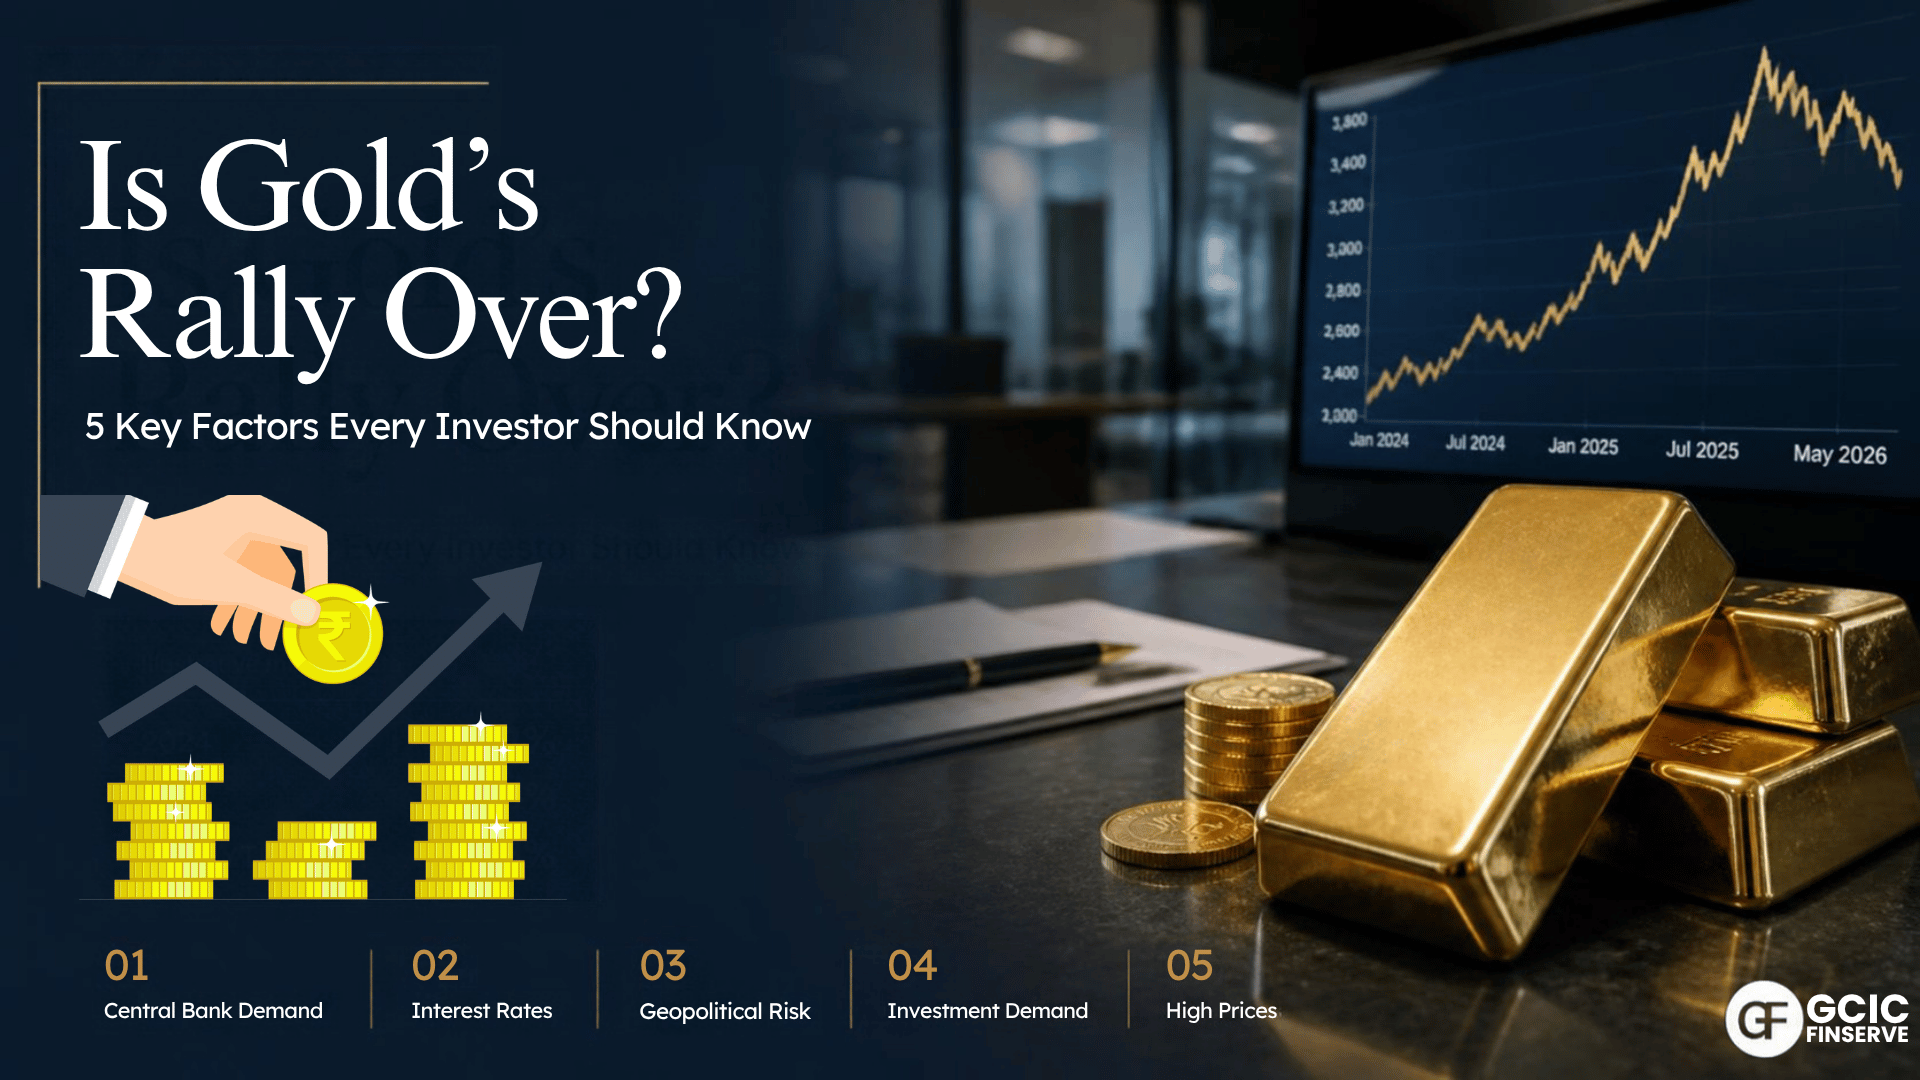
Is Gold’s Rally Over? 5 Key Factors Every Delhi NCR Investor Should Know

is gold's rally over gold investment market analysis
Gold’s strong rally brings both opportunities and risks for investors.

Is gold’s rally over? That’s the question on many investors’ minds after gold delivered one of its strongest runs in recent memory. In India, gold gained around 21% in 2024, while domestic gold prices rose roughly 75% in 2025.

By Q2 2026, gold prices had pulled back from their early-year highs but remained historically elevated, with India’s domestic gold price still around 59% higher than a year earlier.

After a run like that, the question isn’t simply “Why is gold rising?” anymore. The bigger question is whether the forces behind the rally can continue.

Why Gold Hasn’t Risen for Just One Reason

It’s tempting to explain gold’s rally with a single word—”uncertainty. “The real picture is more complicated.

Geopolitical uncertainty, investor demand for diversification, expectations around interest rates, movements in the US dollar, and continued central-bank buying have all influenced gold demand.

Gold also benefited from strong investment demand during 2025. The World Gold Council reported that global gold demand exceeded 5,000 tonnes in 2025 for the first time, while global investment demand reached 2,175 tonnes, an 84% increase from 2024.

So, gold didn’t rise because of one single factor. Several forces supported the rally at the same time.

What Is Gold Actually Used For?

Gold’s investment story gets most of the headlines, but investment isn’t its only role.

Gold is also widely used for jewellery, central bank reserves, and technology applications. In India, jewellery continues to be an important part of gold demand even though high prices have changed purchasing behaviour.

Globally, the 2025 gold market showed an interesting contrast. Investment demand increased strongly, while jewellery demand fell as prices moved higher. The World Gold Council reported that global jewellery consumption declined 18% in 2025, even though the value of jewellery demand increased by 18%.

That tells us something important: when gold becomes expensive, consumers may buy less gold by weight while still spending significant amounts of money on it.

India’s Gold Demand Is Adapting, Not Disappearing

India provides a good example of this behavior.

In Q2 2026, Indian gold demand fell to 131 tonnes, down 6% year-on-year. Jewellery demand fell 15% year-on-year to 75 tonnes. Yet the value of India’s gold demand reached a quarterly record of approximately ₹1.979 lakh crore, up 35% year-on-year.

In other words, Indians were buying less gold by weight but spending more because prices were much higher.

Consumers have also been adapting by choosing lighter jewellery, lower-carat products, and old-gold exchanges. The World Gold Council noted that these changes have helped consumers manage affordability while maintaining their connection with gold.

For Delhi NCR households, this distinction matters. A strong gold price does not necessarily mean demand disappears. Instead, the way people buy gold can change.

What About Gold Supply?

Gold supply is another important part of the story.

The global gold supply reached approximately 5,002 tonnes in 2025, up around 1% from 2024. Mine production increased modestly, while recycled gold supply rose around 3%.

In India, however, Q2 2026 supply fell to a six-year low. The World Gold Council noted that adequate domestic inventories and recycling helped meet market requirements, meaning the lower supply did not indicate that the world was simply “running out of gold.”

This is important because gold behaves differently from commodities that are consumed permanently. Much of the gold ever mined remains in circulation in some form and can potentially return to the market.

Reasons the Rally Could Continue—or Cool Down

There are genuine reasons why gold could remain supported.

Central-bank demand remains important. Central banks bought around 863 tonnes of gold in 2025, significantly above the 2010–2021 annual average of 473 tonnes. In Q2 2026 alone, central bank net purchases reached approximately 289 tonnes, although the first-half pace remained below recent years.

Investment demand is another important factor. The World Gold Council expects investment to remain the principal source of gold-demand growth through the second half of 2026, with Asian investment and OTC activity expected to contribute significantly.

At the same time, there are reasons for caution.

High gold prices are putting pressure on jewellery demand. In Q2 2026, global jewellery demand fell 17% year-on-year, while Indian jewellery demand fell 15%. Investment demand outside OTC markets also declined to 262 tonnes during the quarter, partly reflecting gold ETF outflows.

So the picture isn’t simply “gold will keep rising” or “gold is about to crash. “Both supporting and opposing forces are present.

So, Is Gold’s Rally Over?

Is gold’s rally over? There is no reliable way to know for certain.

The case for continued support includes central bank buying, investment demand, geopolitical uncertainty, and the possibility of changing interest-rate conditions.

The case for caution includes elevated prices, weaker jewellery volumes and periods of reduced investment demand.

The World Gold Council’s Q2 2026 outlook expects investment to remain an important driver during the second half of 2026, while central banks are expected to remain significant buyers. At the same time, high prices are expected to continue weighing on jewellery volumes.

That makes the current environment more nuanced than simply asking whether gold will go up or down next.

The Real Risk May Be FOMO

There’s a psychological trap hiding underneath a major rally.

Someone who bought gold several years ago may have seen a significant increase in value. Someone who didn’t buy may now feel that they have missed their opportunity.

That’s where FOMO—fear of missing out—can become dangerous.

The thought process can quickly become:

“Gold has already gone up so much. I should buy before it goes even higher.”

But past performance doesn’t tell you what will happen next.

The more useful question isn’t simply “Is gold a good investment?”

It’s:

“What role should gold play in my overall financial plan?”

For some investors, gold may have a role in diversification. For others, physical gold may primarily serve cultural, family or wealth-preservation purposes. The appropriate allocation depends on the individual’s goals, existing portfolio, risk profile, and investment horizon.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, an AMFI-registered Mutual Fund Distributor (ARN-272705), we believe gold deserves to be understood rather than chased.

A decision to buy gold simply because it has recently delivered strong returns is very different from allocating to gold because it has a clearly defined role in your overall portfolio.

Before making a decision, investors should consider:

  • Their existing asset allocation
  • Financial goals
  • Investment horizon
  • Risk tolerance
  • Liquidity requirements
  • Existing exposure to gold

If you’re considering gold alongside mutual funds or other investments, understanding how each asset fits into the overall portfolio can be more useful than focusing only on recent returns.

You can also refer to the World Gold Council’s gold-market research for updated information on global gold demand, supply, and market trends.

FAQs

Q1. Is gold’s rally over after such a strong run?

There is no reliable way to know. Gold continues to have support from investment demand and central-bank buying, while high prices are putting pressure on jewellery demand and making investors more price-sensitive.

Q2. How much has gold risen in India recently?

Gold gained around 21% in India during 2024, while domestic gold prices rose roughly 75% in 2025. By Q2 2026, India’s domestic gold price remained approximately 59% higher than a year earlier, despite a moderation from early-2026 highs.

Q3. Is gold in short supply right now?

There is no simple global shortage story. The global gold supply reached around 5,002 tonnes in 2025, with mine production and recycling contributing to the supply. India’s Q2 2026 supply fell to a six-year low, but the World Gold Council noted that inventories and recycling provided a buffer.

Q4. Should I invest in gold after its recent rally?

There is no universal answer. The decision should depend on your financial goals, existing asset allocation, investment horizon, liquidity needs, and risk tolerance rather than gold’s recent performance alone.

Q5. Can gold prices fall after a major rally?

Yes. Gold prices can decline, sometimes sharply, even after a strong period of appreciation. Investors should therefore avoid assuming that past price increases guarantee future returns.

Final Word

Is gold’s rally over? That’s a question the market cannot answer with certainty in advance.

Gold still has structural support from investment demand and central-bank interest, but elevated prices are also changing consumer behavior and putting pressure on jewelry demand.

For investors, the more useful question may not be whether gold will rise next month or next year. It is whether gold has a clear and appropriate role in their overall financial plan.

After a major rally, avoiding FOMO can be just as important as understanding the reasons behind the rally.

Disclaimer

This article is for educational and informational purposes only and should not be construed as investment advice or a guarantee of returns. Gold prices can be volatile and may decline substantially. Mutual fund and other market-linked investments are subject to market risks. Investors should consider their financial objectives, risk profile, investment horizon and liquidity requirements before making investment decisions. Please read all relevant product and scheme-related documents carefully and consult a qualified financial professional where appropriate.

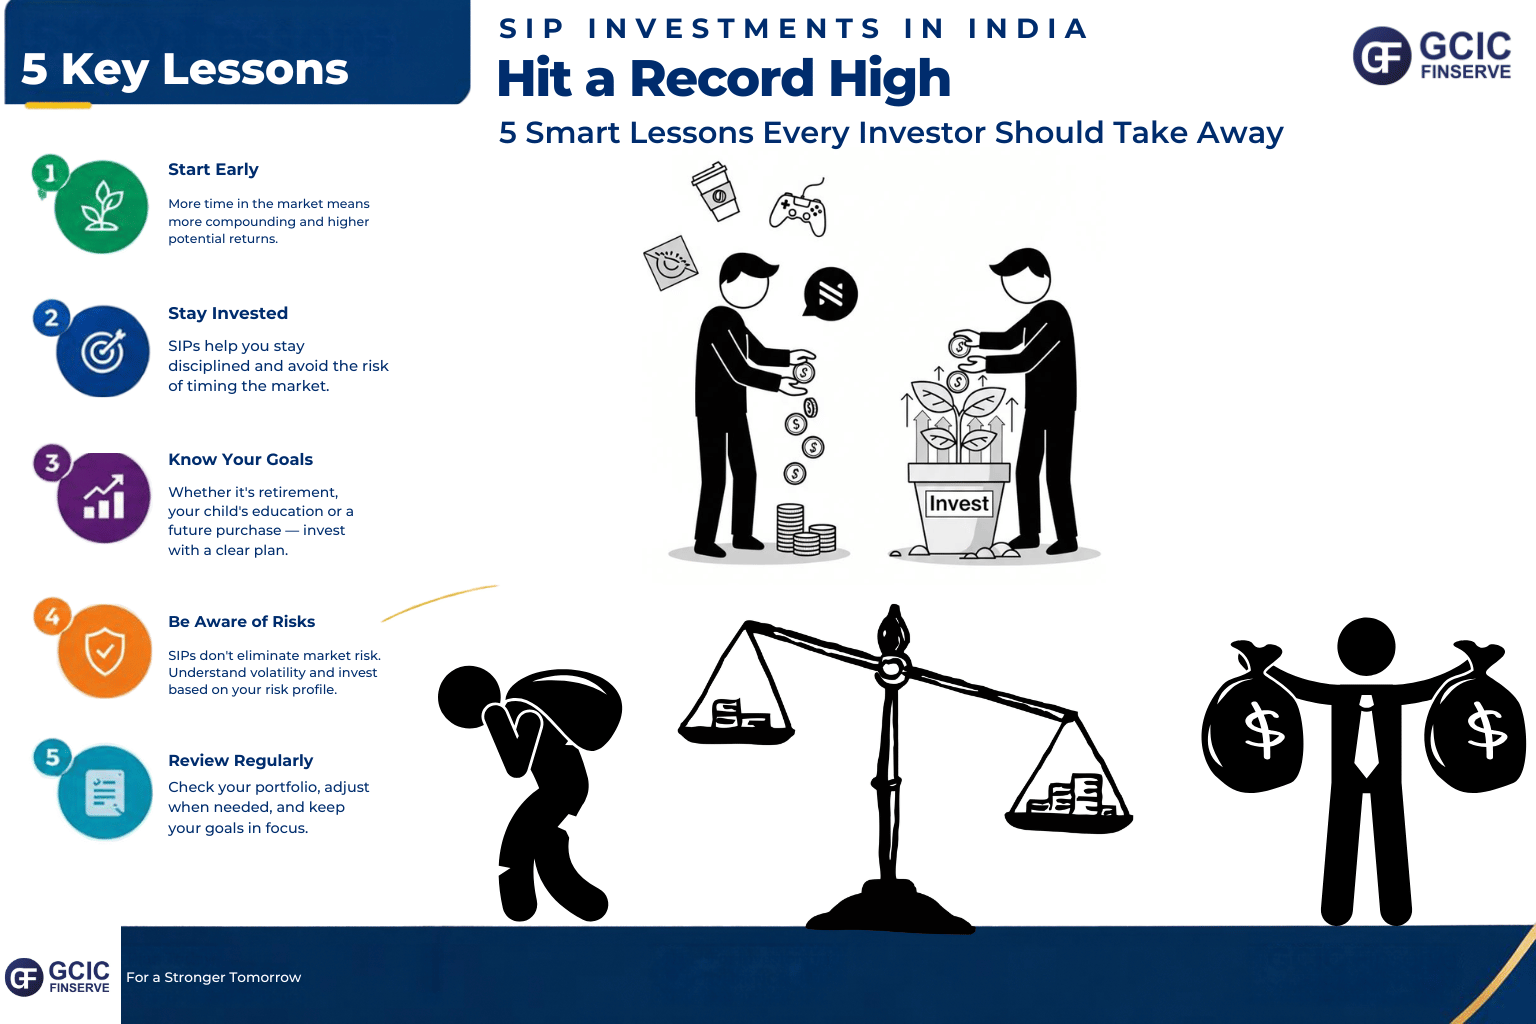
SIP Investments in India Hit a Record High: 5 Smart Lessons Every Delhi NCR Investor Should Take Away

SIP investments in India hit a record high with ₹32,297 crore monthly contribution in August 2026
India’s monthly SIP contribution reached a record ₹32,297 crore in August 2026, according to AMFI data.

SIP investments in India hit a record high of ₹32,297 crore in August 2026—the highest monthly SIP contribution ever recorded by AMFI. Ten years earlier, in August 2016, that number was just ₹3,497 crore. That’s a more than nine-fold jump in a decade. But behind this headline number is a much more interesting story for Delhi NCR investors: how Indians are quietly changing the way they think about money and what the cost of waiting to invest actually looks like.

Just How Big Is India’s SIP Boom?

The scale becomes clear when you place the numbers side by side. Monthly SIP contributions rose from ₹3,497 crore in August 2016 to ₹32,297 crore in August 2026. Outstanding SIP accounts reached 10.75 crore, with 10.02 crore actually contributing that month, and SIP assets under management touched ₹18.62 lakh crore. AMFI also recorded 66.40 lakh new SIP registrations in August alone, against 53.82 lakh SIPs that were discontinued or completed—a net addition of roughly 12.58 lakh accounts in just one month. SIP investments in India hitting a record high comes as part of a much larger increase in SIP participation over the past decade. 

The Bigger Mutual Fund Story Behind the Numbers

SIPs are just one part of a much larger transformation. India’s overall mutual fund industry AUM stood at ₹87.08 lakh crore at the end of August 2026, up roughly six-fold from ₹15.63 lakh crore in August 2016. Mutual fund folios have grown from 10.86 crore in August 2021 to 28.35 crore in August 2026—more than a two-and-a-half-fold increase in just five years, with roughly 21.62 crore of those folios in equity, hybrid, and solution-oriented schemes. For Delhi NCR households, this points to something bigger than a passing trend: organized, systematic investing is becoming the norm rather than the exception.

Why Has the SIP Become So Popular?

The appeal is part mathematics, part psychology. Ask someone to invest ₹12 lakh in one go, and it immediately raises hard questions—where will the money come from, is the market at the right level, and what if it falls right after? Ask instead, “Can you invest ₹10,000 a month?” and the decision suddenly feels manageable. According to AMFI, a SIP, is simply a method of investing a fixed amount periodically in a mutual fund scheme, helping investors stay disciplined without trying to time the market. It’s worth remembering: a SIP is a method of investing, not an investment product in itself—the underlying mutual fund is what actually carries the risk and return.

The Real FOMO Isn’t About Missing the Next Rally

The common fear is “the market went up; I should have invested earlier.” But that’s not the FOMO that matters most. Consider two people who both could have started investing ₹10,000 a month five years ago—one did, one kept waiting for the “right time.” Five years later, the person who started has something the other person can never buy back: five years of investment time. You can increase your SIP amount later, change your strategy later, or even recover from a bad investment choice later—but you cannot recover lost time.

What Does Starting Early Actually Do?

Here’s a simple illustration. Investing ₹10,000 every month for 20 years means a total contribution of ₹24 lakh, which at an illustrative 12% annualized return could grow to approximately ₹99 lakh. Wait five years, and investing the same ₹10,000 monthly for only 15 years brings the total contribution down to ₹18 lakh, with an illustrative corpus of around ₹50 lakh. (These are hypothetical illustrations, not guaranteed returns—actual outcomes depend on market performance, fund selection, costs, and taxes.) The investor who waited contributed just ₹6 lakh less, yet the eventual illustrative gap is far larger—because those extra five years of compounding matter more than the headline contribution amount.

The Other Side of the SIP Story

Record SIP contributions shouldn’t push anyone into investing blindly. When your colleague has an SIP, your friend has three mutual funds, and headlines talk about ₹32,297 crore flowing in every month, it’s easy to feel like you’re “behind”—but that’s FOMO, not a strategy. The fact that millions of Delhi NCR residents (and Indians nationwide) are investing through SIPs doesn’t tell you what to invest in, how much risk to take, or which mutual fund category actually suits your goal. It’s also worth remembering that an SIP doesn’t remove market risk—if you’re invested in equity mutual funds, your value can still fall when markets fall. A SIP simply means you keep investing on schedule; it doesn’t eliminate volatility.

3 Questions to Ask Before Starting a SIP

Before jumping in because “SIP investments in India hit a record high” made headlines, ask yourself:

  1. What am I actually investing for? Retirement, a child’s education, or a future purchase can each call for a different approach.
  2. How long can I realistically stay invested? Your time horizon should match the volatility you’re willing to sit through.
  3. How much can I invest without disrupting my monthly budget? A sustainable SIP beats an aggressive one you can’t maintain past a few months.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, AMFI-registered Mutual Fund Distributor (ARN-272705), we see the SIP boom as a genuine shift in household financial behavior—but record flows should never replace a plan built around your own goals and risk profile. If you have a long-term goal and keep postponing simply because the timing never feels perfect, it’s worth understanding what that delay is actually costing you in lost compounding time. Connect with our team to understand which mutual fund categories might suit your goals. For the latest official SIP and mutual fund industry data, refer to AMFI India’s official reports.

FAQs

Q1. Are SIP investments in India really at a record high?

Yes—AMFI reported ₹32,297 crore in monthly SIP contributions in August 2026, the highest in its published series.

Q2. Does a record SIP contribution mean the stock market will rise? No. SIP flows reflect investor participation, not a reliable signal of future market direction.

Q3. Is it too late to start a SIP now that contributions are at record highs? 

There’s no universal answer—it depends on your goals, horizon, and risk tolerance. But waiting indefinitely for a “perfect” entry point can mean losing valuable compounding time.

Q4. Does starting a SIP early guarantee higher returns? 

No. Starting earlier gives your investment more time to potentially compound, but actual returns still depend on market performance and the underlying fund.

Final Word

SIP investments in India hitting a record high isn’t a signal to rush in—it’s a signal that Indian investors, including many across Delhi NCR, are increasingly treating investing as a recurring habit rather than a one-time event. You don’t need to feel FOMO because someone else started before you. But if investing genuinely fits your goals, understand what indefinite postponement is costing you. The market will offer many entry points over your lifetime—time is the one entry point you can’t revisit.

Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. This article is for educational and informational purposes only and should not be construed as investment advice or a guarantee of returns. The illustrations used are hypothetical. Please assess your own financial circumstances and, where appropriate, consult a qualified financial professional before investing. Data source: Association of Mutual Funds in India (AMFI), August 2026.

Selling During a Market Crash: 5 Costly Lessons Every Investor Should Know

Selling during a market crash: investor journey from ₹60 lakh to ₹40 lakh and missed recovery
A visual story showing how panic selling during a market crash can lead to missed recovery and future compounding opportunities.

Selling during a market crash can feel like the safest decision in the moment. But when markets recover, investors who sold in panic can sometimes find themselves facing a different problem: how and when to get back in.

This is the story of Arjun, a fictional investor based on a situation many Delhi NCR investors can relate to. One five-minute decision during a period of market panic changed the way he approached his long-term investment journey.

The Setup: A Normal Long-Term Investment

In 2010, Arjun invested ₹25 lakh into a diversified equity portfolio with a simple goal: build wealth over the next 15–20 years and support his family’s future needs.

He wasn’t trading or looking for quick profits. For years, his plan worked reasonably well. His portfolio went through good years, bad years, and a few uncomfortable corrections.

Arjun understood that markets don’t move in a straight line, so he stayed invested. Then came a market fall that tested that confidence.

For investors who want to understand how different investment structures work, our guide on Mutual Funds vs PMS and AIFs explains the key differences between these options.

When ₹60 Lakh Started Looking Like ₹40 Lakh

At its peak, Arjun’s portfolio had grown to roughly ₹60 lakh.

Then the market entered a sharp decline. The value moved from ₹55 lakh to ₹48 lakh, then ₹42 lakh, and eventually ₹40 lakh.

Almost ₹20 lakh had disappeared from the portfolio value.

Arjun knew, in theory, that equity markets could fall. But watching his own money decline day after day felt very different from reading about market volatility in an article—the numbers started becoming emotional.

Market volatility is a normal part of investing, but the way an investor responds to it can have a major impact on their investment journey. SEBI’s investor-education material explains volatility risk and discusses diversification as one way investors can manage different investment risks. (SEBI Investor)

The Moment of Selling During a Market Crash

One evening, Arjun called his advisor and said,

“I don’t want to lose any more.”

He wasn’t asking what fund to buy next—he had already made up his mind.

Despite being reminded about his long-term goal, Arjun sold his remaining equity investments and moved ₹40 lakh into cash.

For the first time in weeks, he felt relieved.

At least, he thought, the portfolio couldn’t fall any further.

Selling during a market crash felt like the safest decision at that moment.

But the difficult part came later.

What Happened After He Sold

The market eventually stopped falling—and started recovering.

Arjun told himself he would invest again “when things became clearer.”

But clarity didn’t arrive on his preferred schedule.

The market recovered 10%, then another 10%. Arjun continued waiting for a clear signal that it was safe to return.

By the time the market looked comfortable again, prices had already moved significantly higher, and buying back in suddenly felt expensive.

So he waited for another correction—one that didn’t arrive when he expected it.

Months became years, and the investor who had successfully avoided the fall ended up missing a significant part of the recovery.

NISM investor-education material similarly highlights the role of disciplined investing, long-term planning, and avoiding emotion-driven decisions during market fluctuations. (NISM)

The Two Paths: Staying Invested vs Staying in Cash

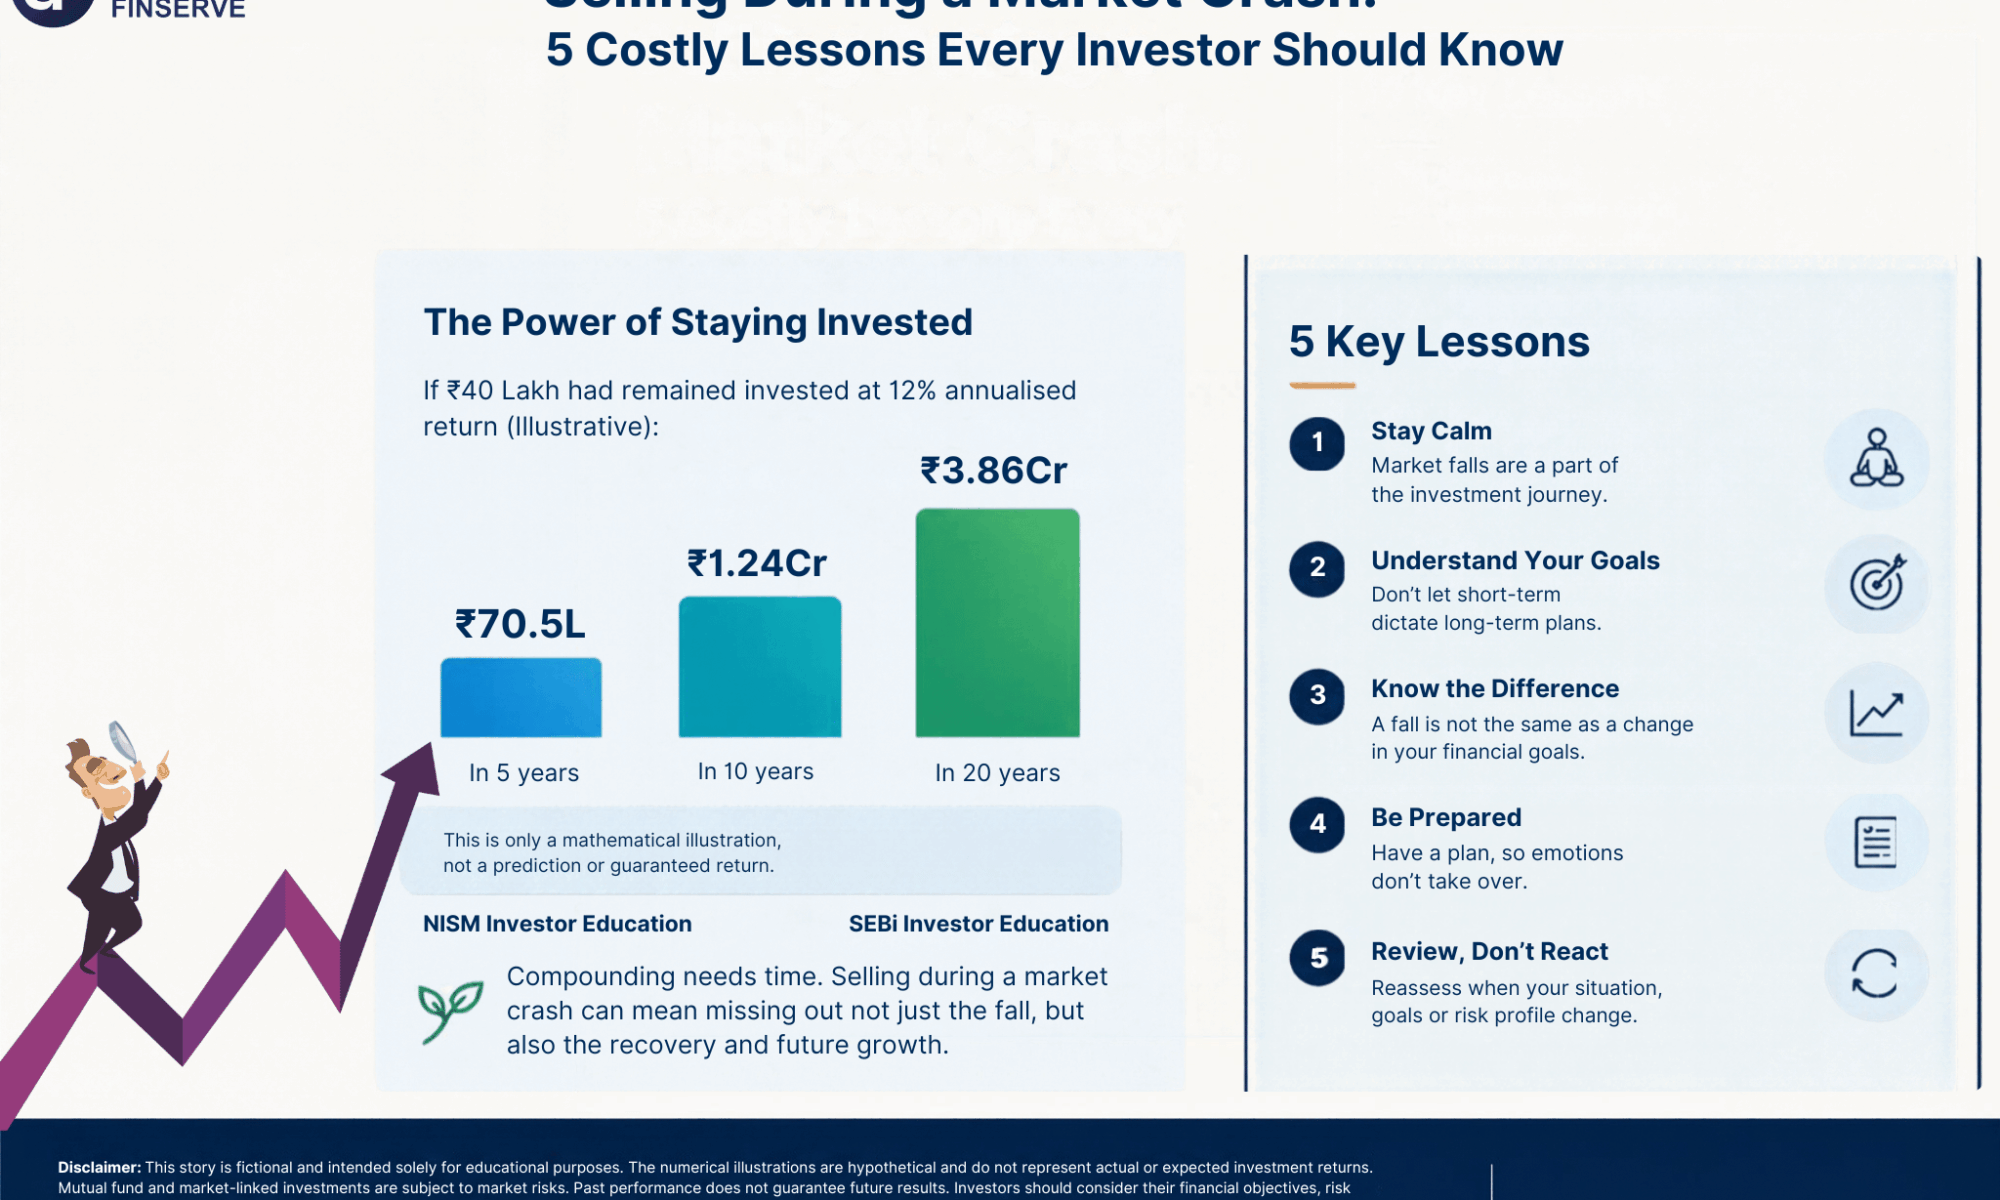
If Arjun’s ₹40 lakh had remained invested and earned an illustrative 12% annualized return, it could have grown to approximately ₹70.5 lakh in 5 years, ₹1.24 crore in 10 years, and ₹3.86 crore in 20 years.

(This is only a mathematical illustration, not a prediction or guaranteed return.)

Instead, if the ₹40 lakh simply remained as cash, it would still be approximately ₹40 lakh, ignoring interest, inflation, and taxes.

The important point is that compounding needs time—when an investor sells during a market crash, they may not just miss the fall, they can also miss the recovery and the future compounding that follows.

For more on how investment behavior can affect long-term outcomes, investors can also explore NISM’s educational material on disciplined investing and staying invested through market fluctuations. (NISM)

The Real Cost Wasn’t the Fall—It Was the Recovery He Missed

Consider an even simpler example.

Suppose an investor has ₹1 crore and the market falls by 30%.

The portfolio becomes ₹70 lakh.

To get from ₹70 lakh back to ₹1 crore, the portfolio needs to rise by approximately 42.9%, not 30%.

Now imagine the investor sells at ₹70 lakh.

If the market subsequently rises by 50%, the investor who stayed invested would have approximately ₹1.05 crore, while the investor who sold would still have ₹70 lakh if that money remained in cash.

This doesn’t mean investors should never sell—it simply shows why selling during a market crash can create another challenge: participating in the recovery.

Should You Never Sell?

Absolutely not—that would be the wrong lesson to take from this story.

There can be perfectly valid reasons to sell or reduce an investment: your financial goal has changed, your investment horizon has become shorter, your risk tolerance has changed, your circumstances are different, or the underlying investment case no longer fits your original plan.

These situations deserve a proper review.

The bigger concern is selling purely because the market is falling, without anything about your actual plan having changed.

Before selling during a market crash, ask yourself:

“If the market hadn’t fallen, would I still believe this portfolio is right for my long-term goal?”

If the answer is yes, your goal hasn’t changed—only the market value has.

That distinction can be important.

If you’re reviewing your mutual fund portfolio, you may also find our guide on Why Is My Mutual Fund Underperforming? useful for understanding whether underperformance is temporary or something that requires a deeper review.

GCIC Finserve’s Take

Arjun’s story is fictional, but the behavior behind it is something many Delhi NCR investors can relate to during difficult market cycles.

At GCIC Finserve, AMFI-registered Mutual Fund Distributor (ARN-272705), we believe investment decisions should be reviewed in the context of your financial goals, risk profile, investment horizon, and underlying investments—not simply because markets have temporarily fallen.

A market correction can be uncomfortable, but making a long-term decision during a short-term period of fear can have consequences.

Before selling during a market crash, take a step back and review whether your original plan has actually changed.

Investors can also refer to NISM’s investor-education resources for information on disciplined investing, financial planning, and understanding market fluctuations. NISM’s recent investor-education material specifically highlights disciplined investing and avoiding emotional decision-making during market cycles. (NISM)

For additional information about mutual fund risks, investors can refer to AMFI’s investor education resources. AMFI notes that mutual fund investments are subject to market-related risks and that returns are not guaranteed. (AMFI India)

If you’re unsure whether your portfolio still fits your goals, connect with GCIC Finserve or consider discussing your situation with a qualified financial professional before making a major investment decision.

FAQs

Q1. Is selling during a market crash ever a good idea?

It can be appropriate when your financial goals, investment horizon, risk tolerance, or the underlying investment have genuinely changed.

Selling purely because of short-term market fear, however, can make it difficult to participate in a subsequent recovery.

Q2. How much does a portfolio need to recover after a 30% fall?

A portfolio that falls 30% needs approximately a 42.9% gain to return to its original value.

Q3. Why do investors often miss the recovery after selling?

Markets don’t usually provide a clear signal telling investors exactly when the recovery has begun.

Investors waiting for “confirmation” may re-enter only after prices have already moved higher.

Q4. What should I ask myself before selling during a market crash?

Ask whether your original investment goal, time horizon, and reason for investing have changed.

If they haven’t, consider whether the decision is being driven mainly by short-term market fear.

Q5. Should I stop investing when the market falls?

There is no single answer for every investor.

The appropriate approach depends on your goals, risk profile, time horizon, and financial circumstances.

A market fall by itself does not automatically mean an existing investment plan is no longer suitable.

Final Word

A market fall is an event. Your response to it is a decision—and the two don’t necessarily have to be treated as the same thing.

Arjun didn’t need to predict the market bottom or buy at the lowest possible price.

He simply needed to understand the difference between a temporary market decline and a genuine change in his plan.

Sometimes, the biggest cost of selling during a market crash isn’t the loss you lock in—it’s the recovery and future compounding you may miss.

Disclaimer: This story is fictional and intended solely for educational purposes. The numerical illustrations are hypothetical and do not represent actual or expected investment returns. Mutual fund and market-linked investments are subject to market risks. Past performance does not guarantee future results. Investors should consider their financial objectives, risk profile, and investment horizon before making investment decisions. Please consult a qualified financial professional for advice specific to your circumstances.

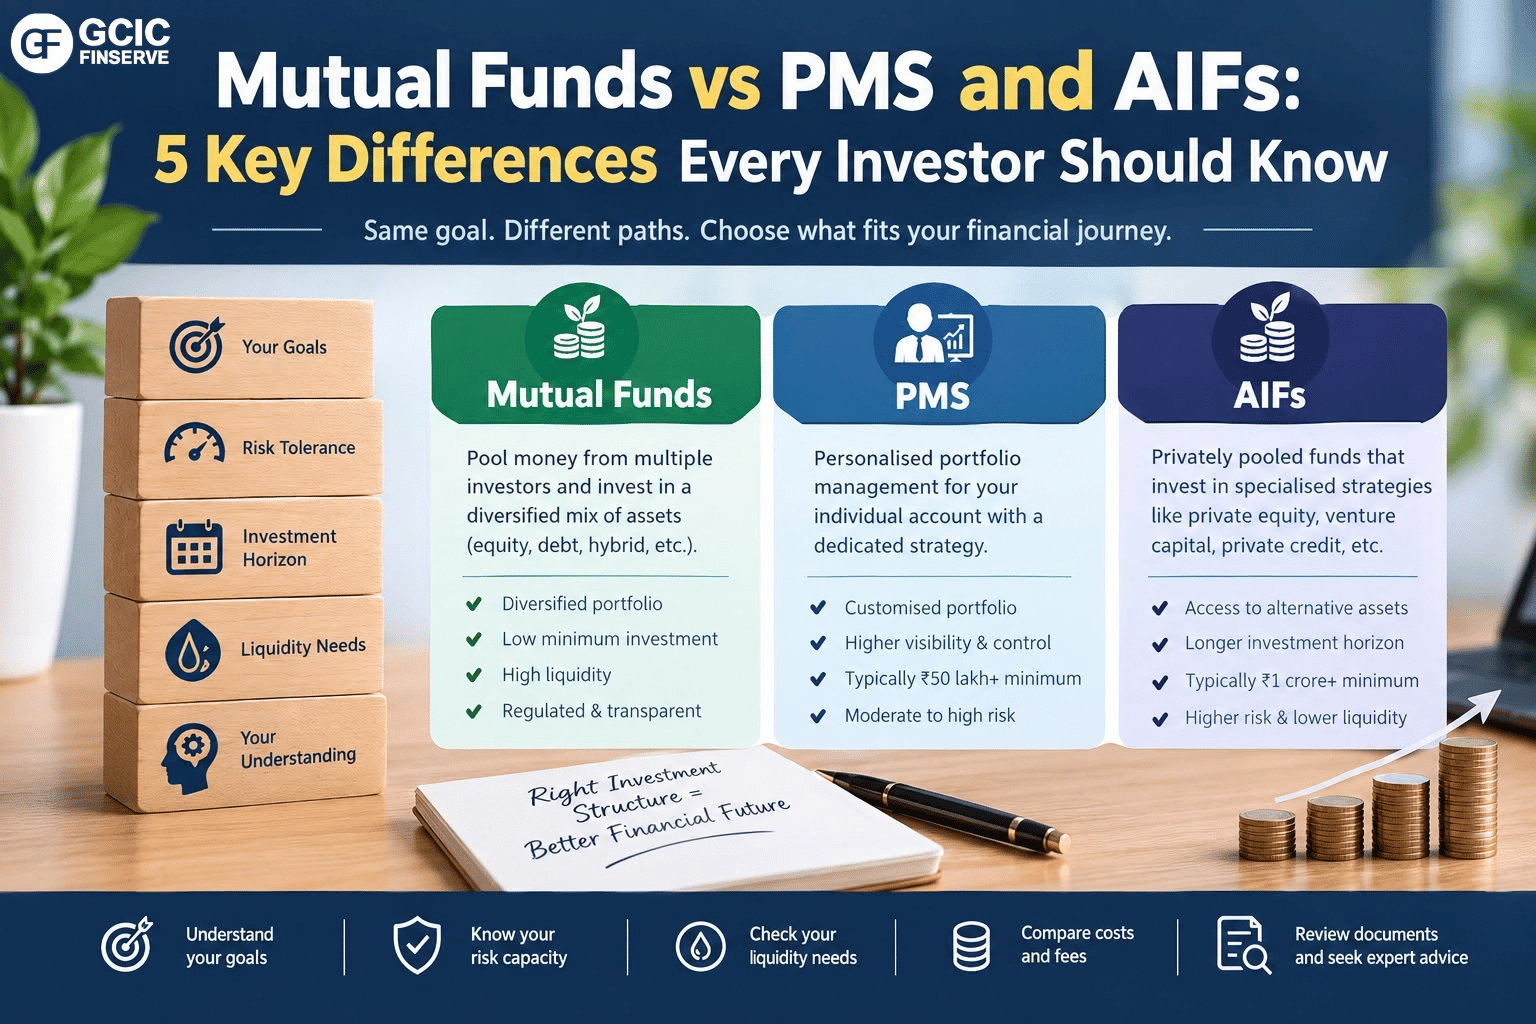
Mutual Funds vs PMS and AIFs: 5 Key Differences Every Investor Should Know

Mutual funds vs PMS and AIFs: key investment differences
Mutual Funds vs PMS and AIFs – understand the key differences in investment structure, customisation, risk, liquidity and costs.

As an investment portfolio grows, many investors begin comparing mutual funds vs PMS and AIFs. Mutual funds, Portfolio Management Services (PMS), and Alternative Investment Funds (AIFs) offer different ways to invest, manage risk, and access financial opportunities.

However, a more specialized investment structure is not automatically better. The right choice depends on your financial goals, risk tolerance, investment horizon, liquidity requirements, and level of understanding.

Three Investment Structures Explained Simply

Mutual Funds

A mutual fund pools money from multiple investors. The fund manager invests this money according to the scheme’s stated objective.

Mutual funds may invest in equity, debt, hybrid instruments, and other permitted securities. Investors own units of the scheme rather than directly owning every security in the portfolio.

Portfolio Management Services (PMS)

PMS involves managing investments in an investor’s individual account according to an agreed strategy.

Depending on the arrangement, PMS may provide greater portfolio visibility and customization. However, the strategy, costs, concentration, and risks vary between providers.

Alternative Investment Funds (AIFs)

AIFs are privately pooled investment vehicles that follow specific investment strategies. Depending on the category and mandate, an AIF may invest in private equity, venture capital, private credit, or other permitted investments.

AIFs can involve longer investment horizons, limited liquidity, and specialised risks.

Mutual Funds vs PMS and AIFs: 5 Key Differences

1. Ownership and Investment Structure

In a mutual fund, investors own units of a common scheme.

In PMS, the underlying securities are generally held in the investor’s individual account, subject to the service arrangement.

In an AIF, investors participate in a pooled investment structure and follow the fund’s defined strategy.

The ownership structure affects transparency, control, reporting, and how investments are managed.

2. Portfolio Customisation

Mutual funds generally follow one investment strategy for all investors in the scheme.

PMS can offer greater customisation because the portfolio is managed for an individual investor. However, the degree of customisation depends on the specific PMS strategy and agreement.

AIF investments usually follow a common strategy defined in the fund’s documents rather than being individually customised for every investor.

More customisation does not necessarily mean lower risk. A concentrated portfolio may increase exposure to specific companies, sectors, or investment themes.

3. Investment Opportunities

Mutual funds provide access to various permitted asset classes, including equity, debt, and hybrid investments.

PMS strategies may focus on listed equities, debt, or other permitted securities, depending on the portfolio manager’s mandate.

AIFs may provide access to specialised opportunities such as:

  • Private equity
  • Venture capital
  • Private credit
  • Specialised investment strategies
  • Other permitted alternative investments

The availability of these opportunities depends on the fund’s category, mandate, and regulatory framework.

4. Liquidity and Investment Horizon

Liquidity refers to how easily an investment can be converted into cash.

Mutual funds generally offer relatively convenient purchase and redemption mechanisms, although the applicable rules vary by scheme.

PMS liquidity depends on the securities held and the investment strategy.

AIFs may have lock-in periods, limited exit opportunities, or longer investment commitments, particularly when they invest in private or less-liquid assets.

Before investing, understand:

  • Lock-in period
  • Exit conditions
  • Redemption process
  • Possible exit charges
  • Expected investment duration

5. Minimum Investment, Costs and Risks

Mutual funds are available across a wide range of investment amounts, depending on the scheme.

For PMS, the general regulatory minimum investment requirement is ₹50 lakh, subject to applicable regulations and exceptions.

For AIFs, the general minimum investment requirement is ₹1 crore, with specific exceptions, including provisions applicable to accredited investors. Always verify the current regulatory requirements before investing.

Costs also differ between these structures. Investors should review:

  • Management fees
  • Expense ratios
  • Performance-linked fees
  • Exit charges
  • Other applicable expenses

Higher fees or greater complexity do not guarantee better investment performance.

When Mutual Funds May Be Suitable

Mutual funds may be suitable for investors looking for diversified exposure through a professionally managed structure.

They can be considered for goals such as:

  • Long-term wealth creation
  • Retirement planning
  • Children’s education
  • Systematic investing
  • Asset allocation

The suitability of a mutual fund depends on its investment objective, risk level, costs, and alignment with the investor’s goals.

A growing portfolio does not automatically require an investor to shift away from mutual funds.

When PMS May Be Considered

PMS may be considered by investors who require a more personalised investment approach and understand the associated risks and costs.

Potential features may include:

  • Individual portfolio management
  • Greater visibility of holdings
  • Strategy-based customisation
  • Direct ownership of underlying securities

However, PMS portfolios may be more concentrated and can experience significant fluctuations. Investors should carefully evaluate the portfolio manager, strategy, fees, risk management process, and track record.

Past performance does not guarantee future results.

When an AIF May Be Suitable

AIFs may be considered by eligible investors seeking exposure to specialised investment strategies or asset classes.

Depending on the AIF category, investments may involve private companies, venture capital, private credit, or other alternative assets.

Before investing, assess:

  • Investment strategy
  • Fund category
  • Lock-in period
  • Liquidity risks
  • Capital commitment
  • Fees and expenses
  • Risk disclosures
  • Exit and distribution terms

An AIF should be selected based on its specific investment purpose rather than its exclusive or sophisticated image.

Is PMS or an AIF Automatically Better Than a Mutual Fund?

No investment structure guarantees superior returns.

A mutual fund, PMS strategy, or AIF may perform differently depending on market conditions, investment decisions, costs, and portfolio construction.

Instead of asking which product is more sophisticated, consider:

What specific purpose will this investment serve in my portfolio?

The investment structure should match your financial goals, risk capacity, liquidity needs, and investment knowledge.

5 Questions to Ask Before Investing

Before moving money from mutual funds into PMS or AIFs, ask yourself:

  1. What financial goal am I trying to achieve?
  2. What additional benefit does this investment provide?
  3. How much liquidity am I giving up?
  4. Do I understand all costs and risks?
  5. Am I choosing the strategy or simply following recent returns?

A detailed review can help you understand whether the proposed investment fits your overall financial plan.

GCIC Finserve’s Perspective

At GCIC Finserve, we help investors understand different investment structures based on their financial goals, risk profile, and liquidity requirements.

As an AMFI-registered Mutual Fund Distributor (ARN-272705), AMFI-registered SIF Distributor, and PMS Distributor (APRN-08140), our team helps investors evaluate the role of mutual funds, PMS, and AIFs within their overall investment strategy.

Before making an investment decision, review the relevant product documents and understand the risks, fees, and applicable eligibility requirements.

Contact GCIC Finserve to discuss your investment requirements.

Frequently Asked Questions

Q1. Is PMS better than mutual funds?

Not automatically. PMS may offer greater customization, but it can involve different costs, concentration levels, and risks. Suitability depends on the investor’s requirements.

Q2. What is the minimum investment for PMS in India?

The general minimum investment requirement for PMS is ₹50 lakh, subject to applicable regulations and exceptions.

Q3. What is the minimum investment for AIFs?

The general minimum investment requirement for AIFs is ₹1 crore. Certain exceptions may apply, including provisions for accredited investors. Confirm the current rules before investing.

Q4. Can I invest in mutual funds, PMS, and AIFs together?

Yes, an investor may use different investment structures where appropriate. Each investment should have a clearly defined purpose and fit the overall portfolio strategy.

Q5. Should high-net-worth investors automatically move to PMS or AIFs?

No. A larger portfolio does not automatically make a complex investment product suitable. Goals, risk tolerance, liquidity, costs, and investment knowledge should be evaluated first.

Final Word

The comparison of mutual funds vs PMS and AIFs is not about choosing the most sophisticated product. It is about understanding how each structure works and whether it supports your financial goals.

Mutual funds, PMS, and AIFs have different features, costs, risks, and liquidity conditions. Evaluate each option carefully, review the relevant documents, and make decisions based on your individual circumstances.

Disclaimer: This article is intended solely for educational and informational purposes and should not be construed as investment advice. Investments in mutual funds, PMS, and AIFs are subject to market and other risks. Please review all relevant product and scheme documents and consult an appropriately registered professional before investing.

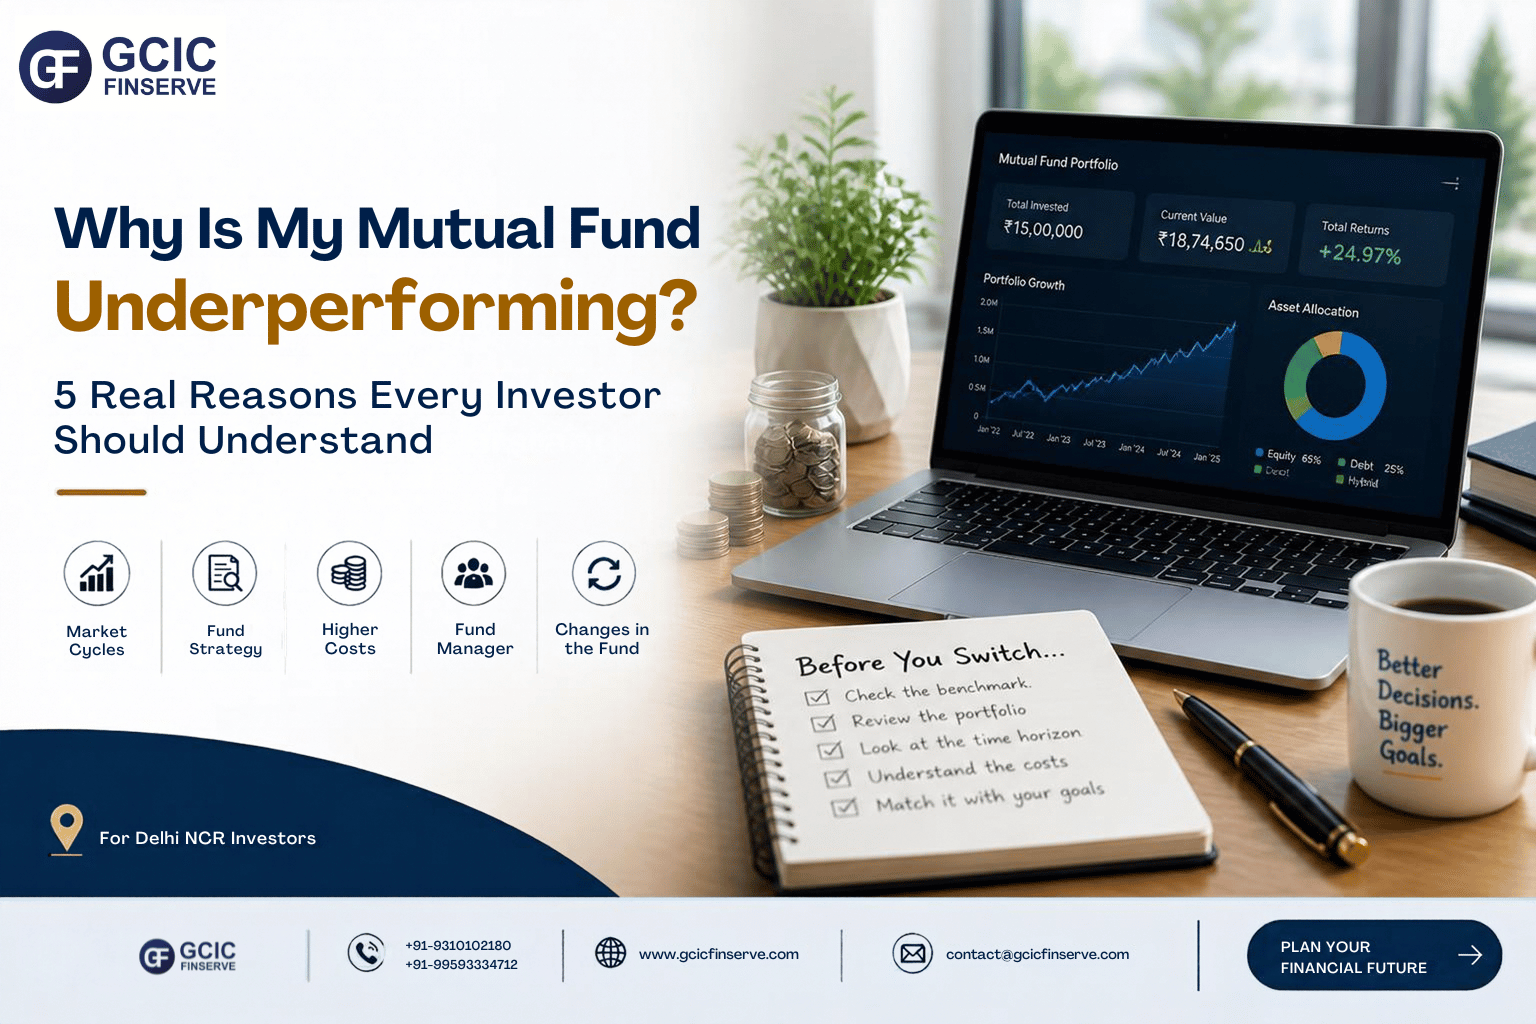
Why Is My Mutual Fund Underperforming? 5 Real Reasons Every Delhi NCR Investor Should Understand

Why is my mutual fund underperforming – 5 real reasons explained
Should you invest in 10 mutual funds portfolio diversification
More mutual funds do not always mean better diversification.

Why is my mutual fund underperforming? It’s the question that hits the moment you spot a friend’s fund or a WhatsApp forward showing higher returns than your own. Across Delhi NCR, this is one of the most common triggers for investors to impulsively switch funds, often without actually understanding what’s behind the gap. Before you make that call, it helps to know that a fund can deliver positive returns and still technically be “underperforming”—and that alone isn’t always a red flag.

What Does “Underperforming” Actually Mean?

Underperformance simply means a fund has delivered lower returns than an appropriate reference point—its benchmark, its category, or a comparable peer—over a specific period. If your fund returned 10% while its benchmark returned 14%, that’s a 4-point gap. But looking at just one period can be misleading, since different investment strategies perform differently across market cycles. A fund trailing today may lead tomorrow once conditions shift—which is exactly why understanding why my mutual fund is underperforming matters more than reacting to a single number.

5 Real Reasons a Mutual Fund Can Underperform

1. Its Investment Style Is Temporarily Out of Favor

A value-oriented fund can lag when growth stocks are leading the market, and a defensive portfolio may not fully participate in a sharp rally. This doesn’t mean the fund manager has erred—it may simply be positioned differently from what the market is currently rewarding.

2. It’s Going Through a Difficult Market Cycle

If the sectors a fund holds significant exposure to fall out of favor, its returns can trail benchmarks and peers for a stretch—particularly relevant for actively managed funds whose positioning differs meaningfully from an index.

3. The Fund Manager’s Calls Haven’t Worked Out

Active management means making decisions that differ from the benchmark. Some work, some don’t. If a fund manager’s decisions consistently fail to add value over a meaningful period, that’s when persistent underperformance deserves closer investigation.

4. Higher Costs Are Eating Into Returns

Expenses reduce what actually reaches investors. Two funds with near-identical portfolios can produce different investor returns purely due to differences in expense ratios—which is exactly why performance should be judged after costs, not just on paper.

5. The Fund Itself Has Changed

Fund managers change, investment processes evolve, and portfolios can end up looking quite different from what you originally signed up for. If the reason you picked the fund no longer holds true, that’s worth attention—even before returns reflect the shift.

Stop Comparing Every Fund to the Nifty

One of the biggest mistakes behind “why is my mutual fund underperforming” panic is comparing every scheme directly to the Nifty 50. A small-cap fund, a debt fund, and a large-cap fund all have completely different mandates, so their performance should be judged against the appropriate benchmark and category—not a single headline index. The real question isn’t “did my fund beat the market?” It’s “Did my fund perform reasonably well relative to what it’s actually designed to compete with?”

How Long Should You Wait Before Judging a Fund?

There’s no universal timeframe that fits every fund. Short-term performance is heavily influenced by market conditions, so a few weak months — or even a year — may not say much about a long-term strategy’s quality. A more meaningful review looks at performance across different market cycles and an appropriate investment horizon. According to AMFI India’s investor education resources, evaluating a fund against its category and benchmark over a longer, relevant period gives a far more accurate picture than a single year’s snapshot.

Should You Switch Your Mutual Fund?

Not simply because another fund performed better recently. Switching purely on recent performance often traps investors in a costly cycle—selling a fund after weakness and buying another right after it has already run up. Instead, first understand why your fund underperformed and whether that reason is likely to persist. If its strategy, management, and risk profile remain appropriate, temporary underperformance may not require any action at all. A review becomes genuinely worthwhile when underperformance is persistent, hard to explain, or accompanied by real changes in fund management or strategy.

GCIC Finserve’s Take for Delhi NCR Investors

At GCIC Finserve, when Delhi NCR clients ask, “Why is my mutual fund underperforming?” we don’t jump straight to a switch—we look at the fund’s benchmark-relative performance, category consistency, portfolio positioning, and whether it’s still serving its original purpose in the portfolio. As an AMFI-registered Mutual Fund Distributor (ARN-272705), our team helps you separate a fund that genuinely needs replacing from one that’s simply going through a normal market cycle.

FAQs

Q1. Why is my mutual fund underperforming the market? It could be due to its investment style being out of favor, sector exposure, costs, fund manager decisions, or changes in the fund’s strategy—not necessarily poor management.

Q2. Should I sell a mutual fund after one year of underperformance? Not necessarily. One year can reflect normal market cycles rather than a genuine problem—compare it against its appropriate benchmark and category first.

Q3. Should I switch to whichever fund has the highest recent returns? Not automatically. Chasing recent performance often means buying high after a fund has already run up—evaluate based on strategy and suitability instead.

Q4. What should I check before replacing an underperforming fund? Its benchmark and category performance, consistency across periods, portfolio positioning, costs, and whether it still fits your original goal and risk profile.

Final Word

The next time you catch yourself asking, “Why is my mutual fund underperforming?” resist the urge to switch immediately. Understand the reason first—market cycle, style, costs, or a genuine change in the fund—and only then decide if action is actually needed. A fund doesn’t need to top the charts every year to remain the right investment for you.


Disclaimer: This article is intended solely for educational and informational purposes and should not be construed as investment advice. Mutual fund investments are subject to market risks. Please review scheme-related documents and consult a registered advisor before investing.

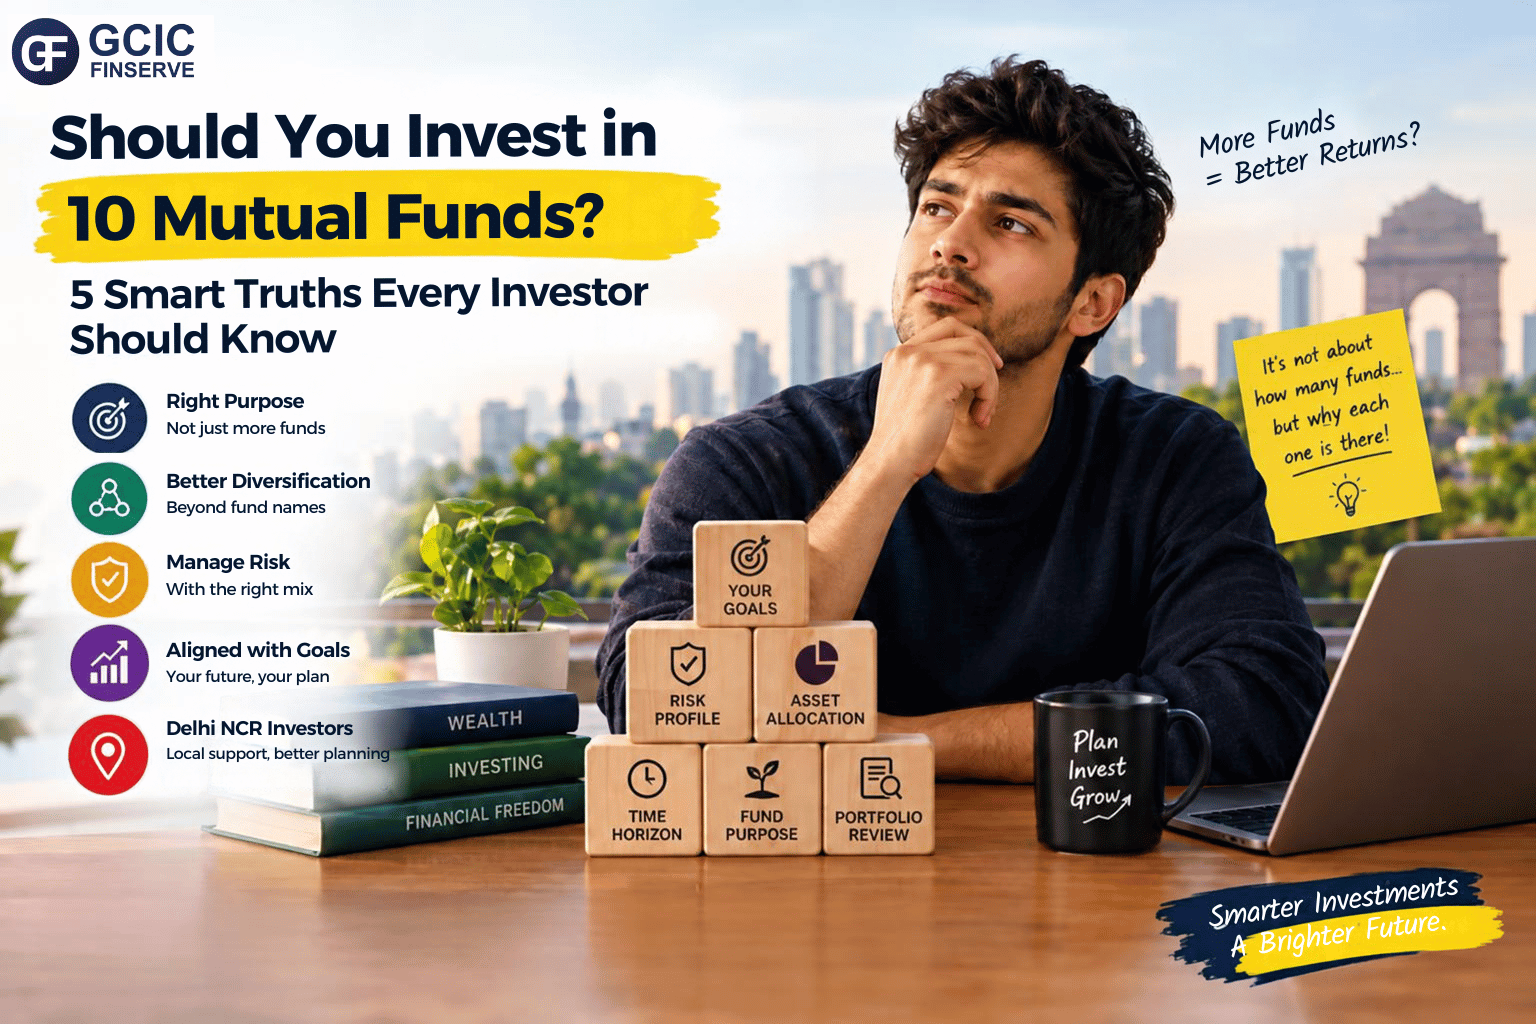
Should You Invest in 10 Mutual Funds? 5 Smart Truths Every Delhi NCR Investor Should Know

Should you invest in 10 mutual funds portfolio diversification
More mutual funds do not always mean better diversification.

Should you invest in 10 mutual funds to achieve proper diversification?
This is a common question among Delhi NCR investors who started with one or two SIPs and gradually added more funds.

One mid-cap fund here, one flexi-cap fund there, and another scheme recommended by a friend can eventually turn into a portfolio of ten or more mutual funds.

But owning ten mutual funds and being genuinely diversified are not necessarily the same thing.

The important question is not simply how many funds you own. It is whether each fund has a clear purpose and contributes meaningfully to your overall financial goals.

1. Why the Number of Funds Isn’t the Real Question

Diversification depends on what your investments actually hold, rather than the number of schemes in your portfolio.

For example, three large-cap mutual funds may invest in many of the same companies. Although the fund names and fund managers are different, their underlying holdings may overlap significantly.

This means a portfolio can appear diversified while still having considerable exposure to the same stocks or sectors.

Before adding another mutual fund, consider:

  • Underlying stock holdings
  • Overall asset allocation
  • Investment time horizon
  • Risk tolerance
  • The purpose of each fund
  • Your financial goals

Instead of focusing only on the number of schemes, understand how each investment fits into your complete portfolio.

2. How Mutual Fund Portfolios Quietly Become Overcrowded

Most investors do not intentionally decide to create a portfolio of ten mutual funds.

It often happens gradually. A fund generates strong recent returns, a new category becomes popular, or someone recommends another SIP. Over time, more schemes are added without reviewing the existing investments.

This can create two common challenges.

Fund Overlap

Different mutual funds may hold similar companies or sectors. This can reduce the diversification benefit you expected from owning multiple schemes.

Portfolio Complexity

When you own too many funds, it may become difficult to understand:

  • Where your money is invested
  • Which funds serve similar purposes
  • Whether your asset allocation remains suitable
  • Which investments need periodic review

A larger portfolio is not automatically a better portfolio. Clarity and suitability matter.

3. Should You Invest in 10 Mutual Funds?

There is no universal number of mutual funds that every investor should own.

The appropriate number depends on factors such as your investment amount, financial goals, risk profile, time horizon, and the role of each scheme.

An investor with multiple financial goals and a diversified asset allocation may have different requirements from someone who is starting their first SIP.

For many investors with relatively straightforward goals, adding funds only to increase the number of schemes may not provide meaningful benefits.

Before investing in another mutual fund, ask yourself:

What does this fund add to my existing portfolio that I do not already have?

If you cannot clearly explain its purpose, take time to review your existing investments before adding another scheme.

4. A Simple Test Before Adding Another Fund

Before deciding whether you should invest in 10 mutual funds or maintain a smaller portfolio, ask yourself these three questions.

1. Does the Fund Have a Different Purpose?

Does the new fund serve a different investment objective from your existing schemes?

Avoid adding a fund merely because it belongs to a different category or has recently delivered strong returns.

2. Does It Improve Diversification?

Review the fund’s underlying holdings and sector exposure. Different fund names do not necessarily mean different investments.

3. Would You Choose It Today?

Imagine that you were building your portfolio from scratch.

Would you still select this fund based on your current goals, risk profile, and investment strategy?

This question can help identify investments that remain in a portfolio simply because they were purchased in the past.

5. What If You Already Own 10 or More Funds?

If you already own ten or more mutual funds, do not rush to sell them only because the number appears high.

Instead, begin with a structured portfolio review.

Step 1: List All Your Funds

Prepare a list of your mutual funds, investment amounts, SIP contributions, and financial goals.

Step 2: Understand Each Fund’s Role

Identify whether each scheme is intended for long-term growth, a specific goal, diversification, or another purpose.

Step 3: Review Portfolio Overlap

Check whether multiple funds have similar holdings, sector exposure, or investment objectives.

Step 4: Review Your Asset Allocation

Understand your overall exposure to equity, debt, and other asset classes according to your financial needs and risk profile.

Step 5: Consider Consolidation Carefully

After reviewing the portfolio, you may identify opportunities to simplify your investments. Any decision to switch or redeem should consider factors such as taxes, exit loads, investment goals, and suitability.

The objective should not be reaching an arbitrary number of funds. The objective should be creating a portfolio that is understandable and aligned with your financial goals.

6. GCIC Finserve’s Approach for Delhi NCR Investors

At GCIC Finserve, we believe the right question is not simply, “Should you invest in 10 mutual funds?”

The more important question is:

Does every mutual fund in your portfolio have a clear reason to be there?

As an AMFI-registered Mutual Fund Distributor (ARN-272705), GCIC Finserve helps investors understand their portfolio structure, identify potential overlap, and review investment choices in the context of their financial goals.

Investors in South Delhi, Gurgaon, Noida, Ghaziabad, and other parts of Delhi NCR can consider reviewing their existing portfolio before adding another scheme.

You can explore our Financial Assessment page or visit our Contact Us page to learn more about the available services.

For investor education and mutual fund-related resources, visit AMFI India.

7. Frequently Asked Questions

Q1. Should you invest in 10 mutual funds?

It depends on your financial goals, risk profile, asset allocation, and the purpose of each fund. The number of schemes alone does not determine diversification.

Q2. How many mutual funds should I own?

There is no fixed number that applies to every investor. Choose investments based on your goals and whether each fund serves a distinct purpose.

Q3. Can different mutual funds hold the same stocks?

Yes. Different mutual funds can hold many of the same companies. This is known as portfolio overlap.

Q4. Should I sell my mutual funds if I own 10 or more?

Not automatically. Review each fund’s role, holdings, costs, tax implications, and suitability before making any decision.

Q5. How can I identify mutual fund overlap?

You can compare the underlying holdings, sector exposure, and investment objectives of your mutual funds. A portfolio review can help you understand similarities between schemes.

Final Word

The real question is not How many mutual funds should I own?

It is:

Does every fund in my portfolio have a clear reason to be there?

A portfolio with fewer funds may be easier to monitor, while a larger portfolio may be appropriate for certain investors and goals. What matters is whether your investments are suitable, understandable, and aligned with your financial plan.

Before adding your next mutual fund, review what you already own.

Disclaimer

This article is intended solely for educational and informational purposes and should not be construed as investment advice. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Consider your financial goals, risk profile, and investment horizon before making investment decisions.

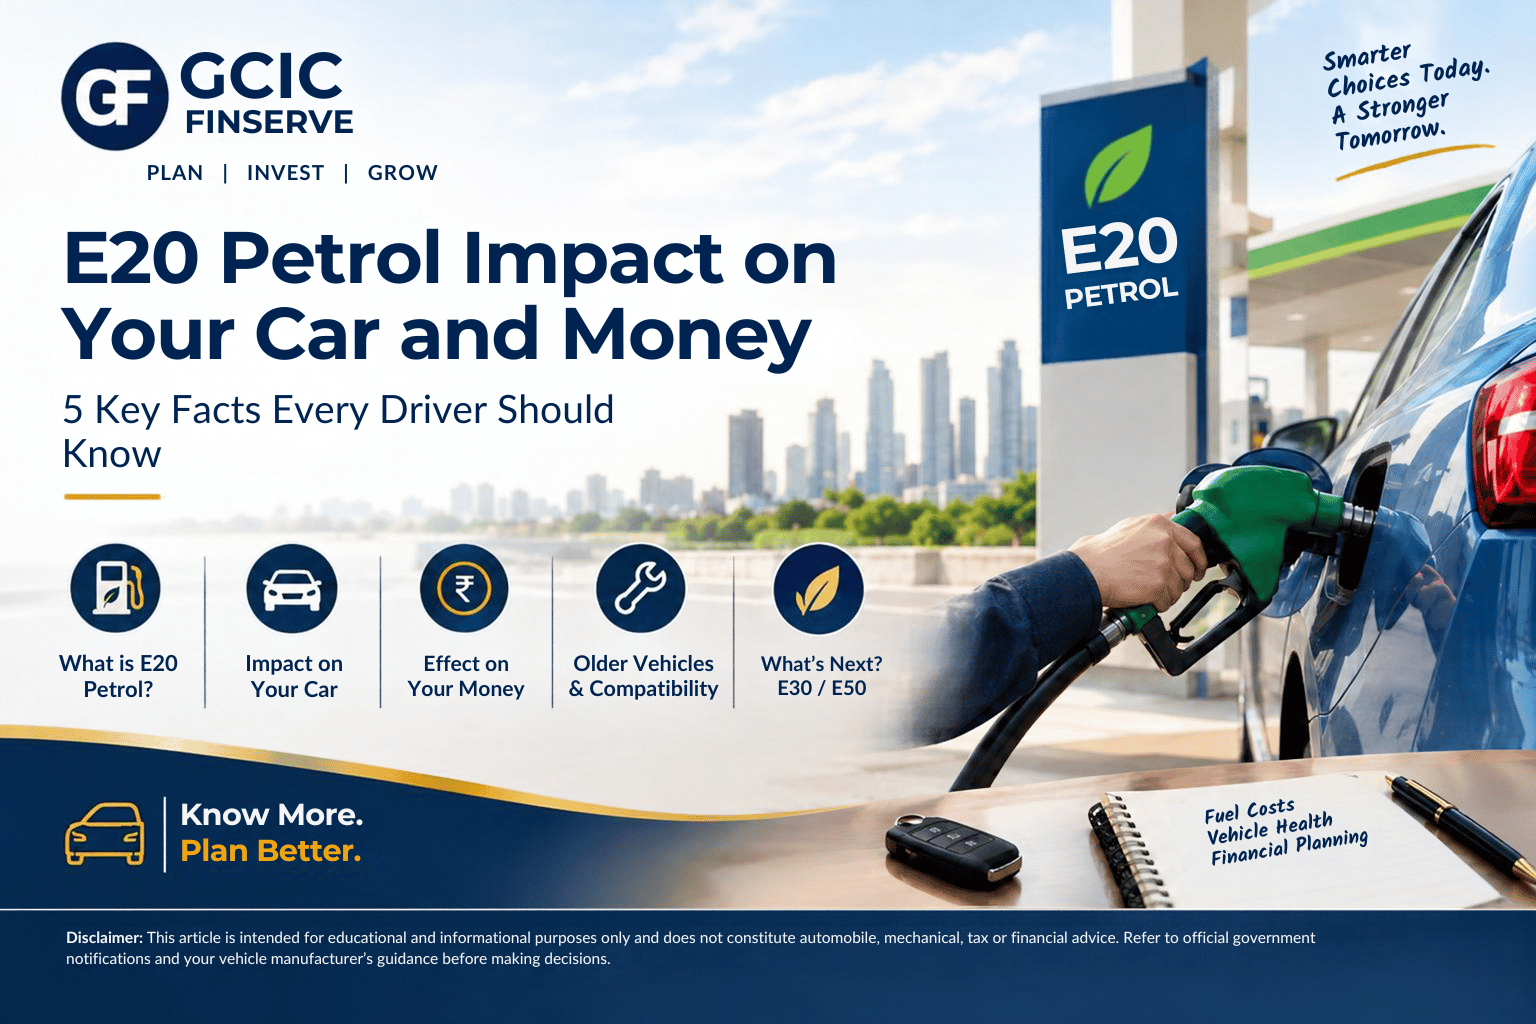
E20 Petrol Impact on Your Car and Money: 5 Key Facts Every Delhi NCR Driver Should Know

E20 petrol impact on your car and money for Delhi NCR drivers
Understanding E20 petrol, vehicle compatibility, and fuel expenses for Delhi NCR drivers.

E20 petrol impact on your car and money is an important topic for vehicle owners across Delhi NCR. Whether you drive in South Delhi, Gurugram, Noida or Ghaziabad, understanding E20 petrol can help you monitor your vehicle’s performance and household transportation expenses.

E20 petrol contains up to 20% ethanol blended with petrol. India’s ethanol-blending program aims to reduce crude-oil import dependence, support domestic production, and improve energy security.

But what does E20 mean for your car, mileage, and monthly expenses? Let’s understand the key points without relying on social media rumors. For official updates, readers can visit the Government of India PIB website

1. What Is E20 Petrol?

E20 petrol is fuel containing up to 20% ethanol blended with petrol.

Ethanol is an alcohol-based fuel produced from sources such as sugarcane and grains. India’s ethanol-blending program is intended to reduce dependence on imported crude oil and support domestic energy objectives.

The Government of India has stated that the E20 rollout followed testing and consultation involving automobile manufacturers, technical institutions, and other stakeholders.

However, fuel compatibility and vehicle performance can vary depending on the vehicle’s design, calibration, age, and maintenance.

2. How E20 Can Affect Your Car

One of the most discussed concerns is whether E20 petrol can damage vehicle engines.

Understanding the E20 petrol impact on your car and money requires looking at vehicle compatibility, fuel efficiency, and maintenance requirements. The government has stated that testing and field experience have not established widespread engine damage in E20-compatible vehicles. However, individual vehicle performance may differ, and owners should follow the manufacturer’s recommendations.

Ethanol contains less energy per liter than petrol. As a result, some vehicles may experience a reduction in fuel efficiency, depending on their engine calibration and operating conditions.

Mileage can also be affected by:

  • Traffic conditions
  • Driving habits
  • Tyre pressure
  • Vehicle maintenance
  • Air-conditioning usage
  • Fuel quality
  • Vehicle age and design

Therefore, a change in mileage should not automatically be attributed to E20 without proper assessment.

3. E20 Petrol Impact on Your Money

The E20 petrol impact on your car and money is especially relevant for people who drive long distances every month.

Suppose your vehicle’s mileage changes slightly. Your monthly fuel requirement may increase if you travel the same distance. Over time, this could affect your household transportation budget.

However, the actual impact depends on your vehicle, driving pattern, fuel prices, and distance travelled.

Instead of assuming a fixed cost increase, track your fuel expenses for a few months.

You can monitor:

  • Monthly kilometres travelled
  • Fuel purchased
  • Average mileage
  • Monthly fuel expenditure
  • Changes in driving patterns

This information can help you understand your actual costs rather than relying only on general claims.

For Delhi NCR households, fuel expenses should be considered alongside other regular commitments such as rent, EMIs, education costs, insurance, and savings.

4. What Should Older Vehicle Owners Know?

Owners of older petrol vehicles should check their manufacturer’s guidance regarding ethanol compatibility.

The Government of India has stated that E20 has undergone testing for parameters such as engine durability, material compatibility, drivability, and fuel efficiency.

At the same time, vehicle owners should not ignore unusual symptoms.

If you experience:

  • Sudden mileage changes
  • Starting problems
  • Engine warning lights
  • Unusual vibrations
  • Performance issues
  • Fuel-system concerns

Consult a qualified mechanic or authorized service center.

Do not assume that ethanol is automatically responsible for every vehicle problem. Proper diagnosis is necessary.

5. Is E30 or E50 Petrol Coming?

There has been public discussion about higher ethanol blends, including E30 and E50.

However, the Government of India stated in July 2026 that no decision had been taken to increase ethanol blending with petrol beyond 20%. Any future decision would require scientific and technical studies and consultation with relevant stakeholders.

E85 fuel has been introduced for specially designed and certified flex-fuel vehicles. This does not mean that E85 has become the standard fuel for all petrol vehicles in India.

Therefore, vehicle owners should rely on official announcements and manufacturer guidance instead of social media speculation.

6. What Should Delhi NCR Drivers Actually Do?

Here are some practical steps for vehicle owners:

1. Check Your Vehicle’s Compatibility

Refer to your vehicle manufacturer’s official guidance regarding E20 petrol.

2. Track Your Mileage

Record your fuel consumption and compare it under similar driving conditions.

3. Maintain Your Vehicle

Follow the recommended servicing schedule and address unusual symptoms promptly.

4. Avoid Unverified Claims

Do not make vehicle or purchasing decisions based only on forwarded messages and social media videos.

5. Include Fuel Costs in Your Budget

If fuel is a major monthly expense, include it while planning your household budget and future vehicle purchase.

6. Compare Your Future Vehicle Options Carefully

If you are planning to purchase a vehicle, compare petrol, CNG, hybrid, and electric options based on your driving distance, budget, maintenance needs, and charging or refueling access.

7. Why This Matters Beyond the Petrol Pump

Fuel expenses are one part of a household’s broader financial planning.

A change in monthly transportation costs may influence how much money is available for:

  • Emergency savings
  • Insurance premiums
  • Education planning
  • Loan repayments
  • Long-term investments
  • Retirement planning

At GCIC Finserve, we believe financial planning should consider real-life expenses and changing household priorities.

Understanding your expenses can help you review your financial goals and make more informed decisions.

Your financial plan should reflect the way your life actually works.

Frequently Asked Questions

Q1. What is E20 petrol?

E20 petrol contains up to 20% ethanol blended with petrol.

Q2. Does E20 petrol damage car engines?

The government has stated that testing and field experience have not established widespread engine damage in E20-compatible vehicles. Vehicle owners should follow manufacturer recommendations and address specific problems through proper diagnosis.

Q3. Can E20 petrol reduce mileage?

It may affect fuel efficiency because ethanol contains less energy per liter than petrol. The actual effect depends on vehicle design, calibration, driving conditions, and maintenance.

Q4. Is E30 or E50 petrol mandatory in India?

As of the government clarification issued in July 2026, no decision had been taken to increase nationwide petrol blending beyond 20%.

Q5. Should I stop using my petrol vehicle?

Not solely because of online rumors. Check your vehicle’s compatibility, follow the manufacturer’s guidance, and consider your actual running costs.

Q6. How can fuel expenses affect financial planning?

Regular fuel expenses can influence your monthly cash flow. Tracking these costs can help you plan savings, investments, and other financial commitments more effectively.

Final Word

The E20 petrol impact on your car and money depends on several factors, including vehicle compatibility, mileage, driving habits, and monthly usage.

Instead of relying on panic or speculation, check official guidance, monitor your actual fuel expenses, and include transportation costs in your household budget.

Awareness and practical planning can help you make more informed financial decisions.

Disclaimer

This article is intended for educational and informational purposes only and does not constitute automobile, mechanical, tax or financial advice. Refer to official government notifications and your vehicle manufacturer’s guidance before making decisions.


Medical Emergency Preparedness in Delhi NCR: 7 Smart Tips for 2026

Medical emergency preparedness for Delhi NCR families with health insurance and emergency savings
Medical emergency preparedness helps families plan for unexpected healthcare expenses and protect their financial future.

Medical emergency preparedness is something many families think about only when an unexpected health situation occurs. A sudden hospital visit, surgery, or extended treatment can bring emotional stress along with significant financial expenses.

For families living in South Delhi, Gurugram, Noida, Ghaziabad, and other parts of Delhi NCR, having a basic financial preparedness plan can help them manage unexpected healthcare costs without unnecessarily disturbing money reserved for important goals.

The purpose is not to predict when an emergency will happen. It is to understand your health insurance, maintain accessible savings, and keep important documents organized.

Why Medical Emergency Preparedness Matters in Delhi NCR

Medical expenses can vary depending on the treatment, hospital, room category, medicines, diagnostic tests, and duration of hospitalization.

A medical emergency may involve more than the hospital bill. Families could also face expenses related to medicines after discharge, travel, temporary loss of income, and other household responsibilities.

This is why medical emergency preparedness should be considered as part of your overall financial planning.

The objective is simple:

Be prepared for unexpected expenses while protecting your family’s financial priorities.

The Financial Impact of a Medical Emergency

Imagine receiving an unexpected call from a hospital late at night.

Your immediate priority is the health of your family member. At the same time, you may need to arrange money, understand the estimated treatment cost, and check what your health insurance policy covers.

Without accessible funds, a family may need to borrow money or withdraw long-term investments at an inconvenient time.

Health insurance can help with eligible expenses, but coverage depends on the policy’s terms, conditions, exclusions, limits, and waiting periods.

Therefore, insurance and emergency savings can serve different purposes in a family’s financial preparedness plan.

7 Smart Steps for Medical Emergency Preparedness

1. Maintain a Separate Emergency Fund

Consider keeping a portion of your money in an easily accessible emergency reserve.

A commonly considered starting point is three to six months of essential household expenses. However, the appropriate amount depends on your income stability, family responsibilities, existing insurance and financial commitments.

The important factor is accessibility.

Emergency money should be suitable for short-term needs and should not depend entirely on selling long-term investments at short notice.

2. Review Your Health Insurance Regularly

Having health insurance is important, but purchasing a policy once and never reviewing it may not be sufficient.

Review your policy periodically and understand:

  • Sum insured
  • Waiting periods
  • Room-rent conditions
  • Exclusions
  • Co-payment requirements
  • Network hospitals
  • Claim conditions
  • Renewal terms

If your family size, income, or healthcare requirements change, reassess whether your existing coverage remains suitable.

You can explore health insurance planning in Delhi NCR to understand the factors involved in selecting insurance coverage.

Always read the policy wording carefully before making a decision.

3. Understand Where Your Emergency Money Is Kept

Emergency funds should be accessible when required.

Different financial products have different levels of liquidity, risk, withdrawal conditions, and taxation. Before using any financial product for emergency reserves, understand how quickly you can access the money and what conditions may apply.

Emergency money should prioritize accessibility and suitability over chasing higher returns.

The right option depends on your personal circumstances and financial requirements.

4. Keep Short-Term Needs Separate From Long-Term Investments

Money required for immediate expenses and money intended for long-term goals serve different purposes.

For example, investments planned for retirement or a child’s education may have a longer time horizon. Selling these investments suddenly during an emergency could affect the original financial objective.

Maintaining a separate emergency reserve may reduce the need to disturb long-term investments when an unexpected expense arises.

You can also review your mutual fund investment resources to understand available tools and investment information.

5. Keep Important Documents Accessible

During an emergency, searching for policy documents or account information can add unnecessary stress.

Keep important information organized, including:

  • Health insurance policy details
  • Policy number
  • Insurer contact information
  • Health card details
  • Nominee information
  • Important investment records
  • Bank account information
  • Emergency contact details

Family members should also know where these documents are stored and how to access them when necessary.

Avoid sharing sensitive financial or identity documents through unsecured channels.

6. Understand Expenses That Insurance May Not Cover

Health insurance does not necessarily cover every medical expense.

Depending on the policy, certain expenses may be subject to exclusions, limits, deductibles, co-payments, waiting periods, or other conditions.

For this reason, maintaining accessible savings alongside health insurance may help families manage expenses that arise during or after treatment.

For official insurance information and regulatory resources, you can visit the Insurance Regulatory and Development Authority of India (IRDAI).

Understand your policy before you need to use it.

7. Review Your Emergency Preparedness Every Year

Your financial circumstances can change over time.

A new child, change in income, home loan, increased family responsibilities, or a different health insurance requirement may affect your preparedness needs.

Set aside time at least once a year to review:

Emergency savings → Health insurance → Important documents → Short-term liquidity

You can also review your financial plan after a major life event, such as marriage, childbirth, job change, or retirement.

Regular reviews can help you identify gaps before they become urgent.

How GCIC Finserve Supports Investor Awareness

GCIC Finserve Limited helps investors understand financial products and available investment options, including mutual funds, fixed deposits, and other applicable solutions, subject to product features, eligibility, and relevant terms.

As an AMFI-registered mutual fund distributor, GCIC Finserve focuses on investor awareness and helping investors understand available options and associated risks.

For health insurance and other financial products, individuals should carefully review the relevant product documents, coverage conditions, exclusions, and applicable terms before making a decision.

You can learn more about GCIC Finserve and explore the available financial services.

Understand your options. Know the risks. Make informed decisions.

FAQs

Q1. What is medical emergency preparedness?

Medical emergency preparedness means maintaining accessible savings, understanding health insurance coverage, and organizing important financial documents so that an unexpected medical situation can be managed more effectively.

Q2. Is health insurance enough for a medical emergency?

Health insurance can help cover eligible medical expenses, subject to the policy’s terms, conditions, exclusions, and limits. An emergency reserve may also help with expenses that are not covered by the policy.

Q3. How much should I keep in an emergency fund?

A commonly considered starting point is three to six months of essential expenses. The appropriate amount depends on income stability, family responsibilities, existing savings, and financial commitments.

Q4. Should emergency money be invested?

Emergency money should prioritize accessibility and suitability for short-term needs. Before selecting a financial product, understand its risks, liquidity, withdrawal process, applicable charges, and taxation.

Q5. How often should I review my health insurance?

Review your health insurance at least annually and whenever there is a significant change in your family, income, or healthcare requirements. Always check the current policy terms.

Q6. Does health insurance cover every hospital expense?

Not necessarily. Coverage depends on the policy’s terms, exclusions, limits, waiting periods, and other conditions. Read the policy documents carefully and confirm the applicable coverage with the insurer.

Final Thoughts

A medical emergency cannot always be predicted, but families can prepare for its potential financial impact.

Maintaining accessible emergency savings, understanding health insurance coverage, organizing important documents, and separating short-term needs from long-term investments can support better financial preparedness.

You cannot predict tomorrow. But you can prepare for it.

Disclaimer

Insurance products are subject to policy terms, conditions, exclusions, waiting periods, and other applicable provisions. Mutual fund investments are subject to market risks, including the potential loss of capital, liquidity risk, and market volatility. Please read all relevant policy and scheme-related documents carefully before making a financial decision. This article is provided for general educational and informational purposes only and should not be considered insurance, financial, investment, legal, or tax advice.

Is Your Mutual Fund Portfolio Growing Enough? 5 Smart Checks Every Delhi NCR Investor Should Run

mutual fund portfolio growing enough for long term financial goals
Is your mutual fund portfolio growing enough to support your financial goals?

Is your mutual fund portfolio growing enough—or just growing? Most investors in Delhi NCR know exactly how much their portfolio is worth today, but far fewer stop to ask if it’s growing at the rate they actually need. Watching your money move from ₹20 lakh to ₹25 lakh feels encouraging, but if that growth is genuinely “enough,” it depends entirely on what the money is meant to fund, when you’ll need it, and how much your goal will actually cost by then.

What Does “Growing Enough” Really Mean?

There’s no universal number that makes a return “good” for every investor. Someone investing for retirement 20 years away and someone saving for a house in Gurugram in 3 years could both have ₹25 lakh invested—yet their portfolios need to behave completely differently. If a mutual fund portfolio is growing enough depends on your financial goal, time horizon, inflation, current corpus, ongoing contributions, and risk profile. A portfolio should never be judged in isolation—only against the job it’s actually meant to do.

Why Inflation Matters for Your Mutual Fund Portfolio

Inflation is one of the biggest reasons Delhi NCR investors underestimate how much they truly need. If you want ₹1 crore for a goal 15 years away and inflation averages around 6%, the purchasing power of that ₹1 crore today could require closer to ₹2.4 crore by the time you reach your goal. So the real question isn’t “Can I build ₹1 crore?”—it’s “How much will my goal actually cost when I get there?” Your strategy should be based on this future value, not today’s price tag.

Don’t Judge a Single Year’s Return

Mutual fund returns swing considerably year to year, especially in equity. A portfolio might deliver 15% one year, dip 8% the next, and recover strongly after that. Looking only at the last 12 months can give a misleading picture of whether your mutual fund portfolio is growing enough. For long-term investors, metrics like CAGR, rolling returns, and XIRR—particularly useful for SIP investors since money enters at different points in time—offer a far more honest read of your actual trajectory.

Your Mutual Fund Portfolio Doesn’t Have to Beat the Nifty

A common mistake is comparing every portfolio against the Nifty 50. If the index delivers 14% and your portfolio delivers 11%, that doesn’t automatically mean it has underperformed. The Nifty 50 represents a specific set of large-cap companies, while your portfolio may hold a mix of large-cap, mid-cap, and debt funds designed to balance growth with stability. The more meaningful comparison runs from your portfolio to an appropriate benchmark to category performance and finally to the return your specific goal actually requires.

The Return You Need Is More Important Than the Return You Want

There’s a real difference between “what’s the highest return I can chase?” and “what return does my plan actually need?” If your goal requires an average of 10% over 15 years, chasing funds that recently delivered 18–20% may mean taking on far more risk than necessary. On the flip side, if your portfolio is tracking closer to 6% while your plan needs 10%, staying invested without a review could leave your mutual fund portfolio short of the target. The objective isn’t maximum return at any cost—it’s a reasonable return for the risk your goal actually requires.

5 Smart Checks: Is Your Mutual Fund Portfolio Growing Enough?

  1. What is this portfolio meant to achieve? Every investment should have a defined purpose.
  2. How much will I actually need? Factor in inflation and any changes to your goal’s future cost.
  3. How much time do I have? A 15-year horizon is evaluated very differently from a 3-year one.
  4. What return does my plan require? Work backwards from your goal instead of chasing an arbitrary number.
  5. Am I on track? Compare your current corpus and contribution rate against what you’re likely to need.

If your answer to that final question is no, identify why before switching funds impulsively—it could simply mean investing a little more each month rather than chasing a “better” fund.

When Should You Actually Be Concerned?

A slow-growing portfolio isn’t automatically a problem, but a proper review becomes important if you notice consistent underperformance against an appropriate benchmark, an asset allocation that no longer matches your goals, excessive concentration in one fund or sector, a major change in your financial circumstances, or a goal approaching without sufficient capital built up. According to AMFI’s investor education resources, reviewing your fund’s category and benchmark performance periodically—rather than reacting to short-term swings—is a healthier way to judge whether your mutual fund portfolio is growing enough.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, we help Delhi NCR clients look beyond the headline return and ask the more important question: is your mutual fund portfolio genuinely growing enough for the life you’re planning? As an AMFI-registered Mutual Fund Distributor (ARN-272705), our team helps map your current investments against your real goals, time horizon, and risk profile. Book a portfolio review with our team before deciding whether your investments need a change.

FAQs

Q1. What is considered a good return for a mutual fund portfolio? There’s no universal number—it depends on your goal, time horizon, inflation, contributions, and risk profile.

Q2. Should my mutual fund portfolio always beat the Nifty 50? No. A diversified portfolio may have a different asset mix, so it should be compared against an appropriate benchmark, not just the index in the news.

Q3. How do I know if my mutual fund portfolio is growing enough? Compare your current corpus and monthly contributions against what your goal will realistically cost, factoring in inflation and your remaining time horizon.

Q4. How often should I review my mutual fund portfolio? A periodic review—rather than daily monitoring—helps confirm your investments, allocation, and goals remain aligned.

Final Word

The next time you check your investments, don’t just ask, “How much did I make?” Ask instead, “Is my mutual fund portfolio growing enough for where I actually want to go?” That’s the number that matters far more than last year’s headline return.


Disclaimer: This article is intended solely for educational and informational purposes and should not be construed as investment advice. Mutual fund investments are subject to market risks. Please review scheme-related documents and consult a registered advisor before investing.