SIP Investments in India Hit a Record High: 5 Smart Lessons Every Delhi NCR Investor Should Take Away

SIP investments in India hit a record high with ₹32,297 crore monthly contribution in August 2026
India’s monthly SIP contribution reached a record ₹32,297 crore in August 2026, according to AMFI data.

SIP investments in India hit a record high of ₹32,297 crore in August 2026—the highest monthly SIP contribution ever recorded by AMFI. Ten years earlier, in August 2016, that number was just ₹3,497 crore. That’s a more than nine-fold jump in a decade. But behind this headline number is a much more interesting story for Delhi NCR investors: how Indians are quietly changing the way they think about money and what the cost of waiting to invest actually looks like.

Just How Big Is India’s SIP Boom?

The scale becomes clear when you place the numbers side by side. Monthly SIP contributions rose from ₹3,497 crore in August 2016 to ₹32,297 crore in August 2026. Outstanding SIP accounts reached 10.75 crore, with 10.02 crore actually contributing that month, and SIP assets under management touched ₹18.62 lakh crore. AMFI also recorded 66.40 lakh new SIP registrations in August alone, against 53.82 lakh SIPs that were discontinued or completed—a net addition of roughly 12.58 lakh accounts in just one month. SIP investments in India hitting a record high comes as part of a much larger increase in SIP participation over the past decade. 

The Bigger Mutual Fund Story Behind the Numbers

SIPs are just one part of a much larger transformation. India’s overall mutual fund industry AUM stood at ₹87.08 lakh crore at the end of August 2026, up roughly six-fold from ₹15.63 lakh crore in August 2016. Mutual fund folios have grown from 10.86 crore in August 2021 to 28.35 crore in August 2026—more than a two-and-a-half-fold increase in just five years, with roughly 21.62 crore of those folios in equity, hybrid, and solution-oriented schemes. For Delhi NCR households, this points to something bigger than a passing trend: organized, systematic investing is becoming the norm rather than the exception.

Why Has the SIP Become So Popular?

The appeal is part mathematics, part psychology. Ask someone to invest ₹12 lakh in one go, and it immediately raises hard questions—where will the money come from, is the market at the right level, and what if it falls right after? Ask instead, “Can you invest ₹10,000 a month?” and the decision suddenly feels manageable. According to AMFI, a SIP, is simply a method of investing a fixed amount periodically in a mutual fund scheme, helping investors stay disciplined without trying to time the market. It’s worth remembering: a SIP is a method of investing, not an investment product in itself—the underlying mutual fund is what actually carries the risk and return.

The Real FOMO Isn’t About Missing the Next Rally

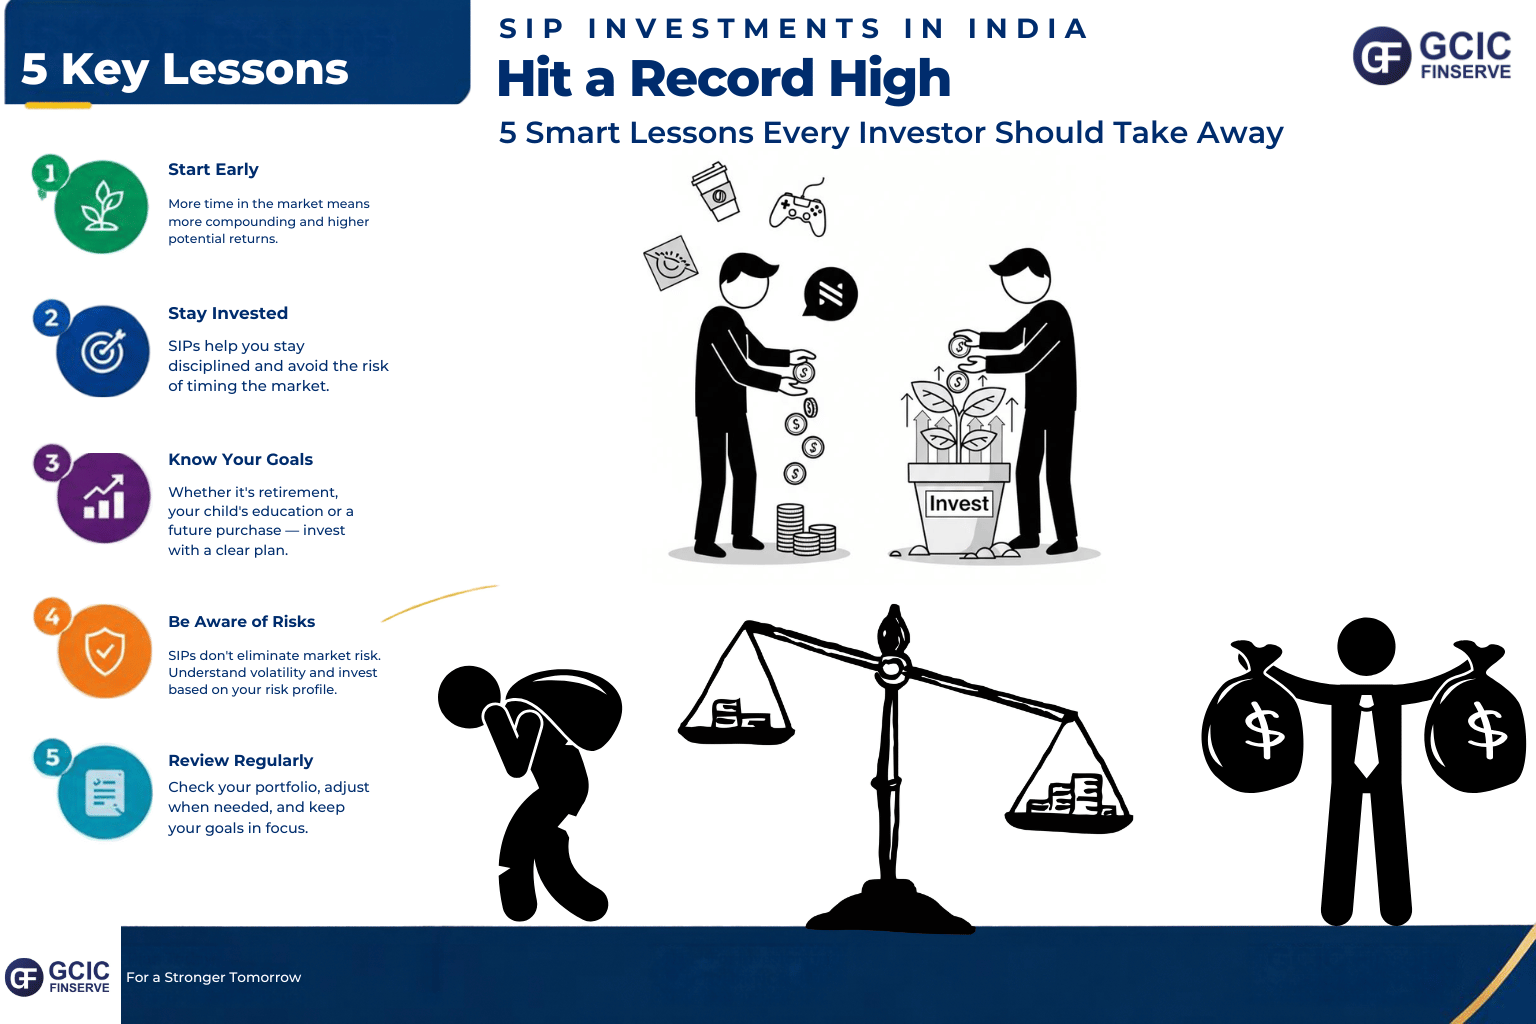
The common fear is “the market went up; I should have invested earlier.” But that’s not the FOMO that matters most. Consider two people who both could have started investing ₹10,000 a month five years ago—one did, one kept waiting for the “right time.” Five years later, the person who started has something the other person can never buy back: five years of investment time. You can increase your SIP amount later, change your strategy later, or even recover from a bad investment choice later—but you cannot recover lost time.

What Does Starting Early Actually Do?

Here’s a simple illustration. Investing ₹10,000 every month for 20 years means a total contribution of ₹24 lakh, which at an illustrative 12% annualized return could grow to approximately ₹99 lakh. Wait five years, and investing the same ₹10,000 monthly for only 15 years brings the total contribution down to ₹18 lakh, with an illustrative corpus of around ₹50 lakh. (These are hypothetical illustrations, not guaranteed returns—actual outcomes depend on market performance, fund selection, costs, and taxes.) The investor who waited contributed just ₹6 lakh less, yet the eventual illustrative gap is far larger—because those extra five years of compounding matter more than the headline contribution amount.

The Other Side of the SIP Story

Record SIP contributions shouldn’t push anyone into investing blindly. When your colleague has an SIP, your friend has three mutual funds, and headlines talk about ₹32,297 crore flowing in every month, it’s easy to feel like you’re “behind”—but that’s FOMO, not a strategy. The fact that millions of Delhi NCR residents (and Indians nationwide) are investing through SIPs doesn’t tell you what to invest in, how much risk to take, or which mutual fund category actually suits your goal. It’s also worth remembering that an SIP doesn’t remove market risk—if you’re invested in equity mutual funds, your value can still fall when markets fall. A SIP simply means you keep investing on schedule; it doesn’t eliminate volatility.

3 Questions to Ask Before Starting a SIP

Before jumping in because “SIP investments in India hit a record high” made headlines, ask yourself:

  1. What am I actually investing for? Retirement, a child’s education, or a future purchase can each call for a different approach.
  2. How long can I realistically stay invested? Your time horizon should match the volatility you’re willing to sit through.
  3. How much can I invest without disrupting my monthly budget? A sustainable SIP beats an aggressive one you can’t maintain past a few months.

GCIC Finserve’s Perspective for Delhi NCR Investors

At GCIC Finserve, AMFI-registered Mutual Fund Distributor (ARN-272705), we see the SIP boom as a genuine shift in household financial behavior—but record flows should never replace a plan built around your own goals and risk profile. If you have a long-term goal and keep postponing simply because the timing never feels perfect, it’s worth understanding what that delay is actually costing you in lost compounding time. Connect with our team to understand which mutual fund categories might suit your goals. For the latest official SIP and mutual fund industry data, refer to AMFI India’s official reports.

FAQs

Q1. Are SIP investments in India really at a record high?

Yes—AMFI reported ₹32,297 crore in monthly SIP contributions in August 2026, the highest in its published series.

Q2. Does a record SIP contribution mean the stock market will rise? No. SIP flows reflect investor participation, not a reliable signal of future market direction.

Q3. Is it too late to start a SIP now that contributions are at record highs? 

There’s no universal answer—it depends on your goals, horizon, and risk tolerance. But waiting indefinitely for a “perfect” entry point can mean losing valuable compounding time.

Q4. Does starting a SIP early guarantee higher returns? 

No. Starting earlier gives your investment more time to potentially compound, but actual returns still depend on market performance and the underlying fund.

Final Word

SIP investments in India hitting a record high isn’t a signal to rush in—it’s a signal that Indian investors, including many across Delhi NCR, are increasingly treating investing as a recurring habit rather than a one-time event. You don’t need to feel FOMO because someone else started before you. But if investing genuinely fits your goals, understand what indefinite postponement is costing you. The market will offer many entry points over your lifetime—time is the one entry point you can’t revisit.

Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. This article is for educational and informational purposes only and should not be construed as investment advice or a guarantee of returns. The illustrations used are hypothetical. Please assess your own financial circumstances and, where appropriate, consult a qualified financial professional before investing. Data source: Association of Mutual Funds in India (AMFI), August 2026.

SEBI’s Role in Regulating Mutual Funds in India

SEBI’s Role in Regulating Mutual Funds

Mutual funds have become one of the most popular investment options in India, offering investors a convenient way to diversify their portfolios and participate in market growth. However, to ensure transparency, fairness, and investor protection, the mutual fund industry needs strong regulation. In India, this responsibility lies with the Securities and Exchange Board of India (SEBI).

This article explores SEBI’s role in mutual funds regulation, the framework it has created, and how it safeguards the interests of millions of investors.

SEBI’s Role in Mutual Funds Regulation

SEBI, established in 1992, is the apex regulatory body for India’s securities and capital markets. One of its key responsibilities is overseeing the functioning of the mutual fund industry. The SEBI role in mutual funds regulation ensures that fund houses operate fairly, disclose accurate information, and maintain investor trust.

Through a comprehensive framework of guidelines, rules, and monitoring mechanisms, SEBI ensures that mutual funds remain transparent and investor-friendly.

SEBI Guidelines for Mutual Funds in India

SEBI has issued detailed SEBI guidelines for mutual funds India, covering everything from fund structure to investor disclosures. These guidelines include:

  • Registration Requirement: Only Asset Management Companies (AMCs) registered with SEBI can operate mutual funds.

  • Scheme Launch Approvals: AMCs must seek SEBI’s approval before launching any new fund scheme.

  • Transparency in Disclosures: Mutual funds are required to publish scheme details, investment objectives, risks, and historical performance.

  • Periodic Reporting: AMCs must disclose Net Asset Values (NAVs), portfolio holdings, and compliance reports regularly.

These measures ensure that investors have access to reliable and timely information before making investment decisions.

SEBI Mutual Fund Rules and Regulations

The SEBI mutual fund rules and regulations are designed to protect investors and maintain market integrity. Some key rules include:

  • Investment Limits: Restrictions on how much mutual funds can invest in a single company or sector to reduce risk.

  • Expense Ratio Caps: SEBI sets limits on fees charged by AMCs to prevent overcharging investors.

  • Riskometer Requirement: Every mutual fund must display a riskometer to indicate the level of risk associated with the scheme.

  • Fair Valuation: Rules ensure that securities are valued fairly, so investors are not misled about NAVs.

These regulations foster accountability and reduce the chances of mismanagement.

How SEBI Regulates Mutual Funds

Investors often ask, how SEBI regulates mutual funds on a day-to-day basis. SEBI does so through:

  1. Registration and Licensing – Approving AMCs and trustees after thorough scrutiny.

  2. Regular Audits and Inspections – Conducting compliance checks and inspections of fund houses.

  3. Investor Grievance Redressal – Providing a platform for investors to raise complaints against fund houses.

  4. Monitoring Advertisements – Ensuring that mutual fund promotions are not misleading.

This continuous monitoring helps in maintaining transparency and accountability across the industry.

SEBI Mutual Funds Compliance in India

Compliance is at the heart of mutual fund governance. SEBI mutual funds compliance in India requires AMCs and trustees to follow strict operational and reporting norms. For instance:

  • All schemes must be approved by trustees.

  • Compliance officers must certify that the AMC follows SEBI rules.

  • Violations can lead to penalties, suspension, or cancellation of licenses.

Such strict compliance ensures that investor money is managed responsibly.

SEBI Mutual Fund Investor Protection

One of SEBI’s top priorities is SEBI mutual fund investor protection. It does this by:

  • Ensuring accurate disclosure of risks.

  • Making fund houses accountable for investor grievances.

  • Preventing fraudulent or unethical practices.

  • Educating investors through awareness campaigns.

By prioritizing investor interests, SEBI builds long-term confidence in mutual fund investments.

SEBI Regulations on Mutual Fund Companies

The SEBI regulations on mutual fund companies specify the roles and responsibilities of AMCs, trustees, and distributors. These regulations ensure that fund managers act in the best interest of investors rather than chasing profits. Some rules include:

  • AMCs must maintain high standards of integrity.

  • Trustees must oversee the performance and compliance of AMCs.

  • Fund managers must adhere to the investment objectives of schemes.

This creates a balanced governance system.

SEBI Mutual Fund Governance in India

Strong governance is the backbone of investor trust. SEBI mutual fund governance India mandates:

  • Independent trustees to monitor AMCs.

  • Separation of roles between trustees and fund managers.

  • Regular board meetings to review fund performance and compliance.

Such governance mechanisms reduce conflicts of interest and promote transparency.

SEBI Rules for Mutual Fund Investors

Investors are also given certain rights and protections under SEBI rules for mutual fund investors. These include:

  • Right to accurate disclosures of scheme details.

  • Right to redeem investments at prevailing NAVs.

  • Access to grievance redressal mechanisms.

  • Protection from mis-selling by distributors.

This investor-centric approach ensures that mutual funds remain a safe and reliable option.

SEBI Regulation of the Mutual Fund Industry

Overall, SEBI regulation of mutual fund industry has been instrumental in making mutual funds one of the fastest-growing investment products in India. By ensuring transparency, compliance, and governance, SEBI has created a framework that balances investor protection with industry growth.

Conclusion

SEBI’s role in regulating mutual funds in India is crucial for maintaining the stability and credibility of the financial markets. From enforcing SEBI mutual fund rules and regulations to ensuring SEBI mutual fund investor protection, the regulator has built a strong ecosystem of trust.

For investors, understanding how SEBI regulates mutual funds helps in making informed decisions. With SEBI’s continuous oversight, the Indian mutual fund industry is set to grow responsibly while safeguarding investor interests.

Understanding NAV in Mutual Funds: A Simple Guide

what is NAV in Mutual Funds

NAV in Mutual Funds is one of the most important concepts to understand when you start investing in mutual funds. If you are a beginner, you may have come across the term NAV and wondered what it means and how it affects your investment.

What is NAV in Mutual Funds?

NAV stands for Net Asset Value. In simple terms, it is the price of a single unit of a mutual fund scheme. Just like shares of a company have a market price, mutual fund units are valued at their NAV.

So, mutual fund NAV explained simply: It tells you how much one unit of a fund is worth at the end of a trading day.

NAV Meaning in Mutual Funds

The NAV meaning in mutual funds can be understood as:

In other words, it represents the per-unit value of the fund’s holdings after subtracting liabilities.

How NAV is Calculated in Mutual Funds

Fund houses calculate NAV every business day. Here’s a step-by-step NAV calculation example in mutual funds:

  1. Suppose a mutual fund owns stocks worth ₹100 crore and bonds worth ₹50 crore.

  2. It also has ₹5 crore cash and liabilities of ₹2 crore.

  3. Total assets = ₹100 + ₹50 + ₹5 = ₹155 crore.

  4. Net assets = ₹155 – ₹2 = ₹153 crore.

  5. If the fund has 10 crore units, then NAV = ₹153 ÷ 10 = ₹15.30 per unit.

This is how daily NAV in mutual funds India is calculated and published.

NAV vs Market Price in Mutual Funds

Many investors confuse NAV vs market price in mutual funds. Unlike stocks, mutual fund units do not trade on an exchange with fluctuating market prices. Their value is always based on the NAV declared at the end of each day.


Does NAV Affect Mutual Fund Returns?

A common doubt is: does NAV affect mutual fund returns? The answer is no. A fund with a low NAV doesn’t mean it will generate higher returns, and a fund with high NAV doesn’t mean it is expensive. Returns depend on how the underlying assets (stocks, bonds, etc.) perform—not on the NAV itself.

Importance of NAV in Mutual Fund Investment

The importance of NAV in mutual fund investment lies in:

  • Determining the number of units you get when you invest.

  • Helping you track your investment’s growth over time.

  • Ensuring transparency in how fund houses value their schemes.

But remember, when choosing a fund, don’t look only at the NAV—focus on the fund’s performance, portfolio quality, and consistency.

Final Thoughts

Understanding what is NAV in mutual funds is essential, but it’s only one part of your investment journey. Think of NAV as the entry price of your fund unit, not as a measure of performance. A fund with an NAV of ₹10 can give better returns than a fund with an NAV of ₹100, depending on its portfolio.

So, the next time you see the daily NAV of mutual funds in India, you’ll know exactly what it means—and why it should not be the only factor guiding your investment choices.

How to Invest in Mutual Funds

Getting started with mutual fund investing is simpler with GCIC Finserv. Contact us now