Is your mutual fund portfolio growing enough—or just growing? Most investors in Delhi NCR know exactly how much their portfolio is worth today, but far fewer stop to ask if it’s growing at the rate they actually need. Watching your money move from ₹20 lakh to ₹25 lakh feels encouraging, but if that growth is genuinely “enough,” it depends entirely on what the money is meant to fund, when you’ll need it, and how much your goal will actually cost by then.
What Does “Growing Enough” Really Mean?
There’s no universal number that makes a return “good” for every investor. Someone investing for retirement 20 years away and someone saving for a house in Gurugram in 3 years could both have ₹25 lakh invested—yet their portfolios need to behave completely differently. If a mutual fund portfolio is growing enough depends on your financial goal, time horizon, inflation, current corpus, ongoing contributions, and risk profile. A portfolio should never be judged in isolation—only against the job it’s actually meant to do.
Why Inflation Matters for Your Mutual Fund Portfolio
Inflation is one of the biggest reasons Delhi NCR investors underestimate how much they truly need. If you want ₹1 crore for a goal 15 years away and inflation averages around 6%, the purchasing power of that ₹1 crore today could require closer to ₹2.4 crore by the time you reach your goal. So the real question isn’t “Can I build ₹1 crore?”—it’s “How much will my goal actually cost when I get there?” Your strategy should be based on this future value, not today’s price tag.
Don’t Judge a Single Year’s Return
Mutual fund returns swing considerably year to year, especially in equity. A portfolio might deliver 15% one year, dip 8% the next, and recover strongly after that. Looking only at the last 12 months can give a misleading picture of whether your mutual fund portfolio is growing enough. For long-term investors, metrics like CAGR, rolling returns, and XIRR—particularly useful for SIP investors since money enters at different points in time—offer a far more honest read of your actual trajectory.
Your Mutual Fund Portfolio Doesn’t Have to Beat the Nifty
A common mistake is comparing every portfolio against the Nifty 50. If the index delivers 14% and your portfolio delivers 11%, that doesn’t automatically mean it has underperformed. The Nifty 50 represents a specific set of large-cap companies, while your portfolio may hold a mix of large-cap, mid-cap, and debt funds designed to balance growth with stability. The more meaningful comparison runs from your portfolio to an appropriate benchmark to category performance and finally to the return your specific goal actually requires.
The Return You Need Is More Important Than the Return You Want
There’s a real difference between “what’s the highest return I can chase?” and “what return does my plan actually need?” If your goal requires an average of 10% over 15 years, chasing funds that recently delivered 18–20% may mean taking on far more risk than necessary. On the flip side, if your portfolio is tracking closer to 6% while your plan needs 10%, staying invested without a review could leave your mutual fund portfolio short of the target. The objective isn’t maximum return at any cost—it’s a reasonable return for the risk your goal actually requires.
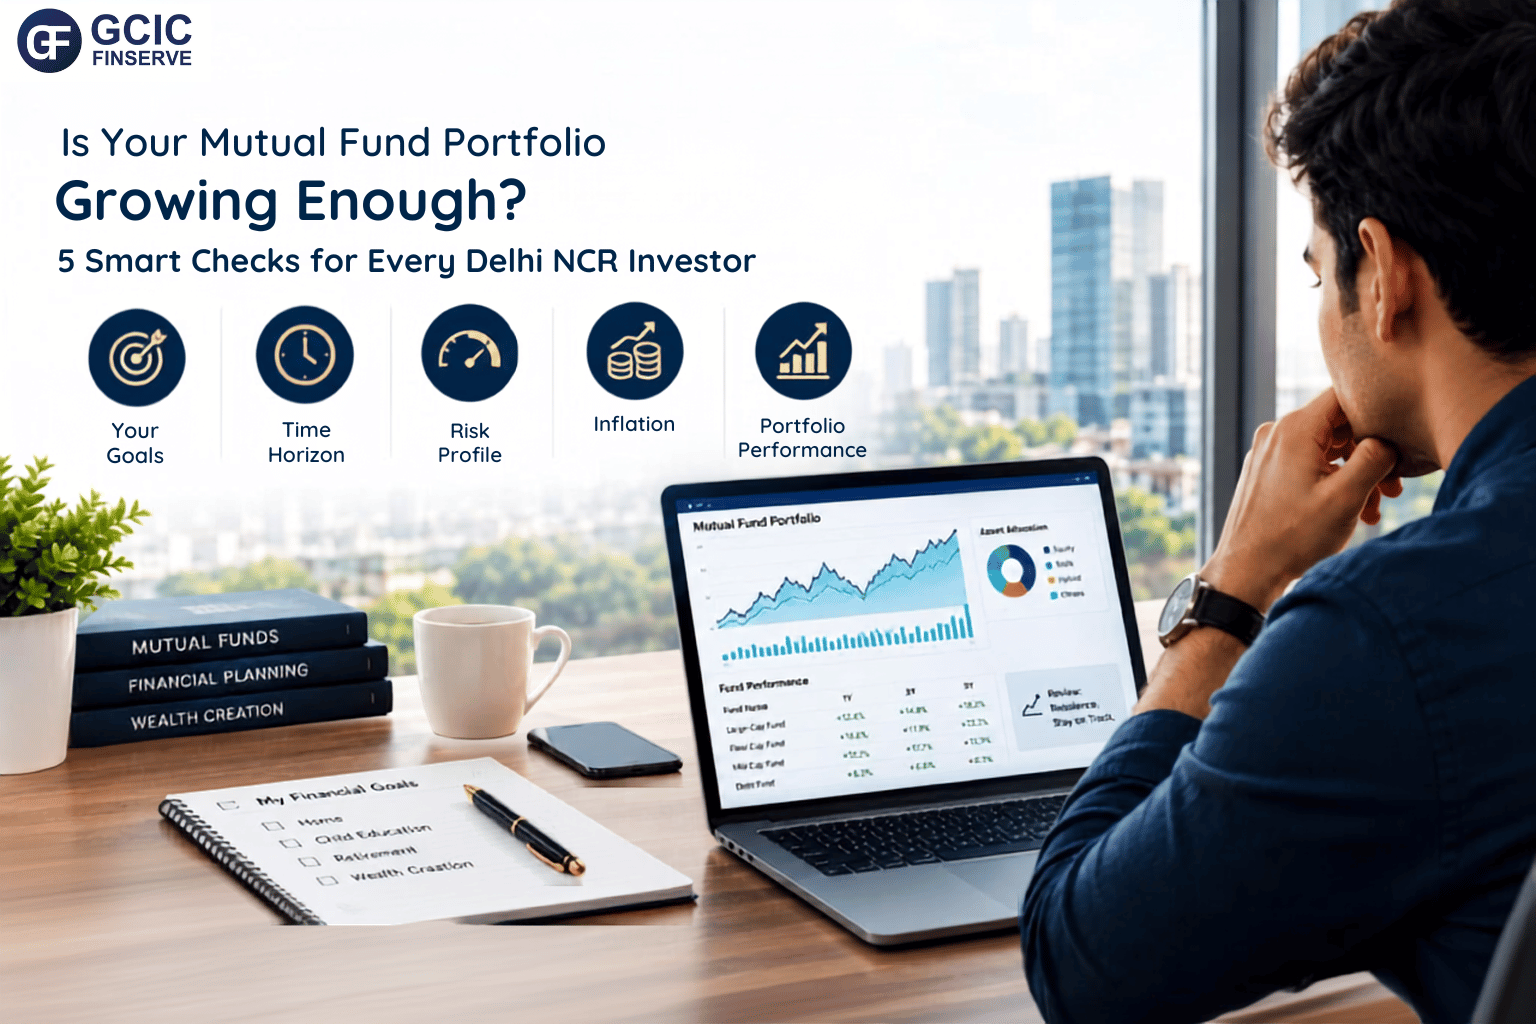
5 Smart Checks: Is Your Mutual Fund Portfolio Growing Enough?
- What is this portfolio meant to achieve? Every investment should have a defined purpose.
- How much will I actually need? Factor in inflation and any changes to your goal’s future cost.
- How much time do I have? A 15-year horizon is evaluated very differently from a 3-year one.
- What return does my plan require? Work backwards from your goal instead of chasing an arbitrary number.
- Am I on track? Compare your current corpus and contribution rate against what you’re likely to need.
If your answer to that final question is no, identify why before switching funds impulsively—it could simply mean investing a little more each month rather than chasing a “better” fund.
When Should You Actually Be Concerned?
A slow-growing portfolio isn’t automatically a problem, but a proper review becomes important if you notice consistent underperformance against an appropriate benchmark, an asset allocation that no longer matches your goals, excessive concentration in one fund or sector, a major change in your financial circumstances, or a goal approaching without sufficient capital built up. According to AMFI’s investor education resources, reviewing your fund’s category and benchmark performance periodically—rather than reacting to short-term swings—is a healthier way to judge whether your mutual fund portfolio is growing enough.
GCIC Finserve’s Perspective for Delhi NCR Investors
At GCIC Finserve, we help Delhi NCR clients look beyond the headline return and ask the more important question: is your mutual fund portfolio genuinely growing enough for the life you’re planning? As an AMFI-registered Mutual Fund Distributor (ARN-272705), our team helps map your current investments against your real goals, time horizon, and risk profile. Book a portfolio review with our team before deciding whether your investments need a change.
FAQs
Q1. What is considered a good return for a mutual fund portfolio? There’s no universal number—it depends on your goal, time horizon, inflation, contributions, and risk profile.
Q2. Should my mutual fund portfolio always beat the Nifty 50? No. A diversified portfolio may have a different asset mix, so it should be compared against an appropriate benchmark, not just the index in the news.
Q3. How do I know if my mutual fund portfolio is growing enough? Compare your current corpus and monthly contributions against what your goal will realistically cost, factoring in inflation and your remaining time horizon.
Q4. How often should I review my mutual fund portfolio? A periodic review—rather than daily monitoring—helps confirm your investments, allocation, and goals remain aligned.
Final Word
The next time you check your investments, don’t just ask, “How much did I make?” Ask instead, “Is my mutual fund portfolio growing enough for where I actually want to go?” That’s the number that matters far more than last year’s headline return.
Disclaimer: This article is intended solely for educational and informational purposes and should not be construed as investment advice. Mutual fund investments are subject to market risks. Please review scheme-related documents and consult a registered advisor before investing.