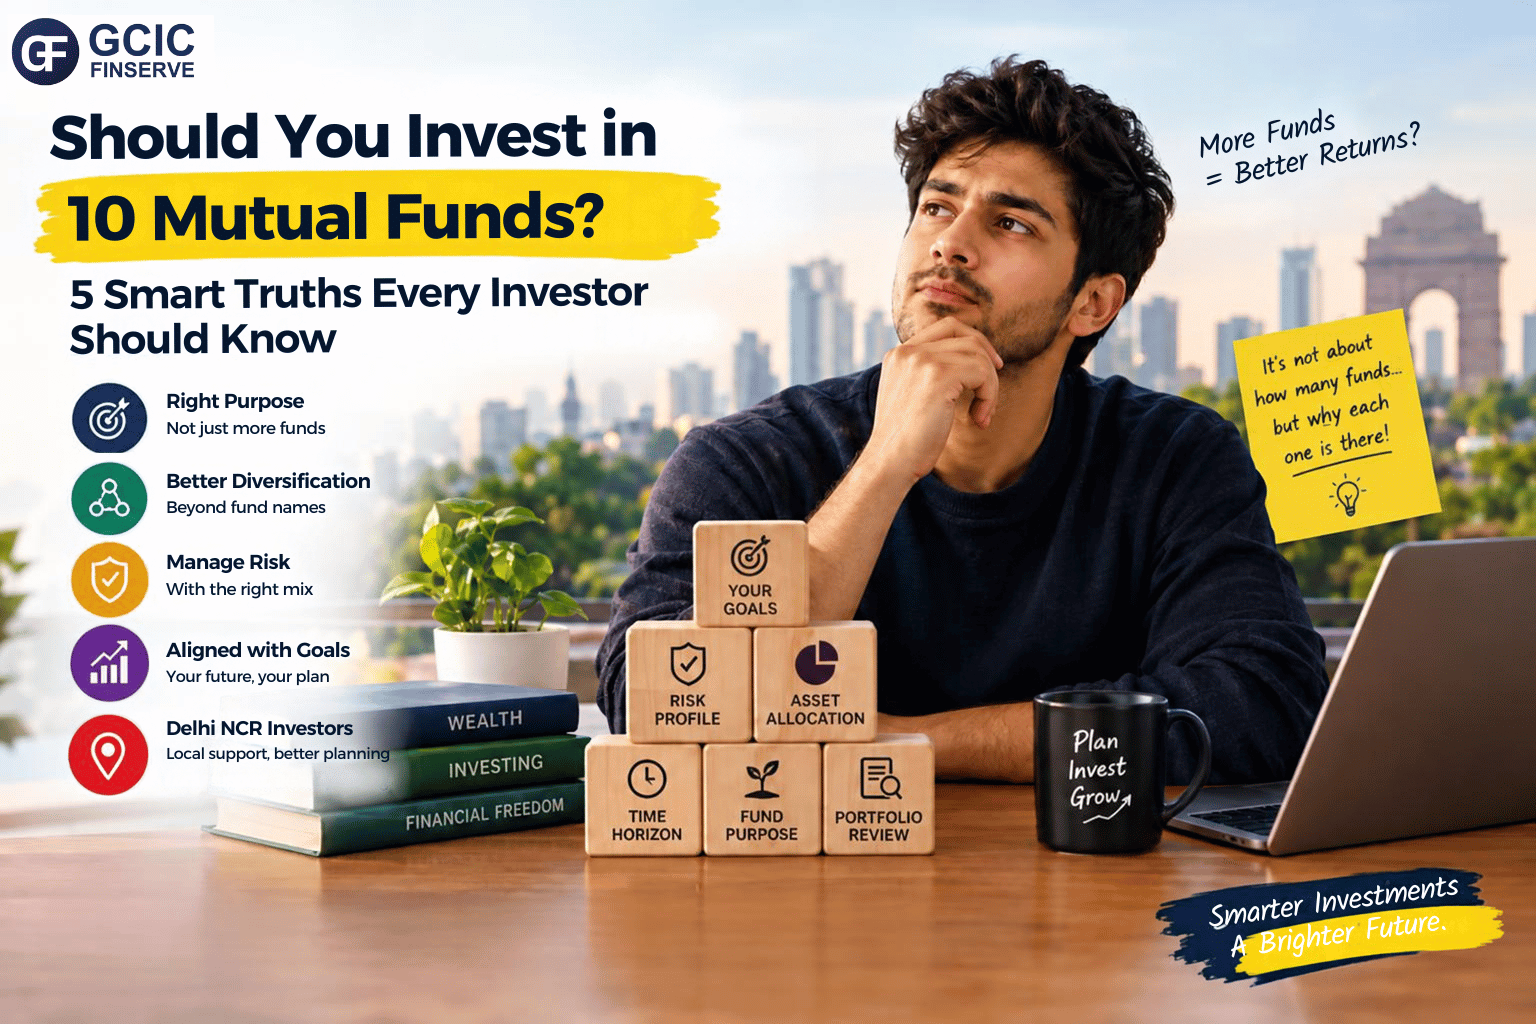
Should you invest in 10 mutual funds to achieve proper diversification?
This is a common question among Delhi NCR investors who started with one or two SIPs and gradually added more funds.
One mid-cap fund here, one flexi-cap fund there, and another scheme recommended by a friend can eventually turn into a portfolio of ten or more mutual funds.
But owning ten mutual funds and being genuinely diversified are not necessarily the same thing.
The important question is not simply how many funds you own. It is whether each fund has a clear purpose and contributes meaningfully to your overall financial goals.
1. Why the Number of Funds Isn’t the Real Question
Diversification depends on what your investments actually hold, rather than the number of schemes in your portfolio.
For example, three large-cap mutual funds may invest in many of the same companies. Although the fund names and fund managers are different, their underlying holdings may overlap significantly.
This means a portfolio can appear diversified while still having considerable exposure to the same stocks or sectors.
Before adding another mutual fund, consider:
- Underlying stock holdings
- Overall asset allocation
- Investment time horizon
- Risk tolerance
- The purpose of each fund
- Your financial goals
Instead of focusing only on the number of schemes, understand how each investment fits into your complete portfolio.
2. How Mutual Fund Portfolios Quietly Become Overcrowded
Most investors do not intentionally decide to create a portfolio of ten mutual funds.
It often happens gradually. A fund generates strong recent returns, a new category becomes popular, or someone recommends another SIP. Over time, more schemes are added without reviewing the existing investments.
This can create two common challenges.
Fund Overlap
Different mutual funds may hold similar companies or sectors. This can reduce the diversification benefit you expected from owning multiple schemes.
Portfolio Complexity
When you own too many funds, it may become difficult to understand:
- Where your money is invested
- Which funds serve similar purposes
- Whether your asset allocation remains suitable
- Which investments need periodic review
A larger portfolio is not automatically a better portfolio. Clarity and suitability matter.
3. Should You Invest in 10 Mutual Funds?
There is no universal number of mutual funds that every investor should own.
The appropriate number depends on factors such as your investment amount, financial goals, risk profile, time horizon, and the role of each scheme.
An investor with multiple financial goals and a diversified asset allocation may have different requirements from someone who is starting their first SIP.
For many investors with relatively straightforward goals, adding funds only to increase the number of schemes may not provide meaningful benefits.
Before investing in another mutual fund, ask yourself:
What does this fund add to my existing portfolio that I do not already have?
If you cannot clearly explain its purpose, take time to review your existing investments before adding another scheme.
4. A Simple Test Before Adding Another Fund
Before deciding whether you should invest in 10 mutual funds or maintain a smaller portfolio, ask yourself these three questions.
1. Does the Fund Have a Different Purpose?
Does the new fund serve a different investment objective from your existing schemes?
Avoid adding a fund merely because it belongs to a different category or has recently delivered strong returns.
2. Does It Improve Diversification?
Review the fund’s underlying holdings and sector exposure. Different fund names do not necessarily mean different investments.
3. Would You Choose It Today?
Imagine that you were building your portfolio from scratch.
Would you still select this fund based on your current goals, risk profile, and investment strategy?
This question can help identify investments that remain in a portfolio simply because they were purchased in the past.
5. What If You Already Own 10 or More Funds?
If you already own ten or more mutual funds, do not rush to sell them only because the number appears high.
Instead, begin with a structured portfolio review.
Step 1: List All Your Funds
Prepare a list of your mutual funds, investment amounts, SIP contributions, and financial goals.
Step 2: Understand Each Fund’s Role
Identify whether each scheme is intended for long-term growth, a specific goal, diversification, or another purpose.
Step 3: Review Portfolio Overlap
Check whether multiple funds have similar holdings, sector exposure, or investment objectives.
Step 4: Review Your Asset Allocation
Understand your overall exposure to equity, debt, and other asset classes according to your financial needs and risk profile.
Step 5: Consider Consolidation Carefully
After reviewing the portfolio, you may identify opportunities to simplify your investments. Any decision to switch or redeem should consider factors such as taxes, exit loads, investment goals, and suitability.
The objective should not be reaching an arbitrary number of funds. The objective should be creating a portfolio that is understandable and aligned with your financial goals.
6. GCIC Finserve’s Approach for Delhi NCR Investors
At GCIC Finserve, we believe the right question is not simply, “Should you invest in 10 mutual funds?”
The more important question is:
Does every mutual fund in your portfolio have a clear reason to be there?
As an AMFI-registered Mutual Fund Distributor (ARN-272705), GCIC Finserve helps investors understand their portfolio structure, identify potential overlap, and review investment choices in the context of their financial goals.
Investors in South Delhi, Gurgaon, Noida, Ghaziabad, and other parts of Delhi NCR can consider reviewing their existing portfolio before adding another scheme.
You can explore our Financial Assessment page or visit our Contact Us page to learn more about the available services.
For investor education and mutual fund-related resources, visit AMFI India.
7. Frequently Asked Questions
Q1. Should you invest in 10 mutual funds?
It depends on your financial goals, risk profile, asset allocation, and the purpose of each fund. The number of schemes alone does not determine diversification.
Q2. How many mutual funds should I own?
There is no fixed number that applies to every investor. Choose investments based on your goals and whether each fund serves a distinct purpose.
Q3. Can different mutual funds hold the same stocks?
Yes. Different mutual funds can hold many of the same companies. This is known as portfolio overlap.
Q4. Should I sell my mutual funds if I own 10 or more?
Not automatically. Review each fund’s role, holdings, costs, tax implications, and suitability before making any decision.
Q5. How can I identify mutual fund overlap?
You can compare the underlying holdings, sector exposure, and investment objectives of your mutual funds. A portfolio review can help you understand similarities between schemes.
Final Word
The real question is not How many mutual funds should I own?
It is:
Does every fund in my portfolio have a clear reason to be there?
A portfolio with fewer funds may be easier to monitor, while a larger portfolio may be appropriate for certain investors and goals. What matters is whether your investments are suitable, understandable, and aligned with your financial plan.
Before adding your next mutual fund, review what you already own.
Disclaimer
This article is intended solely for educational and informational purposes and should not be construed as investment advice. Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Consider your financial goals, risk profile, and investment horizon before making investment decisions.